
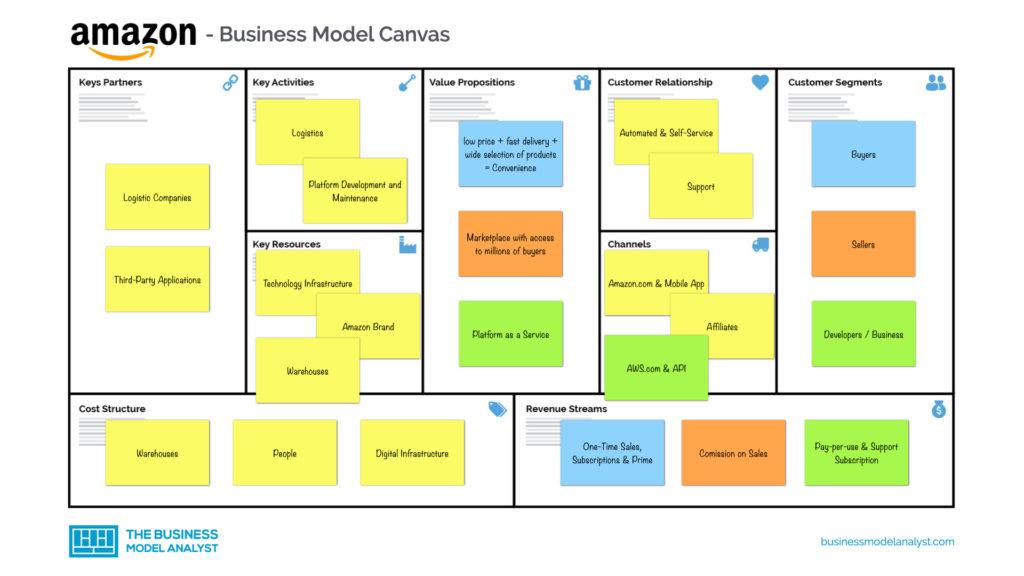

What it is: Amazon’s business model is a diversified, multi-sided platform that combines low-margin retail with high-margin digital businesses. Amazon sells its own products, lets millions of third-party sellers sell through its marketplace, and layers on subscriptions (Prime), advertising, and cloud computing (AWS). Retail brings the scale and the customers. AWS, advertising, and third-party services bring the profit.
The key takeaway: In 2025, Amazon generated $716.9 billion in net sales and $77.7 billion in net income, but most of the profit did not come from selling products. AWS alone produced $45.6 billion of operating income, roughly 57% of the company’s total $80 billion. Amazon runs its store close to breakeven and funds everything else with cloud and ad margins. In 2026, it is recycling that cash into an estimated $200 billion AI and infrastructure build, plus a satellite network (Amazon Leo) meant to rival Starlink.
One-line answer: Amazon makes money by losing the retail margin war on purpose, then winning on cloud, ads, and subscriptions that the retail scale makes possible.
Defining Amazon’s business model is a moving target. The company keeps expanding, year after year, into new geographies, new product categories, and entire new industries. Here is the fastest way to grasp the scale: in the time it takes you to read this article, Amazon will book a few million dollars in fresh revenue.
But scale is the easy part of the story. The interesting part is the design. Amazon is not one business. It is several businesses stacked on top of each other, each feeding the next, and the one most people think of (the online store) is deliberately the least profitable of the bunch.
Amazon by the numbers (FY2025)
Every figure below comes from Amazon’s Q4 and full-year 2025 earnings release, filed with the SEC.
| Metric (FY2025) | Figure | Change vs 2024 |
|---|---|---|
| Total net sales | $716.9B | +12% (from $638.0B) |
| Net income | $77.7B | +31% (from $59.2B) |
| Diluted EPS | $7.17 | +30% (from $5.53) |
| Total operating income | $80.0B | +17% (from $68.6B) |
| Operating cash flow (TTM) | $139.5B | +20% |
| Free cash flow (TTM) | $11.2B | Down sharply |
| Employees | ~1.5 million | Roughly flat |
That free cash flow number is the one competitors tend to skip, and it tells you exactly what Amazon is doing right now. Operating cash flow climbed to $139.5 billion, yet free cash flow fell to just $11.2 billion. The gap is capital spending. Amazon increased its purchases of property and equipment by more than $50 billion in a single year, almost all of it pointed at AI data centers and custom silicon. The store is printing cash, and management is pouring nearly all of it back into the ground.
How Amazon makes money
Amazon reports results across three segments (North America, International, and AWS), but the actual money machine runs on six engines. Here is what each one does and how it earns.
| Revenue engine | How it earns | Margin profile |
|---|---|---|
| Online stores (1P retail) | Amazon buys and resells products directly | Very thin |
| Third-party seller services | Referral fees, fulfillment (FBA), storage, and logistics charged to sellers | Healthy |
| AWS (cloud) | Compute, storage, database, and AI services billed by usage | High (the profit core) |
| Advertising | Sponsored Products, sponsored brands, and Prime Video ads | Very high |
| Subscriptions (Prime) | Membership fees plus the loyalty that drives repeat buying | High and recurring |
| Physical stores | Whole Foods, Amazon Fresh, and Go locations | Thin |
The structural shift to notice: services (advertising, third-party seller services, subscriptions, and AWS) now make up close to 60% of Amazon’s revenue mix, up from roughly 50% in 2021, according to Marketplace Pulse. Amazon has spent two decades quietly converting itself from a retailer that runs services into a services company that happens to run a giant store.
Revenue breakdown by segment
| Segment | FY2025 revenue | Growth (YoY) |
|---|---|---|
| North America | $426.3B | +10% |
| International | $161.9B | +13% |
| AWS | $128.7B | +20% |
| Total | $716.9B | +12% |
Within those segments, two product lines are growing far faster than the retail base. Advertising reached roughly $68.5 billion for the full year, up about 22%, per Business of Apps. AWS exited the year at a quarterly run rate near $142 billion, with fourth-quarter growth of 24%, its fastest in 13 quarters, according to Amazon’s Q4 release.
The real engine: where the profit actually comes from
This is the single most misunderstood thing about Amazon, and the chart most competitor articles bury or omit. Amazon’s $80 billion in operating income is not spread evenly. It is heavily concentrated in cloud.
| Segment | FY2025 operating income | Share of total |
|---|---|---|
| AWS | $45.6B | ~57% |
| North America | $29.6B | ~37% |
| International | ~$4.8B | ~6% |
| Total | $80.0B | 100% |
Read that again. AWS is about 18% of revenue but produces well over half of the profit. The e-commerce operation, the thing Amazon is famous for, runs at razor-thin margins by design. Jeff Bezos made that choice two decades ago: keep retail prices low, accept the slim margins, use the scale to build adjacent businesses (AWS, ads, Prime, seller services) that earn the real returns. The store is the customer-acquisition layer. Everything else is the monetization layer.
If you spun AWS out tomorrow, the remaining Amazon would be a low-margin logistics and retail giant. That is not a criticism. It is the entire point of the design.
A brief history of Amazon
Amazon launched in July 1995 as an online bookstore run out of Jeff Bezos’s garage in Bellevue, Washington. Bezos, a former Wall Street hedge fund executive, had spotted a statistic that web usage was growing at roughly 2,300% a year, and he wanted a business that fit that curve. He chose books for a practical reason: more distinct titles existed than in any other product category, which made the “infinite shelf” of the internet an obvious advantage.
The original name was going to be Cadabra (short for abracadabra), but his lawyer pointed out it sounded too much like “cadaver” over the phone. Bezos landed on Amazon, after the largest river in the world, signaling the scale he was aiming for.
| Era | What defined it |
|---|---|
| 1994 to 2005 | Books, then everything. Survived the dot-com crash by cutting uncontrolled bets and shifting toward a platform model. |
| 2005 to 2015 | The experiments that became giants: Prime (2005), AWS (2006), and advertising. Some flops too, like the Fire Phone. |
| 2015 to 2020 | Proof of scale. AWS numbers stunned the market and forced Microsoft and Google to chase cloud seriously. |
| 2020 forward | Pandemic surge, then a deliberate pivot to AI infrastructure and satellite internet as the next frontier. |
The throughline is consistent: customer obsession first, willingness to lose money for years on bets that might compound, and a habit of turning internal infrastructure into external products. AWS itself started as an attempt to untangle Amazon’s own messy systems before becoming the most profitable part of the company.
Amazon mission statement
Amazon is guided by four principles: customer obsession over competitor focus, a passion for invention, a commitment to operational excellence, and long-term thinking. The company states its aim to be Earth’s most customer-centric company, Earth’s best employer, and Earth’s safest place to work. For a deeper read on how those principles shape strategy and external pressures, see our Amazon PESTLE analysis.
Amazon Business Model Canvas
| Building block | Amazon’s version |
|---|---|
| Customer segments | Buyers, third-party sellers, AWS developers and enterprises, content creators |
| Value propositions | Low prices, fast delivery, vast selection, and above all convenience |
| Channels | Amazon.com, the mobile app, Alexa devices, physical stores, and the affiliate program |
| Customer relationships | Self-service plus reviews, personalized recommendations, and responsive support |
| Revenue streams | Retail sales, seller fees, AWS usage, advertising, Prime subscriptions, licensing |
| Key resources | Technology infrastructure, fulfillment network, data, brand, and talent |
| Key activities | Platform development, logistics, cloud operations, content production, and marketing |
| Key partners | Third-party sellers, AWS partners, affiliates, content creators, delivery partners |
| Cost structure | Cost of sales, fulfillment, technology and infrastructure, marketing, and content |
The two-sided network effect sits at the center of it. More sellers means more selection at competitive prices, which pulls in more buyers, which makes the platform more attractive to even more sellers. Fulfillment by Amazon and Prime tie the loop together by making third-party purchases feel as fast and reliable as Amazon’s own. For a fuller operational view, our Amazon value chain analysis breaks down each link.
The flywheel, and why it still spins
Amazon’s growth has never come from a single product. It comes from the way the pieces reinforce one another. Lower prices and wider selection drive traffic. Traffic attracts sellers, who widen selection further. Scale lowers Amazon’s cost structure, which funds even lower prices. And the by-products of running all that (cloud infrastructure, shopper data, shipping volume) became AWS, the advertising business, and the logistics arm Amazon now rents to other companies.
In 2025, more than 60% of paid units sold on Amazon came from third-party sellers, and over 1.3 million sellers adopted Amazon’s generative AI listing tools, per Amazon’s own reporting. The flywheel is now AI-accelerated, with the same logic running faster.
Amazon’s newest bets: AI infrastructure and Amazon Leo
This is where the 2026 Amazon diverges sharply from the company most articles still describe. Two bets dominate the roadmap.
The AI infrastructure bet. Amazon has guided total 2026 capital spending toward roughly $200 billion, almost entirely for AI data centers, custom chips, and logistics automation, after spending about $125 billion in 2025. Its custom silicon line (the Graviton and Trainium chips) crossed a $10 billion annualized run rate and is growing at triple-digit percentages. The AWS order backlog reached $244 billion, up about 40% year over year, signaling enterprise and government demand that is not slowing. CEO Andy Jassy has framed AWS as an AI infrastructure company with a cloud business underneath, rather than the reverse.
The satellite bet: Amazon Leo. In November 2025, Amazon rebranded Project Kuiper as Amazon Leo, a low-earth-orbit broadband network built to compete with SpaceX’s Starlink. Here is the current state of play.
| Amazon Leo (as of mid-2026) | Detail |
|---|---|
| Satellites in orbit | Roughly 217 to 241 |
| FCC deployment requirement | 1,618 satellites by July 30, 2026 (extension requested) |
| Full first-generation constellation | 3,236 satellites by 2029 |
| Gen2 approval | Cleared for expansion toward a planned 7,727 total |
| Commercial launch target | Mid-2026, after enterprise beta on April 8, 2026 |
| Capital committed | Over $10B, with first-gen estimates of $16.5B to $20B |
| Notable move | ~$9B agreement to acquire Globalstar, announced April 2026 |
For context on the competitive gap: Starlink generated about $10.6 billion in 2025 revenue with more than 10 million subscribers across a constellation of roughly 8,000 satellites, per reporting on Amazon Leo’s commercial timeline. Amazon is years behind on hardware in orbit, but it has something Starlink does not: native integration with AWS, which lets data move from a remote terminal straight into Amazon’s cloud and AI stack. That is the strategic logic. Leo is less a standalone internet company and more an extension of AWS to any point on the planet.
Amazon competitors
Amazon competes on multiple fronts at once, which is part of why no single rival can box it in.
| Competitor | Competes with Amazon in |
|---|---|
| Walmart | Retail and grocery, with a fast-growing US e-commerce arm |
| Alibaba / JD | Global and Chinese e-commerce, B2B and B2C marketplaces |
| Microsoft Azure | Cloud infrastructure, the main AWS rival |
| Google Cloud | Cloud infrastructure and AI services |
| Temu / Shein | Low-price, direct-from-factory goods squeezing Amazon’s budget SKUs |
| Netflix / Disney+ | Streaming, against Prime Video |
| SpaceX Starlink | Satellite internet, against Amazon Leo |
The sharpest near-term pressure comes from two directions. Walmart’s omnichannel model uses its 10,000-plus stores as same-day fulfillment hubs, something Amazon cannot replicate without a physical footprint. For a direct head-to-head, see our Walmart vs Amazon comparison, our Walmart business model breakdown, and the Alibaba business model on the international side. We also keep a fuller list in our guide to Amazon’s competitors.
Amazon SWOT analysis (condensed)
| Strengths | Weaknesses |
|---|---|
| AWS profit engine and brand strength | Razor-thin retail margins |
| Logistics network and Prime loyalty | Labor and workplace scrutiny |
| Data and AI advantage across the stack | Free cash flow squeezed by heavy capex |
| Advertising business at high margins | Heavy reliance on third-party sellers |
| Opportunities | Threats |
|---|---|
| AI services monetization through AWS | FTC antitrust trial beginning October 2026 |
| Amazon Leo and global connectivity | Cloud competition from Azure and Google |
| Healthcare, grocery, and emerging markets | Low-cost Chinese marketplaces on price |
| Custom silicon reducing dependence on NVIDIA | Regulatory pressure across multiple regions |
For the full breakdown with the latest quarterly figures, our dedicated Amazon SWOT analysis goes deeper on each point.
Risks on the horizon
Three risks deserve more attention than the usual “competition is fierce” line.
First, the capital intensity is real. Free cash flow collapsing to $11.2 billion while the company spends toward $200 billion in 2026 is a genuine bet. If AI demand softens or AWS growth stalls, that spending becomes very hard to justify, and the balance sheet feels it.
Second, the FTC antitrust trial is scheduled for October 2026, joined by 17 state attorneys general. An adverse outcome could force changes to how Amazon ties its marketplace, fulfillment, and advertising businesses together, which is precisely where the flywheel earns its margin.
Third, seller relations are fraying at the edges. In April 2026, more than 700 third-party sellers representing roughly $14 billion in revenue mounted an advertising boycott over payout delays and fees. The marketplace flywheel depends on seller participation, and Amazon’s pricing power over those sellers cuts both ways.
Bottom line
Amazon in 2026 is best understood as a cash-flow machine pointed entirely at the future. The retail business it is famous for barely turns a profit on purpose. The real earnings come from AWS, advertising, and seller services, and almost every dollar of that profit is being recycled into AI infrastructure and satellite internet rather than returned to shareholders.
That is either the most disciplined long-term bet in corporate history or an expensive overreach, depending on how the next two years play out. What is not in question is the design. Amazon built a low-margin engine to generate scale, then attached high-margin businesses that the scale made possible, and it keeps repeating the pattern. The store was never the point. It was always the on-ramp.
Frequently asked questions
What is Amazon’s business model in simple terms? Amazon sells products at low margins to attract a huge customer base, then earns most of its profit from higher-margin businesses built on that scale: cloud computing (AWS), advertising, Prime subscriptions, and fees charged to third-party sellers.
How does Amazon actually make money? Through six engines: first-party retail, third-party seller services, AWS, advertising, Prime subscriptions, and physical stores. In 2025, AWS alone produced about 57% of operating income despite being roughly 18% of revenue.
How much revenue did Amazon make in 2025? Amazon reported $716.9 billion in net sales and $77.7 billion in net income for full-year 2025.
Why is AWS so important to Amazon? AWS is the company’s profit core. It generated $45.6 billion of operating income in 2025, the majority of Amazon’s total, and funds the retail and logistics operations that run near breakeven.
What is Amazon Leo? Amazon Leo, formerly Project Kuiper, is Amazon’s low-earth-orbit satellite internet network. It entered enterprise beta in April 2026 with commercial launch targeted for mid-2026, and it is designed to compete with Starlink while integrating directly with AWS.


nice analysis ,thanks
bestfitnesstores fitness store best fitness stores fitness store bestfitnesstores fitnessstore fitness store fitnessstore store
CatFee 拥有来自大厂的技术专家团队,以及在区块链领域深耕多年的工程师,确保了平台技术的高效与稳定。
Great read. There were a few points here I hadn’t considered before, and it gave me a different perspective on the topic. Appreciate you sharing this.
Really helpful article. I especially liked how clearly the topic was explained without overcomplicating it. Thanks for putting this together.
Today, while I was at work, my sister stole my iPad and tested to see
if it can survive a 30 foot drop, just so she can be a youtube sensation. My apple ipad is now broken and
she has 83 views. I know this is completely
off topic but I had to share it with someone!
my blog Sallie
Your point of view caught my eye and was very interesting. Thanks. I have a question for you.
Check it out—just ask AI about it.
1
1
1
1
1
1
1
1
1″(‘.)a,bcd
1
1
1
1
1
1
1
1
1)
1′
1′)
1
1
1
1
Traveling around Southeast Asia is not always about seeing as many places as possible. Staying longer, choosing a comfortable base, and learning how local life works can make the experience much more enjoyable. For practical ideas on destinations, remote work, visas, and slow travel, SlowTropics offers useful guides for travelers and digital nomads exploring the region.
This was beautiful Admin. Thank you for your reflections.
I appreciate you sharing this blog post. Thanks Again. Cool.
çok başarılı ve kaliteli bir makale olmuş güzellik sırlarım olarak teşekkür ederiz.
naturally like your web site however you need to take a look at the spelling on several of your posts. A number of them are rife with spelling problems and I find it very bothersome to tell the truth on the other hand I will surely come again again.
This post reminded me why I love 🔥 being part of this wonderful community
Hi there to all, for the reason that I am genuinely keen of reading this website’s post to be updated on a regular basis. It carries pleasant stuff.
Great insights! It’s fascinating to see how Amazon’s business model continues to evolve. The emphasis on diversification and innovation really sets them apart from their competitors. I’m particularly intrigued by their expansion into AI and how that might shape future revenue streams. Looking forward to seeing how these strategies play out!
Great insights on Amazon’s evolving business model! It’s fascinating to see how they diversify their revenue streams, especially with their focus on cloud services and subscription models. I’m curious to see how they will adapt to new market trends in the coming years. Thanks for the detailed analysis!