Target SWOT Analysis at a Glance
What it is: A SWOT analysis of Target Corporation (NYSE: TGT) examines the internal strengths and weaknesses and the external opportunities and threats shaping the seventh-largest retailer in the United States.
The 2026 takeaway: For the first time in over a year, the Target story has a plot twist. Revenue fell for a third straight year in fiscal 2025, to roughly $104.8 billion, with comparable sales down 2.6%. Then in the first quarter of fiscal 2026 the company snapped a five-quarter losing streak: comparable sales rose 5.6%, net sales grew 6.7%, and management raised full-year guidance. The core advantages (a beloved brand, an owned-brand portfolio, a same-day fulfillment network, and a fast-growing ad business) never broke. The question now is whether one good quarter is the bottom or just a bounce.
SWOT Quadrant One-Line Summary Strengths Distinctive brand, ~50 owned brands, Target Circle 360 loyalty, same-day fulfillment, Roundel ad engine Weaknesses Heavy discretionary reliance, weak store execution, eroded price perception, thin grocery mix Opportunities Owned-brand expansion, retail media (Roundel), grocery share, the $6B store-investment plan Threats Walmart and Costco momentum, tariffs, reputational crossfire, e-commerce margin pressure Figures reflect Target’s fiscal 2025 results (year ended January 31, 2026) and first-quarter fiscal 2026 results (quarter ended May 2, 2026).
Quick Answer: Is Target in Trouble in 2026?
Less than it was six months ago. For most of 2025 the honest answer was “yes, but the problems are fixable.” Sales fell for several quarters straight, foot traffic softened, and the company changed CEOs. Then the first quarter of fiscal 2026 landed well above expectations and broke the losing streak. Comparable sales grew 5.6%, the first positive number in five quarters, and Target raised its full-year sales outlook.
So the framing has shifted. This is no longer a story about whether Target can stop the bleeding. It is a story about whether the early recovery holds against a brutal Walmart, a relentless Costco, and a tougher set of year-over-year comparisons in the back half of 2026. Target is still profitable, still owns one of the most recognized brands in U.S. retail, and is funding a multi-year fix. The slump looks like it has a floor. Whether it has a future depends on execution from here.
This analysis breaks down exactly where Target stands, what changed across 2025 and 2026, and what the SWOT framework reveals about its next move.
Target Corporation: Company Snapshot (2026)
Before the SWOT, here is the current picture. A SWOT analysis is only as useful as the facts underneath it, so these numbers anchor everything that follows.
| Metric | Figure | Period / Source |
|---|---|---|
| Founded | 1902 (corporation); 1962 (first Target store) | Company history |
| Headquarters | Minneapolis, Minnesota | Company filings |
| CEO | Michael Fiddelke (effective February 1, 2026) | Company announcement |
| Executive Chairman | Brian Cornell (CEO 2014 to 2026) | Company announcement |
| Total revenue | ~$104.8 billion | Fiscal year 2025 |
| Comparable sales | Down ~2.6% | Fiscal year 2025 |
| Q1 net sales | $25.4 billion (up 6.7%) | Q1 fiscal 2026 |
| Q1 comparable sales | Up 5.6% | Q1 fiscal 2026 |
| Q1 gross margin | 29.0% (up from 28.2%) | Q1 fiscal 2026 |
| U.S. stores | ~1,995 | 2026 |
| Employees | ~415,000 | 2025 |
| Full-year 2026 sales guidance | Growth of ~4% (raised from ~2%) | Q1 fiscal 2026 |
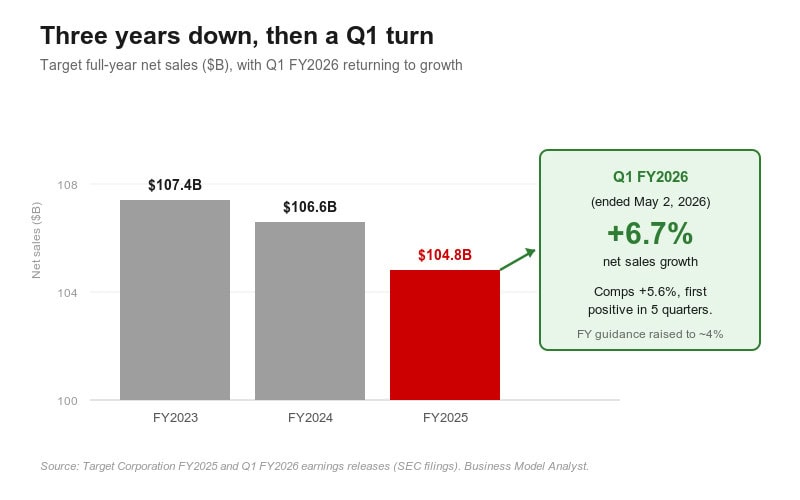
Target’s revenue slid from about $107.4 billion in fiscal 2023 to $106.6 billion in fiscal 2024 to $104.8 billion in fiscal 2025. That three-year drift down from the pandemic peak is the backdrop for almost every weakness and threat below, and the Q1 fiscal 2026 rebound is the reason the analysis no longer reads like an obituary. Full results are published in Target’s investor relations filings and its annual 10-K report filed with the SEC.
What Changed for Target Between 2024 and 2026
Most SWOT articles on Target read like they were written in 2022. They were not wrong then. They are simply stale now. Here is what genuinely moved, and why each item matters for the analysis.
| Event | When | Why It Matters for the SWOT |
|---|---|---|
| Target scaled back DEI programs | January 2025 | Triggered a sustained consumer boycott; reputational threat |
| Consumer boycott launched by faith leaders | February 2025 | Over 150,000 pledged participants; foot traffic fell for 10+ consecutive weeks |
| Q1 fiscal 2025 sales miss | May 2025 | Comparable sales down ~3.8%; company cut its full-year outlook |
| CEO succession announced | August 2025 | COO Michael Fiddelke named to replace Brian Cornell |
| $6 billion turnaround plan unveiled | Late 2025 | Investment in stores, staffing, and technology; a direct response to weaknesses |
| Fiddelke becomes CEO | February 1, 2026 | First leadership change in over a decade |
| National boycott formally ends | March 2026 | Reputational pressure eases, but activists remain split on outcomes |
| Q1 fiscal 2026 beats and guidance raised | May 2026 | First positive comp in five quarters; full-year sales outlook lifted to ~4% |
This timeline is the single biggest reason a 2026 SWOT of Target looks different from any version published before. The strengths are familiar. The weaknesses and threats are not, and now neither is the trajectory. Reporting from the Associated Press and outlets such as Reuters tracked each of these developments through 2025 and 2026.
The Q1 fiscal 2026 print deserves its own look, because it is the data point that reframes the whole analysis.
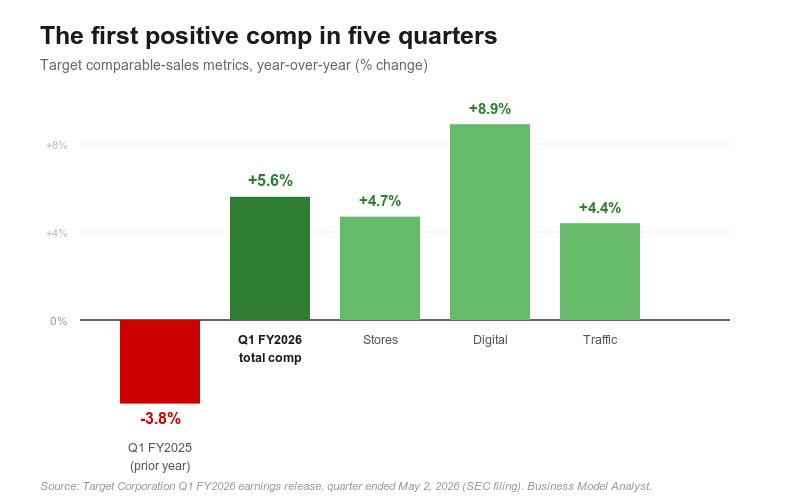
A 5.6% comparable-sales gain after four straight negative quarters is a real inflection, not a rounding error. Stores grew 4.7%, digital grew 8.9%, traffic was up 4.4%, and same-day delivery through Target Circle 360 jumped more than 27%. The one caveat worth keeping in view: Target was lapping a weak quarter, so part of that swing is an easy comparison. The tougher test comes later in 2026, when the company laps stronger prior-year periods.
Target SWOT Analysis: The Full Matrix

For readers who want the structure at a glance before the detail:
| Strengths | Weaknesses |
|---|---|
| Strong, differentiated brand identity (“cheap chic”) | Heavy reliance on the U.S. market |
| Roughly 50 owned and exclusive brands | Overexposure to discretionary, non-essential categories |
| Same-day fulfillment network (Drive Up, Order Pickup, Shipt) | Weak in-store execution: pricing, stocking, service |
| Target Circle 360 loyalty and membership revenue | Eroding value perception versus Walmart |
| Roundel retail media business | Smaller international and grocery footprint than rivals |
| Opportunities | Threats |
|---|---|
| Expansion of owned-brand portfolio | Intensifying competition from Walmart and Costco |
| Growth of retail media (high-margin ad revenue) | Tariffs and import-cost volatility |
| Grocery and essentials share gains | Reputational and political crossfire over social issues |
| The $6 billion store-investment plan | E-commerce fulfillment costs compressing margins |
| Target+ marketplace and membership growth | Soft discretionary spending and cautious consumers |
The sections below explain each quadrant with current evidence.
Strengths: What Target Still Does Better Than Most
Target’s strengths are real and durable. They are also the reason the slump proved fixable rather than fatal, and the reason the Q1 rebound was even possible.
A genuinely differentiated brand
Target built its identity on “cheap chic,” the idea that a discount store could feel like a design destination. Decades of collaborations with designers and the cultivation of the affectionate “Tar-zhay” nickname gave the company something most discounters never achieve: emotional brand equity. Walmart competes on price. Costco competes on bulk value. Target competes on the experience of shopping, and that positioning is hard to copy. The same dynamic shows up clearly in the Walmart SWOT analysis, where scale and price leadership, not experience, are the headline strengths.
A deep portfolio of owned brands
Target operates roughly 50 owned and exclusive brands spanning apparel, home, groceries, and essentials, including names like Good & Gather, Cat & Jack, Threshold, and All in Motion. Owned brands matter for two reasons. They carry higher margins than national brands, and they cannot be bought anywhere else, which protects against pure price comparison. Several of these brands individually generate over a billion dollars in annual sales. This private-label strength is central to the Target Corporation business model, and it helped push gross margin up to 29.0% in Q1 fiscal 2026 from 28.2% a year earlier.
A built-out same-day fulfillment network
Target’s same-day services (Drive Up, Order Pickup, and delivery through Shipt) turn its store base into a fulfillment advantage. Because most of Target’s online orders are filled from nearby stores rather than distant warehouses, the model is structurally cheaper per order than warehouse-only e-commerce. The proof showed up in Q1 fiscal 2026: digital comparable sales grew 8.9%, led by more than 27% growth in same-day delivery powered by Target Circle 360. The channel is not just working, it is leading the recovery.
Target Circle 360 loyalty and the Roundel ad business
Target Circle, the company’s loyalty program, gives Target a large base of identified shoppers and a stream of first-party data. That data feeds Roundel, Target’s retail media network, which sells advertising to brands that want to reach Target shoppers. Retail media is one of the highest-margin businesses in modern retail. In Q1 fiscal 2026, non-merchandise revenue (Roundel ads, Target Circle 360 memberships, and the Target+ marketplace) grew nearly 25%, and management cited those high-margin streams as a direct driver of margin improvement. It is the same kind of high-margin advertising engine that powers the Amazon business model.
| Strength | Strategic Value | Durability |
|---|---|---|
| Brand differentiation | Pricing power, customer loyalty | High |
| Owned-brand portfolio | Margin protection, exclusivity | High |
| Same-day fulfillment | Lower e-commerce cost per order | High |
| Target Circle 360 + Roundel | First-party data, high-margin ad revenue | High |
Weaknesses: Where Target Is Exposed
This is where most competing SWOT articles fall short. They list “dependence on the U.S. market” and stop. The more useful weaknesses in 2026 are about execution, not geography.
Overexposure to discretionary spending
Target’s merchandise mix leans heavily toward discretionary categories: apparel, home decor, electronics, and seasonal goods. That mix is a gift in good times and a liability in cautious ones. When household budgets tighten, shoppers cut the discretionary purchases first, then keep buying groceries and essentials. Walmart, with a much larger grocery business, is far more insulated. Target feels every dip in consumer confidence directly, which is exactly why the back-and-forth of 2025 hit it so hard.
Weak in-store execution
This is the weakness Target’s own leadership has admitted. Industry analysts have pointed out that the sales decline set in before the DEI controversy and was driven by poor execution: inconsistent pricing, out-of-stock shelves, and uneven customer service. As Neil Saunders of GlobalData Retail has argued, the boycott hurt, but the deeper problem was operational. The $6 billion turnaround plan exists specifically because this weakness is internal and within Target’s control to fix.
Eroding value perception
Years of price increases and a premium-leaning assortment slowly weakened Target’s reputation as an affordable store. When inflation squeezed households, “Tar-zhay” charm did not pay the bill, and shoppers traded down to Walmart. Target’s response, slashing prices on thousands of items and rolling out a wave of products priced under $20, is a direct admission that value perception slipped. Rebuilding it is a multi-year project, not a one-quarter fix.
Heavy U.S. concentration
Target operates almost entirely in the United States. It has no meaningful international business after the failed and costly Target Canada exit in 2015. This concentration means Target has no geographic cushion: a soft U.S. consumer is a soft Target. Rivals like Walmart and Costco spread risk across multiple countries, which is one reason their results held up better through the same period. For the full competitive picture, see the top Target competitors breakdown.
| Weakness | Root Cause | Within Target’s Control? |
|---|---|---|
| Discretionary overexposure | Merchandise mix skewed to non-essentials | Partly (mix can shift slowly) |
| Weak store execution | Operational lapses in pricing and stocking | Yes |
| Eroding value perception | Years of price creep | Yes |
| U.S. concentration | No international footprint | Slow / structural |
Opportunities: Where Target Can Grow
Target’s opportunities are not exotic. They are mostly about executing well on assets it already owns, and Q1 fiscal 2026 showed what that execution can produce.
Lean harder into owned brands
Every percentage point of sales shifted from national brands to Target’s owned brands improves margin and deepens customer lock-in. Expanding successful brands into new categories, and launching new ones, is a low-risk growth lever Target has executed well before. The margin gain in Q1 fiscal 2026 is a preview of what scaling private label can do for profit.
Grow Roundel and retail media
Retail media is expanding fast across the industry because it is enormously profitable. Roundel is already established, and the nearly 25% growth in non-merchandise revenue in Q1 fiscal 2026 shows the engine is accelerating. Scaling it further lets Target grow profit even in a flat-sales environment, which is a useful hedge if merchandise momentum cools.
Win more grocery and essentials trips
Target’s discretionary tilt is a weakness, but the fix is also an opportunity. By strengthening grocery and everyday essentials, Target can convert occasional shoppers into weekly ones and reduce its exposure to discretionary swings. More frequent trips also mean more chances to sell higher-margin discretionary goods on the same visit.
Execute the $6 billion turnaround plan
The turnaround plan itself is the headline opportunity. The investment targets the precise weaknesses identified above: store conditions, staffing, and technology. The company opened seven new stores and had more than 100 remodels in progress during Q1 fiscal 2026. If Fiddelke’s team keeps executing, the plan converts Target’s biggest weakness (execution) into renewed strength. If it stalls, the slump could resume. This is still the single most important variable in Target’s 2026 and 2027 story.
| Opportunity | Why It Is Realistic | Primary Benefit |
|---|---|---|
| Owned-brand expansion | Proven capability, existing infrastructure | Higher margin, exclusivity |
| Retail media (Roundel) growth | Industry-wide tailwind, asset already built | High-margin profit growth |
| Grocery and essentials share | Drives trip frequency | Insulation from discretionary swings |
| $6B turnaround execution | Funded and underway, early results positive | Fixes the core weakness |
Threats: What Could Hold Target Back
A stronger, faster Walmart
Walmart is the central competitive threat, and the threat is structural rather than seasonal. While Target’s comp turned positive in Q1, Walmart kept compounding from a far larger base: roughly 4.6% U.S. comparable-sales growth in its most recent quarter, e-commerce up about 24%, and an advertising business near $6.4 billion a year growing 37%. Costco adds pressure from the value end, posting comparable-sales growth of 7.4% in its latest quarter. Target sits squeezed between a scale leader and a value leader.
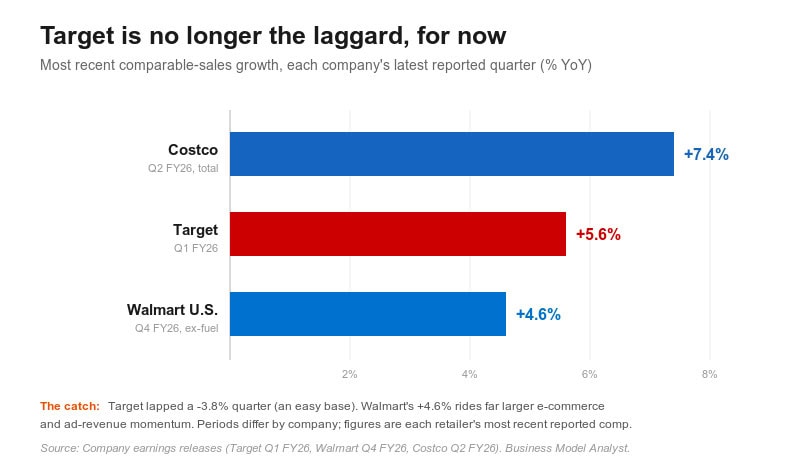
Here is the nuance most write-ups miss. In the single most recent quarter, Target’s 5.6% comp actually ran ahead of Walmart U.S. at 4.6%. That sounds like Target winning. It is not, at least not yet. Target was lapping a 3.8% decline, an easy comparison, while Walmart was growing against tougher numbers and out-investing Target in e-commerce and advertising. A good quarter against a weak prior year is encouraging. Sustained share gains against Walmart’s machine would be something else entirely, and Target has not proven that. The contrast gets clearer when this analysis is read alongside the Costco SWOT analysis.
Tariffs and import-cost volatility
Target sources a large share of its merchandise, particularly owned-brand goods, from overseas. Tariff increases and trade-policy uncertainty raise input costs and force a hard choice: absorb the cost and lose margin, or pass it to shoppers and lose price competitiveness. Target has begun diversifying sourcing away from China toward Central America and the U.S., but supply-chain shifts take years. Notably, Target’s full-year guidance explicitly excludes the impact of any tariff refunds, a sign of how unsettled the trade picture remains. The Office of the U.S. Trade Representative publishes current tariff actions that bear directly on retail import costs.
Reputational and political crossfire
The 2025 DEI episode is the clearest example of a structural threat. Target’s brand sits with a socially engaged customer base, which means decisions on social issues carry commercial consequences in both directions. The DEI rollback drew a sustained boycott; reversing course risks backlash from the other side. The national boycott formally ended in March 2026, but the underlying exposure did not. For a brand built on cultural relevance, this is an ongoing tightrope, not a one-time event.
E-commerce margin pressure and cautious consumers
Online sales grow, but fulfillment, returns, and delivery erode the profit on each order. Combine that with cautious consumers who delay discretionary purchases, and Target faces a slow-growth, thin-margin environment that rewards operational discipline above all. The University of Michigan Index of Consumer Sentiment is a useful gauge of the discretionary-spending mood that drives Target’s results.
| Threat | Severity | Time Horizon |
|---|---|---|
| Walmart and Costco competition | High | Ongoing |
| Tariffs and import costs | Medium-High | Near-term |
| Reputational / political exposure | Medium-High | Ongoing |
| E-commerce margin pressure | Medium | Ongoing |
| Soft discretionary spending | Medium | Cyclical |
What the SWOT Reveals: A Strategic Read
Put the four quadrants together and a clear pattern emerges.
Target’s strengths are intact and actively working. The brand, the owned brands, the fulfillment network, and the loyalty and ad businesses all powered the Q1 fiscal 2026 rebound. None of them broke during the slump, and now they are visibly contributing again.
Target’s weaknesses are mostly self-inflicted and fixable. Weak store execution and eroded value perception are operational problems, not structural ones. That is good news, because operational problems respond to investment and management focus, and the early numbers suggest the focus is landing.
Target’s biggest opportunity and biggest uncertainty are still the same thing: the $6 billion turnaround plan. The first quarter delivered encouraging proof, but one quarter against an easy comparison is not a turnaround. Whether 2026 marks the bottom or merely a pause depends on whether the team sustains execution against tougher comparisons later in the year.
Target’s threats are real but familiar. Competition, tariffs, and reputational exposure are pressures every large retailer manages. Walmart in particular is not slowing down, and Target’s recent comp advantage is mostly a math artifact of an easy base. These pressures constrain Target. They do not define it.
The summary judgment: Target is a strong company that may have found the bottom of a fixable slump. The framework points to a recovery that depends far more on internal execution than on external rescue, and the first real evidence that the execution is working has finally arrived.
Frequently Asked Questions
Who is the CEO of Target in 2026? Michael Fiddelke became CEO of Target on February 1, 2026, succeeding Brian Cornell, who led the company from 2014 and moved into the executive chairman role.
Is Target recovering in 2026? The early signs are positive. In the first quarter of fiscal 2026 (ended May 2, 2026), Target posted comparable-sales growth of 5.6%, its first positive comp in five quarters, along with 6.7% net sales growth. The company also raised its full-year sales outlook. The recovery is real but early, and it benefited from an easy prior-year comparison.
Why did Target’s sales decline? Several factors combined: cautious consumer spending on discretionary goods, weak in-store execution on pricing and stocking, a consumer boycott tied to the rollback of DEI programs, and intensifying competition from Walmart and Costco. Comparable sales fell about 2.6% in fiscal 2025 before turning positive in Q1 fiscal 2026.
What is Target’s biggest strength? Its differentiated brand. Target’s “cheap chic” identity and roughly 50 owned brands give it pricing power and customer loyalty that pure discounters cannot easily replicate, and they helped lift gross margin in the most recent quarter.
What is Target’s biggest weakness? Weak in-store execution combined with overexposure to discretionary categories. Both leave Target vulnerable when consumers tighten budgets, and both are central targets of its $6 billion turnaround plan.
Who are Target’s main competitors? Walmart and Costco are the primary competitors, with Amazon a major force in e-commerce and pressure also coming from off-price and dollar-store chains.
The Business Model Analyst Take
A 2026 SWOT analysis of Target tells a more interesting story than the evergreen versions that still circulate online, and the story changed in May. For most of 2025, Target looked like a strong brand stuck in a self-inflicted slump. Then Q1 fiscal 2026 broke a five-quarter losing streak, gross margin expanded, the ad business accelerated, and management raised guidance. The strengths that never broke finally showed up in the numbers.
We would caution against declaring victory. Target’s standout comp came against a weak prior-year quarter, the toughest comparisons sit in the back half of 2026, and Walmart keeps widening its lead in e-commerce and advertising regardless of what Target does. One quarter is a data point, not a trend.
But the framework’s verdict has clearly improved. Target’s problems are largely internal, which means they are largely solvable, and for the first time in over a year there is hard evidence the fix is working. The next two quarters, against harder comparisons and under a still-new CEO, will tell us whether this is the bottom or just a breather. For now, the most overused phrase in retail analysis finally fits: Target is a turnaround story with actual signs of a turnaround.