


Costco Wholesale Corporation sells bulk goods at razor-thin markups and makes most of its profit somewhere else entirely: the annual fee members pay just to walk through the door. In fiscal 2025, that model produced $269.9 billion in net sales, $5.3 billion in membership fees, and $8.1 billion in net income. This is a close look at how the Costco business model actually works, why it keeps beating retailers many times its size online, and where the pressure points are heading into 2026.
What is the Costco business model?
Costco runs a membership-only warehouse club. Shoppers pay an annual fee ($65 for Gold Star and Business tiers, $130 for Executive) for the right to buy a tightly limited range of products sold at very low margins. Costco keeps merchandise markups near 11%, far below traditional retail, and relies on high volume, fast inventory turnover, and its Kirkland Signature private label to stay profitable. Membership fees, which cost almost nothing to service, supply roughly two-thirds of net income. In short: Costco sells products close to cost and earns its profit on the membership.
Costco business model at a glance (FY2025)
| Metric | FY2025 | Change vs. FY2024 |
|---|---|---|
| Net sales | $269.9 billion | +8% |
| Total revenue (incl. fees) | $275.2 billion | +8% |
| Membership fee revenue | $5.32 billion | +10% |
| Net income | $8.1 billion | +10% |
| Diluted EPS | $18.21 | +10% |
| Gross margin | 11.12% | +20 bps |
| Total paid members | 81.0 million | +6.3% |
| Total cardholders | 145.2 million | +6.1% |
| Warehouses worldwide | 914 | +24 net new |
| U.S. and Canada renewal rate | 92.3% | Stable |
A brief history of Costco
The story starts with Price Club, the warehouse concept Sol Price pioneered in San Diego in 1976. The first Costco warehouse opened in Seattle in 1983, founded by Jim Sinegal, who had trained under Price, and attorney Jeffrey Brotman. The two companies merged in 1993 to form Price Costco, and the business was renamed Costco Companies a few years later.
Sinegal ran Costco until 2012 and set the cultural rules that still govern it: keep markups capped, pay workers well, and never break the promise of the lowest price. Craig Jelinek succeeded him and led the company for more than a decade. In January 2024, Ron Vachris took over as the third CEO in Costco’s history. Vachris joined in the 1980s as a forklift operator and worked his way up through operations, a detail the company likes to cite because it reinforces the promote-from-within culture that keeps turnover low.
Who owns and runs Costco
Costco is a publicly traded company (Nasdaq: COST). Ownership sits mostly with large institutional investors such as Vanguard, BlackRock, and State Street, the same index-fund giants that hold most of corporate America. Founder Jim Sinegal remains the reference point for how the company thinks, even in retirement. For a fuller breakdown, see our analysis of who owns Costco.
Ron Vachris now leads day-to-day strategy, backed by a management team that has spent most of their careers inside the warehouse. That continuity matters: Costco’s whole model depends on discipline, and discipline is easier to hold when the people running it grew up in the system.
The two engines: how Costco makes money
Most retailers make money one way, by buying products and reselling them at a markup. Costco makes money two ways, and the second one is the reason the first can work.
Engine one: merchandise. The bulk of revenue comes from selling goods across food, sundries, fresh foods, and non-food “hardline” and “softline” categories. But Costco deliberately caps its gross margin around 11%, roughly half of what a typical grocery or general retailer earns. Products are sold close to cost on purpose. That is the bait.
Engine two: membership fees. Nobody shops at Costco without paying an annual fee first. Those fees totaled $5.32 billion in fiscal 2025, and because the cost of servicing a membership is minimal, almost all of it drops to the bottom line. Put the two engines side by side and the model becomes obvious.
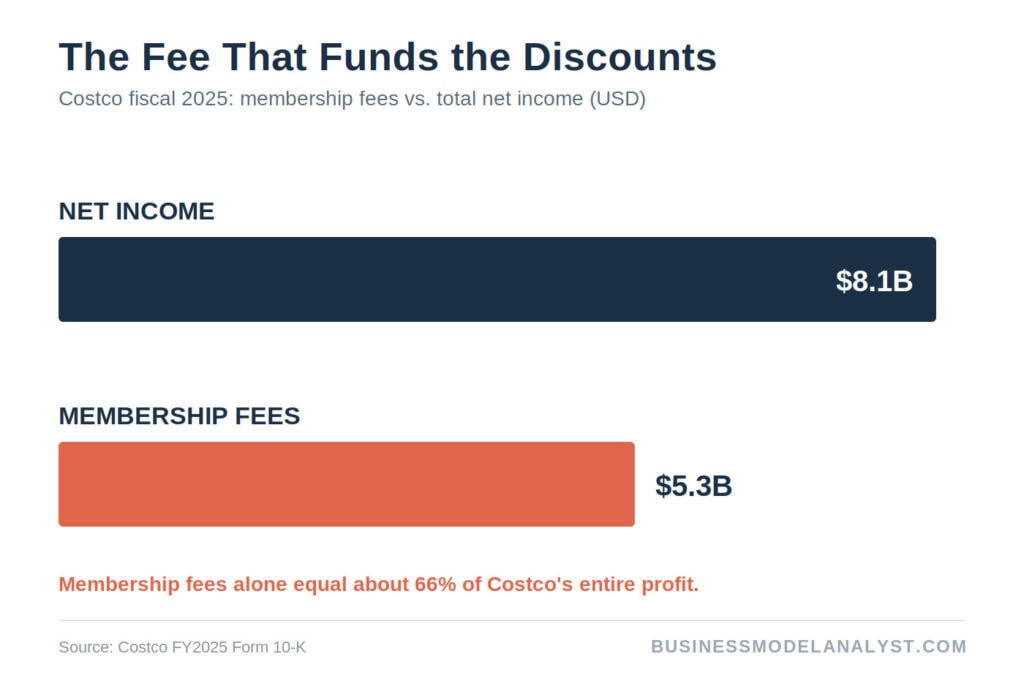
That is the whole trick. Costco can afford to sell a rotisserie chicken at $4.99 and a hot dog combo at $1.50 because it is not trying to profit on the chicken. It is trying to make the membership feel so obviously worth it that you renew every year. In the U.S. and Canada, 92.3% of members do.
Costco’s membership tiers
The fee structure changed on September 1, 2024, the first increase since 2017. Here is the current lineup.
| Tier | Annual fee | Who it is for | Key perk |
|---|---|---|---|
| Gold Star | $65 | Individual households | Standard warehouse and online access |
| Business | $65 | Small businesses and resellers | Same access, plus ability to add affiliates |
| Executive | $130 | High-spend members | 2% cash-back reward, up to $1,250/year |
The Executive tier is where the strategy lives. Executive members pay double the fee, earn 2% back on purchases, and in return they spend far more. They represent roughly 48% of the paid base but drive about 73.6% of Costco’s worldwide sales. Every quarter, Costco pushes Gold Star members to upgrade, most recently by adding executive-only early shopping hours and an Instacart credit.
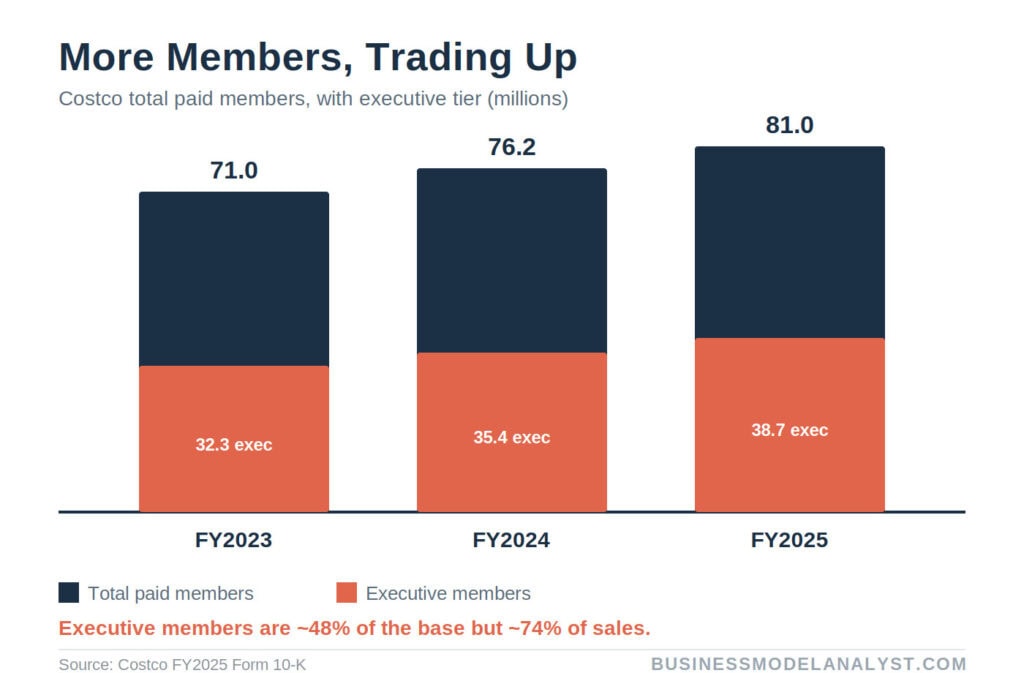
The membership base has grown every year, and the Executive slice is growing faster than the whole. That mix shift is quietly one of the most important numbers at Costco, because it means the average member is spending more and renewing at a higher rate over time.
Costco’s Business Model Canvas
The nine building blocks of the business model canvas map cleanly onto how Costco operates.
| Block | What it looks like at Costco |
|---|---|
| Customer segments | Value-conscious households (Gold Star), small businesses and resellers (Business), and high-spend members (Executive) |
| Value propositions | Lowest possible prices, curated quality, a generous return policy, and 2% rewards for Executive members |
| Channels | 914 warehouses worldwide, Costco.com, the mobile app, and same-day delivery via Instacart, Uber, and DoorDash |
| Customer relationships | Self-service warehouse model reinforced by membership lock-in and the “treasure hunt” of rotating stock |
| Revenue streams | Merchandise sales (near cost) and membership fees (near pure profit) |
| Key resources | The warehouse network, the Kirkland Signature brand, supplier relationships, and a low-turnover workforce |
| Key activities | Bulk purchasing, lean SKU curation, fast inventory turnover, and private-label development |
| Key partners | Manufacturers and suppliers, Kirkland co-packers, Citi and Visa for the co-branded card, and delivery platforms |
| Cost structure | Merchandise costs, warehouse operations, logistics, and above-market employee wages (over $31/hour average) |
Two blocks do the heavy lifting. On the revenue side, the split between near-cost merchandise and near-profit fees is the entire engine. On the cost side, the lean assortment (roughly 4,000 SKUs versus tens of thousands at a supermarket) lets Costco buy deeper on each item, negotiate harder, and turn inventory faster than almost anyone in retail.
Kirkland Signature: the model’s secret weapon
Costco’s private label, Kirkland Signature, turned 30 in 2025 and generated about $90 billion in sales that year, roughly a third of total revenue. To put that in perspective, Kirkland by itself out-sells most of the national brands sitting on Costco’s shelves.
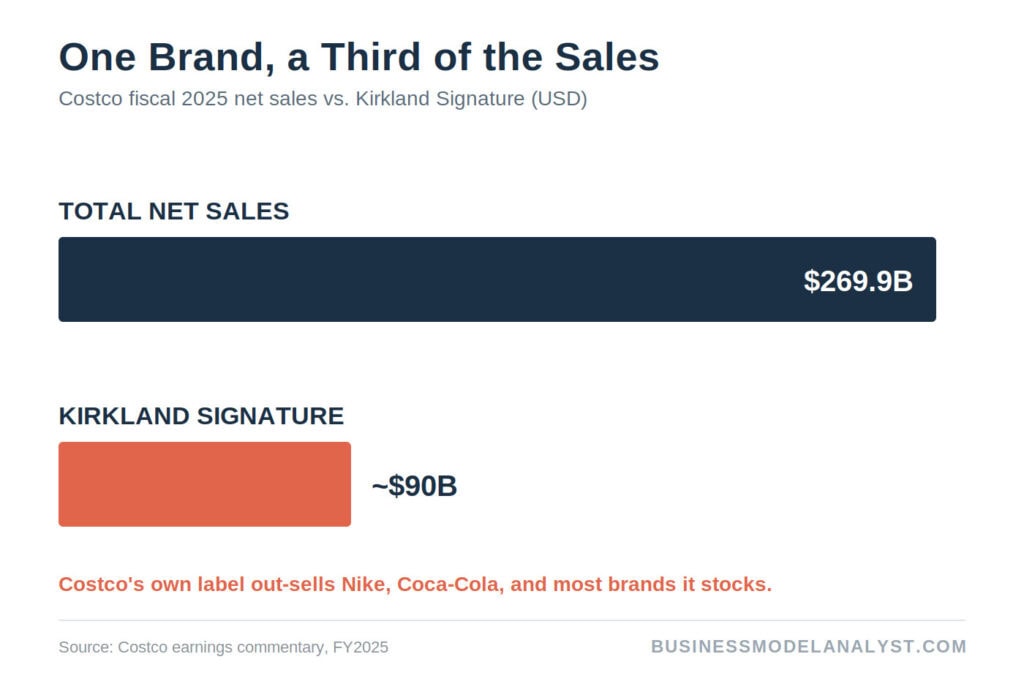
Private label is a margin lever disguised as a value play. When Costco sells Kirkland instead of a national brand, it captures the manufacturer’s profit, controls the supply chain, and often prices the item well below the branded equivalent. Members read that as a better deal; Costco reads it as a better margin and more control during tariff swings. It is the rare feature that makes customers and the finance team happy at the same time.
Costco’s competitors
Costco competes on price and scale against both warehouse clubs and general retail giants.
| Competitor | Model | Annual revenue (latest FY, approx.) |
|---|---|---|
| Walmart | Everyday-low-price mass retail | ~$681 billion |
| Amazon | E-commerce and cloud | ~$638 billion |
| Costco | Membership warehouse club | $269.9 billion |
| Target | General merchandise retail | ~$107 billion |
| Sam’s Club (Walmart) | Membership warehouse club | ~$90 billion |
| BJ’s Wholesale | Membership warehouse club (East Coast) | ~$20 billion |
The direct rival is Sam’s Club, which runs the same fee-plus-warehouse playbook under Walmart’s ownership. The bigger long-term threat is e-commerce. Amazon and Walmart are pouring money into bulk-shipping and fast delivery, and Costco’s digital sales, though growing over 20% year over year, still trail both. Costco’s answer is not to out-Amazon Amazon; it is to keep the in-warehouse experience and the membership value strong enough that members do not defect.
Costco’s SWOT analysis in brief
Strengths: a 92.3% renewal rate, the $90 billion Kirkland brand, industry-leading wages that keep turnover low, and a membership model that funds low prices. Weaknesses: thin ~11% margins, a deliberately limited SKU range, heavy reliance on membership fees for profit, and an e-commerce operation behind its biggest rivals. Opportunities: international expansion (especially Asia), continued Executive upgrades, and private-label growth toward an estimated 35% to 40% of sales by 2030. Threats: tariff uncertainty, aggressive digital competition, and a stock valuation that leaves little room for a stumble. For the full teardown, see our Costco SWOT analysis.
Frequently asked questions
How does Costco make most of its money? Not from selling products. Costco caps merchandise margins near 11% and earns roughly two-thirds of its net income from membership fees, which totaled $5.32 billion in fiscal 2025 and cost almost nothing to service.
How much is a Costco membership in 2025? Gold Star and Business memberships cost $65 a year, and the Executive membership costs $130. Costco raised these fees on September 1, 2024, the first increase since 2017.
Why is Costco able to sell products so cheaply? It carries only about 4,000 SKUs, buys each in enormous volume, sells close to cost, turns inventory quickly, and leans on its Kirkland Signature private label. The membership fee, not the markup, is where the profit comes from.
How many members does Costco have? As of the end of fiscal 2025, Costco had 81.0 million paid memberships and 145.2 million total cardholders. Executive members make up about 48% of the base but drive roughly 74% of sales.
Who is the CEO of Costco? Ron Vachris has been CEO since January 2024. He is the company’s third CEO and started his career at Costco as a forklift operator in the 1980s.
What is Kirkland Signature’s share of Costco sales? Kirkland Signature generated about $90 billion in 2025, roughly a third of Costco’s total revenue, and it is growing faster than the company as a whole.
The Business Model Analyst Take
Costco is one of the cleanest examples in all of retail of separating where you create value from where you capture it. It creates value at the shelf, selling goods so cheaply that a membership pays for itself in a few trips, and it captures profit at the membership counter, where fees flow almost untouched to the bottom line. Every other design choice, the lean SKU count, the Kirkland brand, the well-paid workforce, the 92.3% renewal rate, exists to protect that loop.
The risk worth watching is not the warehouse business, which is compounding nicely. It is the stock. Costco trades at a premium that assumes this machine keeps humming indefinitely, which leaves little margin for a membership-growth slowdown or a tariff shock to merchandise costs. The model is arguably the best in retail. The question for anyone studying it, or investing in it, is whether the price already reflects that. As a business to learn from, Costco remains close to the platonic ideal of a membership flywheel done right.


