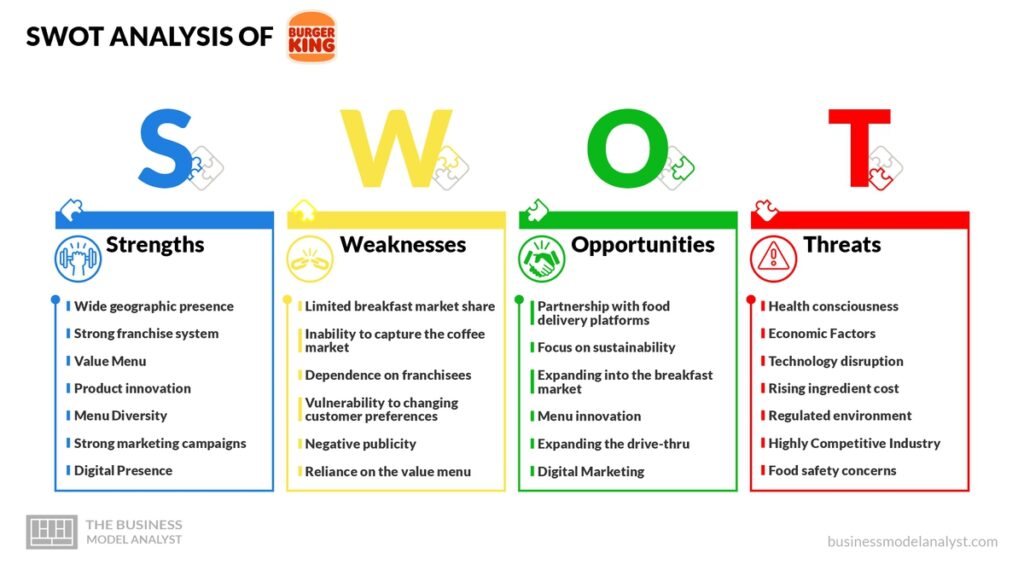

Burger King SWOT Analysis (2026), at a glance
What it is: A structured assessment of Burger King’s internal Strengths and Weaknesses alongside the external Opportunities and Threats shaping the brand in 2026.
Why it matters now: Burger King is four years into its “Reclaim the Flame” turnaround (a combined commitment of more than $700 million plus a $1 billion acquisition of its largest U.S. franchisee, Carrols). The chain posted +3.2% U.S. comparable sales in Q3 2025 and operates 19,732 restaurants across 125 countries under Restaurant Brands International (NYSE: QSR).
The one-line takeaway: Burger King’s brand equity, scale, and international momentum are genuinely strong, but the U.S. business still trades behind McDonald’s and Wendy’s on traffic, and the next phase of growth hinges on remodels, value perception, refranchising Carrols, and getting the Whopper relaunch right.
Introduction
You can tell a lot about a brand by what strangers say to its executives in airports. Tom Curtis, the president of Burger King U.S. and Canada, told The Globe and Mail in April 2026 that the most common reaction he gets when people learn what he does is some version of “I used to love Burger King.” That tense (“used to”) is the strategic problem the chain has been throwing money at since 2022. It is also the right lens for an honest Burger King SWOT analysis in 2026.
The good news for the brand: the turnaround is finally showing up in the numbers. Q3 2025 U.S. same-store sales rose 3.2%, the best print since early 2024, and the international business grew system-wide sales by 12.1%. The harder news: Burger King’s U.S. dollar share still trails McDonald’s by a wide margin, value perception remains fragile, and a $1 billion bet on buying back its biggest franchisee has temporarily inflated the corporate store count to levels Burger King has explicitly said it does not want to maintain.
Below is the full Burger King SWOT analysis for 2026, built on the most recent figures from Restaurant Brands International’s SEC filings and earnings reports, with the strategic context that recycled SWOT articles tend to skip. For background on the framework itself, see How to Do a SWOT Analysis.
Burger King at a Glance (2026 Snapshot)
| Item | Detail |
|---|---|
| Parent company | Restaurant Brands International (NYSE: QSR, TSX: QSR) |
| Founded | 1954, Miami, Florida (James McLamore and David Edgerton) |
| Headquarters | Miami, Florida, U.S. |
| RBI CEO | Joshua Kobza |
| BK President, U.S. and Canada | Tom Curtis |
| Signature product | Flame-grilled Whopper (introduced 1957, refreshed February 2026) |
| Global restaurant count (Dec 31, 2024) | 19,732 |
| Restaurants outside U.S. and Canada | 12,650 |
| Countries and territories served | 125 |
| Franchised share of RBI system | Approximately 95% |
| RBI 2024 revenue | $8.41 billion |
| RBI 2024 system-wide sales (all four brands) | Roughly $45 billion |
| Burger King U.S. comparable sales (Q3 2025) | +3.2% |
| Burger King International comparable sales (Q3 2025) | +6.4% |
| Active turnaround plan | “Reclaim the Flame” (2022 to 2028) |
Burger King SWOT Analysis Snapshot
| Internal: Strengths | Internal: Weaknesses |
|---|---|
| Globally recognized brand anchored by the flame-grilled Whopper | U.S. share gap versus McDonald’s and Wendy’s |
| Scale of 19,732 restaurants across 125 countries | High dependence on franchisees (about 95% of system) |
| Capital-light, 95% franchised model | Persistent value perception issues |
| Funded turnaround (Reclaim the Flame plus Carrols) above $1.2 billion | Breakfast and coffee share well behind specialists |
| International momentum (+12.1% Q3 2025 system-wide sales) | Recurring marketing missteps that invite backlash |
| External: Opportunities | External: Threats |
|---|---|
| Royal Reset remodels lifting AUVs toward $2 million per unit | Tighter consumer discretionary spend on QSR |
| Royal Perks loyalty and digital ordering | Beef cost inflation pressuring franchisee margins |
| Premium menu refresh, starting with the 2026 Whopper relaunch | Aggressive value wars led by McDonald’s and Wendy’s |
| Refranchising Carrols units to local operators | Health, environmental, and labor regulation |
| AI-driven operations (BK Assistant and Patty) | Reputational risk from AI surveillance and ad controversies |
Burger King Strengths
S1. Iconic global brand built on the Whopper
The Whopper is one of the most recognizable single products in fast food, full stop. It anchors marketing, drives traffic, and gives Burger King a story McDonald’s cannot copy without looking like a follower. In February 2026, Burger King updated the Whopper for the first time in nearly a decade, moving to a premium bun, a new mayo, and a clamshell box that finally addresses the long-running “smushed Whopper” complaint. Curtis told CNN it was “like putting our famous iconic burger in a tuxedo instead of a leisure suit.” The choice to elevate the icon, rather than try to replace it, is exactly the kind of brand discipline that pays off in legacy QSR.
S2. Scale very few competitors can match
| Metric | Value | Source |
|---|---|---|
| System-wide restaurants (Dec 31, 2024) | 19,732 | RBI 2024 10-K |
| Countries and territories | 125 | RBI 2024 10-K |
| Restaurants outside U.S. and Canada | 12,650 | RBI 2024 10-K |
| U.S. restaurants (year-end 2024) | 6,701 (5,524 franchised + 1,177 corporate) | QSR Magazine |
Only McDonald’s, with more than 40,000 restaurants globally, has a larger QSR burger footprint. For the comparison set, see the McDonald’s SWOT Analysis and Wendy’s SWOT Analysis.
S3. Capital-light franchise model
About 95% of RBI’s system-wide restaurants are franchised. That keeps Burger King’s own balance sheet light while concentrating operational capex and risk with operators. Royalty, advertising fund, and property revenues from those franchisees are steady and high-margin, which is why RBI continues to post attractive operating margins even when category traffic softens. For a deeper read on how this model converts franchise fees into revenue, see the Burger King Business Model breakdown.
S4. A funded, multi-year turnaround plan
Most legacy brands talk about transformation. Burger King has actually put money on the table.
| Initiative | Amount | Timeframe | Purpose |
|---|---|---|---|
| Fuel the Flame (advertising and digital) | $150 million | 2022 to 2024 | Rebuild media presence and digital infrastructure |
| Royal Reset (remodels and equipment) | $250 million | 2023 to 2025 | Around 800 high-quality projects |
| Additional remodel co-investment | $300 million | 2024 to 2028 | Reach 85% to 90% modern image |
| Carrols acquisition | Roughly $1 billion | May 2024 | Acquire 1,023 BK restaurants from largest franchisee |
| Carrols remodel commitment | Roughly $500 million | 2024 to 2028 | Modernize Carrols-acquired units |
That is more than $2.2 billion of committed capital and acquisition spend directed at the U.S. business, endorsed by more than 93% of U.S. franchisees at launch.
S5. International is now the real growth engine
In Q3 2025, Burger King International grew system-wide sales by more than 12% and posted +6.4% comparable sales, well ahead of the U.S. business. Tim Hortons Canada and the international segment together generate roughly 70% of RBI’s earnings, per CEO Josh Kobza on the Q3 2025 earnings call. Burger King India, which trades publicly on the Indian exchanges, continues to outperform the system average on unit growth. The international story is the part of the Burger King SWOT analysis that most U.S.-only competitor articles miss entirely.
Burger King Weaknesses
W1. The U.S. share gap
Burger King is the second-largest burger chain in the U.S. by units, yet remains a distant runner-up to McDonald’s on dollar share and traffic. In Canada, the gap is even starker. Burger King held just a 5.3% dollar share of the Canadian quick-service burger market in early 2026, according to The Globe and Mail’s interview with Tom Curtis. Closing the gap requires consistent execution across remodels, marketing, and value, which is exactly what the next four years of Reclaim the Flame need to prove.
W2. Franchisee dependence concentrates operational risk
The flip side of an asset-light, 95% franchised model is limited corporate control. Service quality, store cleanliness, and remodel pace vary by operator. The Carrols deal was at its core an admission that some legacy operators needed to be replaced or pushed forward faster than they could deliver on their own. After the Carrols acquisition, Burger King ended 2024 with 1,177 corporate locations, far above the company’s preferred long-term footprint. RBI has been clear it does not intend to run a corporate fleet this large for long.
W3. Value perception keeps cracking under pressure
Independent reviewers and franchisee disclosures have repeatedly flagged that the gap between Burger King’s cheapest and most premium burgers does not feel meaningful enough to consumers. While McDonald’s leans on the $5 Meal Deal narrative and Wendy’s on $5 Biggie Bags, Burger King has cycled through multiple value structures without one that reliably drives traffic. Q3 2025 was a comeback quarter precisely because the chain stopped chasing the value wars and leaned back into the Whopper.
W4. Breakfast and coffee remain structural underperformers
Mornings are a profit pool Burger King has never fully cracked.
| Daypart leader | Brand | Why BK trails |
|---|---|---|
| U.S. breakfast | McDonald’s | Egg McMuffin halo, all-day-ish breakfast history, scale |
| U.S. specialty coffee | Starbucks | Brand equity, loyalty program, store density |
| U.S. value coffee | Dunkin’ | Drive-thru positioning, beverage focus |
| Canadian morning | Tim Hortons (RBI sister brand) | Cultural anchor in Canada |
Burger King’s breakfast menu has had multiple reboots over the past decade without a breakthrough. The same is true of coffee. Within RBI itself, Tim Hortons owns the morning daypart in Canada, which makes a Burger King breakfast push commercially awkward inside the parent company.
W5. Marketing missteps invite real backlash
Burger King’s bold marketing tradition is a strength when it lands (“Whopper Detour,” “Moldy Whopper”) and a recurring weakness when it overreaches. The February 2026 “call my president” hotline, which directed customers to a number tied to terms of service handing over voice and likeness rights, drew sharp critiques from the consumer press, including pieces in Adafruit Industries’ editorial and AOL. The pattern of bold then apologetic is itself a weakness.
Burger King Opportunities
O1. Royal Reset remodels and the “Sizzle” prototype
| Initiative | Status (year-end 2025) | Why it matters |
|---|---|---|
| Royal Reset remodels | Roughly 400 expected in 2025 | Stores reopened for 6+ months post double-digit sales uplifts |
| Modern image target | 85% to 90% of U.S. system by 2028 | Up from a starting point well under 50% |
| “Sizzle” prototype | Used in roughly two-thirds of remodeled Carrols stores | Refreshes layout, drive-thru, digital touchpoints |
| Average remodeled unit volume | Around $2 million in annual unit volume | Materially above pre-remodel average |
O2. Refranchising Carrols faster than originally planned
RBI initially expected to refranchise the 1,023 Carrols stores over three to seven years. Just over a year in, the company is ahead of plan, with 50 to 100 units targeted for sale in 2025 and a larger number planned for 2026. A new “Crown Your Career” program is opening franchising pathways to existing managers and above-restaurant leaders. Smaller, local operators historically run higher-quality Burger King stores than mega-franchisees, so this could lift system-wide service quality alongside unit economics.
O3. Loyalty, digital, and the Royal Perks economy
Royal Perks gives Burger King a first-party data engine it lacked five years ago. Combined with mobile ordering, in-store kiosks, and delivery integrations, the digital channel is now the lowest-cost way to grow check size and frequency. RBI has explicitly named digital as one of its three strategic priorities (alongside Quality and Service) in its 2024 10-K.
O4. Premium menu refresh and selective plant-based plays
The 2026 Whopper relaunch is a template, not a one-off. The pattern is to keep the icon, elevate the experience, and let franchisees hold pricing steady (as Curtis confirmed to CNN). On the plant-based side, the Impossible Whopper delivered a 36% sales lift in test markets at launch and brought new customers into the brand. As the broader plant-based category cooled in 2024 and 2025, Burger King wisely slowed expansion, but the option value remains. See the Beyond Meat SWOT Analysis for the supply-side context, and the Burger King target market analysis for how these innovations align with the brand’s audience.
O5. AI-driven operations through BK Assistant and “Patty”
In February 2026, Burger King announced BK Assistant, a voice-enabled AI platform powered by an OpenAI base model, with a chatbot named “Patty” embedded in employee headsets. According to Fast Company, Patty is currently piloted in roughly 500 U.S. restaurants and scheduled to roll out to all U.S. locations by end of 2026, with Canada following in the second half of 2026. The opportunity is real on three fronts: real-time inventory and menu updates, on-the-line training, and aggregate friendliness coaching. Executed well, this is genuine operational leverage. Executed poorly, it becomes the next reputational issue (see T4).
Burger King Threats
T1. Beef and labor cost inflation
RBI executives explicitly flagged elevated beef costs as a Q3 2025 margin headwind. Beef is the single largest input cost in a Whopper, and franchisees absorb most of the squeeze. According to Restaurant Business Online, QSR-wide beef inflation has been a sector pressure since 2024. The $300,000 average EBITDA per BK U.S. restaurant target gets harder every time commodity costs reset upward.
T2. Aggressive value wars from competitors
McDonald’s $5 Meal Deal and Wendy’s $5 Biggie Bag have set a low price-point bar that is hard to match without margin damage. Burger King chose to “avoid the value wars” in 2025, which protected unit economics but ceded traffic share in soft quarters. The strategy works only as long as the elevated Whopper experience and remodels carry traffic on their own. If they slow, the value pressure returns.
T3. Health, environmental, and labor regulation
QSR menus continue to draw regulatory scrutiny on calorie labeling, sodium, marketing to children, and packaging waste. Labor rules ratchet up costs each year (California’s FAST Act minimum wage being the most visible recent example). Burger King franchisees, not RBI corporate, bear most of the operating cost increases, but RBI absorbs the reputational risk.
T4. Reputational risk around AI and marketing
The Patty rollout drew immediate “creepy” framing in mainstream coverage from NBC News and Fast Company, and the consumer hotline rights controversy followed soon after. Even if the AI tool is genuinely a coaching aid and not a surveillance lever, the perception risk among workers and customers is non-trivial.
T5. Currency and macro exposure outside the U.S.
International is the growth engine, but RBI’s 2024 results were dented by unfavorable FX movements. A stronger U.S. dollar drags reported numbers even when local-currency performance is strong, and political or economic stress in key markets (Argentina, China, Brazil, France, the U.K.) can quickly reverse momentum.
Burger King Competitive Landscape (Quick Comparison)
| Competitor | Approx. Global Units | Key Threat to BK |
|---|---|---|
| McDonald’s | Over 40,000 | Scale, breakfast dominance, brand muscle |
| Wendy’s | Roughly 7,200 | Value menu, fresh beef positioning, social media |
| Chick-fil-A | Roughly 3,050 (U.S.-focused) | Chicken-occasion share, service quality |
| Chipotle | Roughly 3,700 | Premium QSR positioning, digital |
| Jollibee | Roughly 1,600+ | Cultural advantage in Asia and select international markets |
| KFC (see KFC Marketing Strategy) | Roughly 30,000 | Chicken category leader in key international markets |
Strategic Outlook for Burger King in 2026 and Beyond
The honest read on Burger King is not “struggling” and not “winning.” It is “in motion.” The Reclaim the Flame thesis (better restaurants, better marketing, better economics for franchisees) is finally producing the same-store sales pattern executives promised four years ago. International is doing the heavy lifting. The U.S. is no longer losing.
What changes the story is whether Burger King hits these by 2028:
| Strategic Lever | What “winning” looks like by 2028 |
|---|---|
| Modern image rollout | 85% to 90% of U.S. units remodeled |
| Carrols refranchising | Corporate footprint reduced toward pre-Carrols levels |
| U.S. comparable sales | Sustained positive comps even in soft quarters |
| Franchisee EBITDA | At or near the $300,000 average target per BK U.S. restaurant |
| International segment | Continued double-digit system-wide sales growth |
| Digital and loyalty | Meaningful share of orders through Royal Perks |
| Whopper relaunch reception | Sustained mix and check uplift, no price-hike backlash |
Miss those, and “I used to love Burger King” stays the brand’s most common feedback. Hit them, and Burger King moves from second-place burger chain to a genuinely modern QSR brand with a credible second act.
Frequently Asked Questions
Who owns Burger King in 2026?
Burger King is owned by Restaurant Brands International (RBI), a Canadian multinational holding company listed on the NYSE and TSX under the ticker QSR. RBI also owns Tim Hortons, Popeyes, and Firehouse Subs.
Who is the CEO of Burger King?
Burger King does not have a standalone CEO. Joshua Kobza is the CEO of parent company Restaurant Brands International. Tom Curtis serves as President of Burger King U.S. and Canada.
How many Burger King restaurants are there in 2026?
As of December 31, 2024 (the most recent full-year disclosure), Burger King operated 19,732 restaurants across 125 countries and territories, with 12,650 of those outside the U.S. and Canada. The U.S. footprint stood at 6,701 stores at year-end 2024 (5,524 franchised plus 1,177 corporate following the Carrols acquisition).
What is Burger King’s biggest strength?
Brand recognition tied to the flame-grilled Whopper, combined with a globally distributed franchise system of nearly 20,000 restaurants and a funded, multi-year turnaround plan. The Whopper is one of the most recognizable single products in fast food.
What is Burger King’s biggest weakness in 2026?
A persistent U.S. market share gap versus McDonald’s, combined with fragile value perception that competitors exploit during price-led traffic battles, and underperformance in the breakfast and coffee dayparts.
What is “Reclaim the Flame”?
Reclaim the Flame is Burger King’s U.S. turnaround plan launched in September 2022. The original commitment was $400 million ($150 million for advertising and digital under “Fuel the Flame,” and $250 million for the Royal Reset remodel program). In April 2024, an additional $300 million in remodel co-investment was added to reach 85% to 90% modern image by 2028.
Why did RBI buy Carrols Restaurant Group?
Carrols was Burger King’s largest franchisee in the U.S., operating 1,023 stores. RBI acquired Carrols in May 2024 for roughly $1 billion to accelerate remodels, improve operational consistency, and then refranchise the units to smaller local operators over three to seven years (now running ahead of that schedule).
Is Burger King doing well in 2026?
Mixed but improving. In Q3 2025, U.S. comparable sales rose 3.2% (the best print since early 2024) and Burger King International posted +6.4% comparable sales with +12.1% system-wide sales growth. Margins remain pressured by beef inflation and broader QSR softness, but the trajectory is the most positive it has been in years.
What changed about the Whopper in 2026?
On February 26, 2026, Burger King announced its first significant Whopper update in nearly a decade: a more premium bun, an improved mayonnaise, and a clamshell box replacing the paper wrapper. The flame-grilled beef patty and core toppings remain unchanged, and franchisees were asked to hold pricing steady.
Bottom Line
Burger King in 2026 is not the company that “stagnated for years.” It is a brand with real money behind a real plan, finally producing real results. The strengths are global brand power, an asset-light franchise model, and momentum overseas. The weaknesses are a U.S. share gap, breakfast and coffee blind spots, and a value story that still does not sing. Opportunities cluster around remodels, refranchising, digital, premium menu work, and AI operations. Threats cluster around beef costs, value-driven competitors, regulation, and reputation risk.
The next two years are the real test. If Burger King hits 85% to 90% modern image, gets the corporate fleet back near historical levels, keeps comps positive through a tougher consumer cycle, and lands the Whopper relaunch without a price-driven backlash, the SWOT for 2028 will look meaningfully different. If not, this is what the floor of a slow turnaround looks like, and competitors will be glad to keep it there.