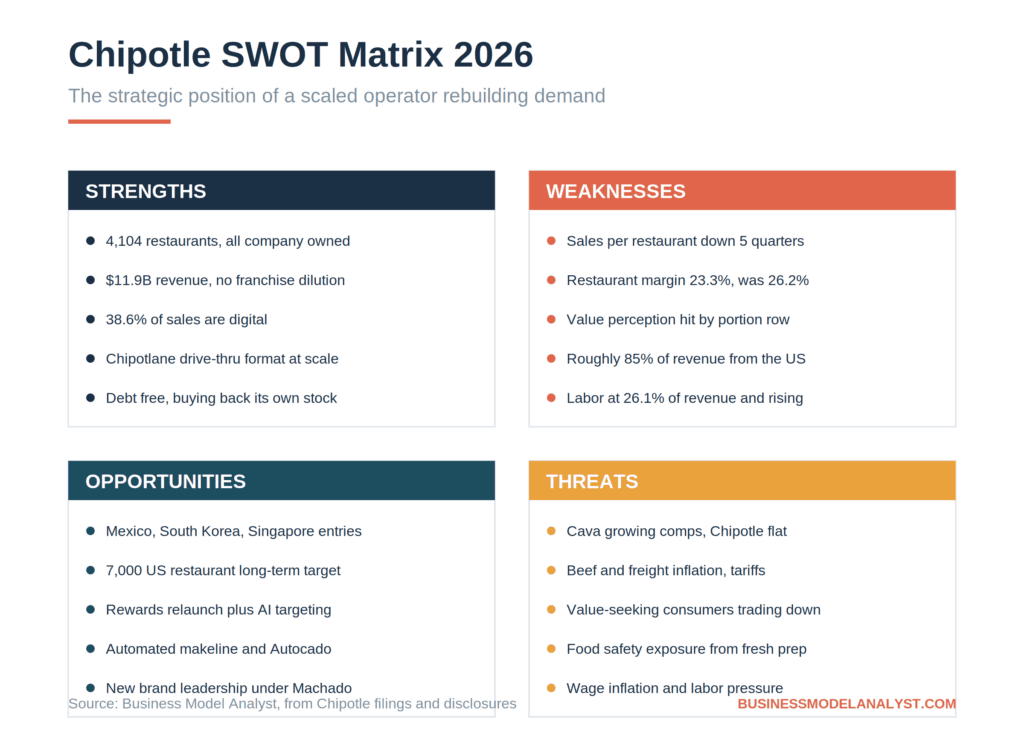
Chipotle SWOT Analysis at a Glance What it is: A strategic evaluation of Chipotle Mexican Grill (NYSE: CMG), the fast casual chain that owns and operates every one of its restaurants in North America and Europe. Core strength: Scale without franchising. More than 4,100 restaurants, $11.9 billion in 2025 revenue, and 38.6% of sales flowing through digital channels. Core weakness: Sales per restaurant have fallen for five consecutive quarters while restaurant level margin dropped from 26.2% to 23.3% in a single year. Biggest opportunity: International expansion into Mexico, South Korea and Singapore, plus a long term target of 7,000 US restaurants. Biggest threat: A value conscious consumer, beef and freight inflation, and a faster growing Cava taking the fast casual growth narrative. Bottom line: Chipotle is no longer a growth story that runs on demand. It is a scaled operator adding restaurants faster than it can fill them.
Chipotle Mexican Grill is an American fast casual chain built on customizable burritos, bowls and tacos. Steve Ells opened the first location near the University of Denver in 1993 with a loan from his father, and the company went public on the NYSE in 2006. Its differentiator was never the food category. It was the operating model: one assembly line, a deliberately short ingredient list, no franchisees, and a supply chain built around a sourcing promise the company calls Food with Integrity.
That model produced one of the great compounding stories in restaurants. It also produced the crisis of 2015, when E. coli and norovirus outbreaks cut the stock in half and forced a multi year rebuild of food safety protocols. Chipotle recovered, digitized, added drive thru Chipotlanes, and by 2023 was trading at a multiple usually reserved for software companies.
The story in 2026 is different, and the difference is the entire point of this analysis. Revenue is still growing. Restaurant count is still growing. But the growth is coming from opening doors, not from filling them. This SWOT analysis examines a company that has to rebuild demand before it can rebuild margin.
Chipotle at a Glance (2026)
| Metric | Figure |
|---|---|
| Founded | 1993, Denver, Colorado |
| CEO | Scott Boatwright (appointed 2024) |
| Chief Brand Officer | Fernando Machado (effective June 2026) |
| Total restaurants | 4,104 as of March 31, 2026 |
| Company-owned restaurants | 4,090 |
| Partner-operated restaurants | 14 |
| FY2025 revenue | $11.9 billion, up 5.4% |
| FY2025 comparable sales | Down 1.7% |
| FY2025 net income | Roughly $1.54 billion, essentially flat |
| Q1 2026 revenue | $3.09 billion, up 7.4% |
| Q1 2026 comparable sales | Up 0.5%, driven by 0.6% transaction growth |
| Q1 2026 restaurant level margin | 23.3%, down from 26.2% |
| Digital share of sales | 38.6% |
| Average restaurant sales | $3.09 million |
| Employees | Over 135,000 |
| Markets | US, Canada, UK, France, Germany, Middle East, Mexico |
| 2026 guidance | Flat comparable sales, 350 to 370 new openings |
Chipotle Strengths
Chipotle’s advantages are structural rather than promotional. They come from choices about ownership, format and technology that competitors would need years to replicate.
Total ownership of the estate
Chipotle is the only restaurant company of its size that owns and operates all of its restaurants in North America and Europe. There is no franchisee layer between the brand and the guest. Every dollar of restaurant revenue flows onto Chipotle’s own income statement, which is why $11.9 billion of system sales in 2025 was also $11.9 billion of reported revenue. Compare that to a franchised model where the parent collects a royalty on the same volume.
The trade is capital intensity for control. Chipotle funds every build, which is why it spent $180 million on property and equipment in a single quarter. In exchange, it can change an ingredient, a price or an operating procedure across 4,000 locations without negotiating with a franchise association. When food safety is your existential risk, that control is worth more than the capital it costs. This is the pivot point of the whole Chipotle business model.
A digital business hiding inside a restaurant business
Digital sales represented 38.6% of food and beverage revenue in the first quarter of 2026, up from 35.4% a year earlier. Roughly two thirds of those digital orders are bowls or salads, which is exactly the order type that automation can handle.
The Chipotlane, a pickup only drive thru lane for digital orders, is the physical expression of this. Around 80% of new company-owned restaurants are being built with one, and 42 of the 49 restaurants opened in Q1 2026 included a Chipotlane. Chipotlane locations open with higher sales, higher margins and better returns than traditional builds, which means the newest cohort of the estate is structurally better than the average.
Balance sheet strength and buyback capacity
Chipotle carries no long term debt. It generated $651 million in operating cash flow in the first quarter of 2026 alone and repurchased $700.8 million of its own stock in the same period, following $741.6 million in the fourth quarter of 2025. Basic share count fell from 1.354 billion to 1.298 billion year over year, a reduction of roughly 4%.
That capacity matters more in a downturn than in a boom. A company that can fund 350 openings a year and buy back $2.8 billion of stock annually out of cash flow does not need the equity market’s permission to keep executing.
Brand equity in the ingredient story
Chipotle’s sourcing commitments, no artificial colors, flavors or preservatives, remain genuinely differentiated in a category where most competitors buy on price. The brand has never had to explain why its food costs more, because the answer is embedded in the marketing. That equity is what made the portion size controversy so damaging, and it is also what makes recovery plausible. Damaged trust in a brand people already believe in is a very different problem from having no brand at all. The Chipotle marketing strategy has always leaned on this asset harder than on discounting.
Chipotle Weaknesses
This is where the 2026 analysis diverges sharply from the version of this story most people carry in their heads.
Sales per restaurant have fallen for five straight quarters
Average restaurant sales dropped from $3.186 million in Q1 2025 to $3.094 million in Q1 2026, declining in every intervening quarter. Over the same five quarters, Chipotle added 309 company-owned restaurants.
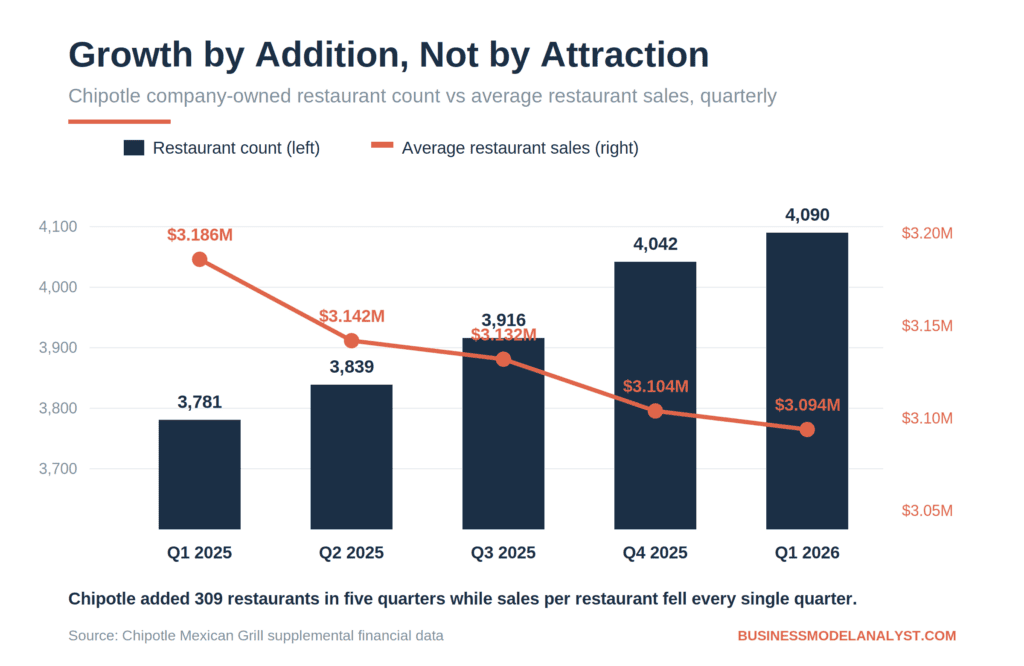
That divergence is the single most important fact about Chipotle right now. Revenue grew 5.4% in 2025 while comparable sales fell 1.7%, which means roughly seven points of unit expansion carried the top line past a shrinking base business. The growth is real, but it is arithmetic, not demand.
Margin compression across every cost line
In the first quarter of 2026, food, beverage and packaging rose to 29.6% of revenue from 29.2%. Labor rose to 26.1% from 25.0%. Occupancy rose to 5.5% from 5.2%. Other operating costs rose to 15.6% from 14.4%. Restaurant level margin fell to 23.3% from 26.2%, a 290 basis point decline in twelve months.
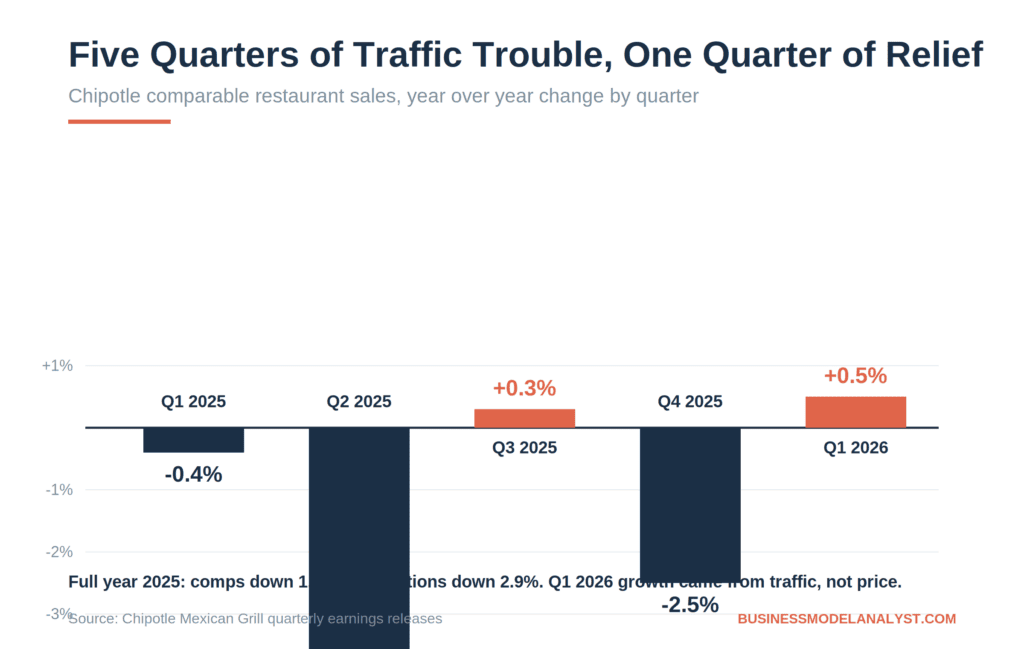
Operating margin fell from 16.7% to 12.9%. Net income dropped 21.7% year over year while diluted earnings per share fell only 17.9%, the gap absorbed by share repurchases. Buybacks are cushioning the reported number, which is a legitimate use of capital but not a substitute for operating performance.
A damaged value perception
The portion size backlash of 2024 and 2025 did lasting damage. Viral social media complaints about inconsistent scoop sizes turned into analyst research, then into a management response, then into a durable belief that Chipotle had quietly reduced what you get for your money. For a brand whose premium was always justified by what landed in the bowl, that is a direct attack on the value proposition.
The consequence shows in the transaction line rather than the check line. Chipotle held average check up through 2025 while transactions fell 2.9% for the year. Customers were not paying less. There were fewer of them. Anyone studying the Chipotle target market should note that the pain concentrated among younger and more price sensitive guests, precisely the cohort that built the brand.
Concentration in a single market
Chipotle operates more than 80 restaurants in Canada, around 20 in the UK, six in France and two in Germany, plus roughly 15 partner-operated locations in the Middle East. Against a base of over 4,000, international is a rounding error. The overwhelming majority of revenue is exposed to one consumer economy, one wage regulation environment and one set of ingredient costs.
The company is fixing this, but from a standing start, and the fix takes a decade rather than a quarter.
Leadership discontinuity
Brian Niccol left for Starbucks on August 31, 2024, and comparable sales began declining almost immediately afterward. Scott Boatwright inherited the turnaround. Chief brand officer Chris Brandt stepped down in January 2026. Fernando Machado, formerly CMO of Restaurant Brands International and Activision Blizzard, started as chief brand officer on June 1, 2026, alongside a newly created chief digital officer role. Chipotle is rebuilding its senior commercial team in the middle of the recovery it needs that team to lead.
Chipotle Opportunities
The Recipe for Growth reset
Announced with the fourth quarter 2025 results, Recipe for Growth is a five pillar framework: protect the core through operational and culinary execution, evolve brand messaging and accelerate menu innovation, modernize the model with AI and technology, expand global reach, and cultivate talent. It is a demand rebuilding plan, not a margin defense plan, and management has been explicit that margin recovery is the downstream outcome rather than the objective.
The first quarter of 2026 provided the first evidence it might work. Comparable sales rose 0.5% on transaction growth of 0.6%, with average check down 0.1%. For the first time in years, more people came, and they were not paying more per visit to make the number work.

International expansion with real momentum
Chipotle opened its first restaurant in Mexico in Nuevo León in July 2026, a genuinely bold move for an American chain selling Mexican inspired food to Mexican consumers. It formed a joint venture with South Korea’s SPC Group in September 2025 to enter Asia, with South Korea planned for 2026 and Singapore in early 2027. The Alshaya partnership in the Middle East has grown to around 15 restaurants across the UAE, Kuwait and Qatar.
The domestic runway is also substantial. Chipotle targets 7,000 US restaurants against roughly 4,000 today, with 350 to 370 openings guided for 2026 including 10 to 15 international partner-operated locations.
The rewards relaunch and AI personalization
Chipotle relaunched its loyalty program in April 2026 as Rewards on Repeat. The strategic gap it addresses is stark: rewards transactions represented about 90% of app orders but only around 20% of in-restaurant orders. Most of Chipotle’s guests were invisible to its data.
Early results were encouraging, with daily enrollments up nearly 25% after the relaunch, supported by in-store menu panels and QR codes. A planned single scan feature will let guests pay and earn points in one step. Every incremental in-restaurant member converts an anonymous transaction into a targetable one.
Kitchen automation at scale
Chipotle’s $100 million Cultivate Next venture fund has backed Vebu, maker of the Autocado avocado processing robot, and Hyphen, developer of the Augmented Makeline that assembles bowls and salads underneath a human operated line. Hyphen raised $25 million led by Chipotle’s fund with participation from Cava, an unusual case of two direct competitors co-funding the same supplier.
Given that labor now consumes 26.1% of revenue and roughly 65% of digital orders are bowls or salads, the theoretical payoff is large. The caveat is timing: this technology has been in test since 2023 and remains unscaled.
Menu innovation as a traffic lever
The return of Chipotle Honey Chicken, the launch of Cilantro Lime Sauce, the Burrito Vault double protein promotion and the Chicken al Pastor revival all point to a deliberately higher cadence of limited time offers. Management noted that Cilantro Lime Sauce was outperforming its predecessor at roughly twice the incidence rate. For a brand that historically resisted menu proliferation, a faster LTO calendar is a meaningful strategic shift.
Chipotle Threats
Cava is winning the growth narrative
Cava raised its 2026 same restaurant sales guidance to a range of 4.5% to 6.5% while Chipotle guides to approximately flat. Cava’s digital mix reached 37.9% of revenue in fiscal 2025, essentially matching Chipotle’s. Consensus estimates put Cava’s 2026 sales growth at 26.2% against Chipotle’s 8.4%.
Cava is roughly a tenth of Chipotle’s size and its valuation prices in flawless execution. But it is taking the story, and stories drive capital, talent and site availability. The broader Chipotle competitors set now includes Qdoba, Moe’s, Sweetgreen and a Taco Bell that has aggressively courted value seekers.
Input cost inflation with limited pricing room
Beef and chicken inflation, freight costs and the tariffs enacted in 2025 all pressured 2025 food costs. Chipotle’s pricing is guided to only 1% to 2% for 2026, deliberately restrained because raising prices into a value perception problem risks accelerating the traffic decline the pricing was meant to offset.
That is a genuine strategic bind. The company can protect margin or protect traffic. In 2026 it has chosen traffic, and the margin numbers show what that choice costs.
A trading down consumer
Fast casual pricing sits above quick service and below casual dining, which is a comfortable position in an expansion and an exposed one in a squeeze. When households tighten, a $13 burrito bowl competes with a $7 combo meal and with a grocery run. Chipotle’s own management has framed the current environment as a dynamic consumer backdrop where guests are more selective.
Food safety remains an existential risk
The 2015 outbreaks are a decade old, but the underlying exposure has not changed. Chipotle prepares fresh, largely unprocessed food across more than 4,000 locations with over 135,000 employees. The company’s own risk disclosures list food safety incidents and foodborne illness among its principal risks. A single serious incident would hit a brand whose entire premium rests on ingredient trust.
Labor cost and regulatory pressure
Labor reached 26.1% of revenue in Q1 2026, and $11.9 million of that quarter’s labor line was an estimated liability for legal proceedings. State minimum wage increases, particularly in California, union organizing activity and immigration enforcement affecting restaurant labor availability all compound the pressure on a company that employs its entire workforce directly rather than pushing that exposure onto franchisees.
Frequently Asked Questions
Is Chipotle still profitable in 2026? Yes. Chipotle reported roughly $1.54 billion of net income on $11.9 billion of revenue in 2025 and $302.8 million of net income in the first quarter of 2026. Profitability is intact but compressing: net income fell 21.7% year over year in Q1 2026 as costs rose faster than revenue.
Why did Chipotle’s sales decline? Comparable sales fell 1.7% in 2025 because transactions fell 2.9%. Fewer customers visited, driven by a value perception problem amplified by the portion size controversy and by a broader consumer pullback on discretionary restaurant spending. Higher average checks masked part of the decline in reported revenue.
Who is Chipotle’s CEO? Scott Boatwright, appointed in 2024 after Brian Niccol left to become CEO of Starbucks. Fernando Machado joined as chief brand officer in June 2026.
How many Chipotle restaurants are there? There were 4,104 restaurants as of March 31, 2026, comprising 4,090 company-owned and 14 partner-operated locations. The company guides to 350 to 370 new openings in 2026 and targets 7,000 US restaurants long term.
Does Chipotle franchise? No. Chipotle owns and operates every restaurant in North America and Europe. It uses partner-operated agreements only for international markets such as the Middle East, South Korea, Singapore and Mexico.
Is Cava a real threat to Chipotle? Directionally yes, structurally not yet. Cava operates a few hundred restaurants against Chipotle’s 4,000 plus, so it takes no meaningful share today. What it does take is the growth narrative and the marginal urban lunch customer, and it is doing so while growing comparable sales at a rate Chipotle has not seen in three years.
What is Chipotle’s biggest weakness? The gap between unit growth and unit productivity. Chipotle added 309 restaurants over five quarters while average sales per restaurant fell in each of them. Adding capacity to a base that is getting less productive per location is the core strategic problem, and it is what the Recipe for Growth strategy is designed to reverse.
The Business Model Analyst Take
The mistake most analyses of Chipotle make in 2026 is treating this as a demand crisis. It is not, or at least not only. It is a productivity crisis in a business model that was designed to scale on demand.
Chipotle’s operating model has one dependency that franchised chains do not share: because the company owns every restaurant, every point of average unit volume decline lands directly on its own margin. A franchisor with falling unit volumes collects a smaller royalty. Chipotle absorbs the full deleverage. That is why a 1.7% comparable sales decline in 2025 translated into a 290 basis point restaurant margin collapse by the first quarter of 2026. Ownership amplifies the upside and it amplifies the downside, and 2026 is the first time in a decade the market has been reminded which direction that works in.
The strategic tension is that Chipotle is accelerating openings into that deleverage. Guiding 350 to 370 new restaurants while average restaurant sales fall every quarter is a bet that the productivity decline is cyclical and the real estate opportunity is not. If Boatwright is right, the company emerges with a larger, better located, Chipotlane heavy estate just as demand recovers. If he is wrong, Chipotle will have spent three years building capacity into a structurally smaller per unit business.
Q1 2026 was the first data point on the optimistic side of that bet, and the quality of it mattered more than the size. A 0.5% comp built on 0.6% transaction growth with average check slightly negative is exactly the shape a recovery should have. Growth built on price would have been a warning. Growth built on traffic is evidence the brand can still pull people through the door without paying them to come.
Two things now decide the story. First, whether traffic growth holds against the easy second quarter comparison, since lapping a minus 4% quarter should produce a bigger number than 0.5% if the recovery is genuine. Second, whether restaurant margin stabilizes near 23% rather than stepping down again, which would show the company is not simply buying its customers back with pricing restraint it cannot afford indefinitely.
Chipotle spent a decade as a growth stock that happened to sell burritos. It is now a scaled operator with a cost problem and a brand it has not finished repairing. That is a less exciting company. It is not necessarily a worse business, and at a valuation roughly half its peak, the market has already priced in a fair amount of the disappointment.
Explore more strategic breakdowns in our library of SWOT analysis examples, including the McDonald’s SWOT Analysis, or read how the company frames its own purpose in the Chipotle mission and vision statement.