
Yeti built its brand on a customer who does not exist in most of its sales figures anymore.
The company was founded in 2006 by Roy and Ryan Seiders to sell coolers to hunters and fishing guides who kept breaking cheap ones. Twenty years later, Yeti is a $1.87 billion business whose single largest product category is a stainless steel cup. The gap between the brand story and the receipts is the whole story of Yeti’s target market, and it is where most analyses of this company go wrong.
Here is the version built on numbers the company actually reported.
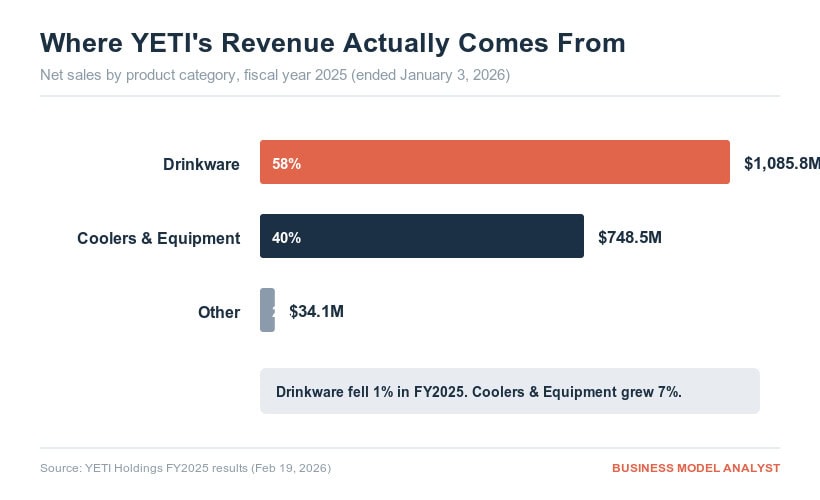
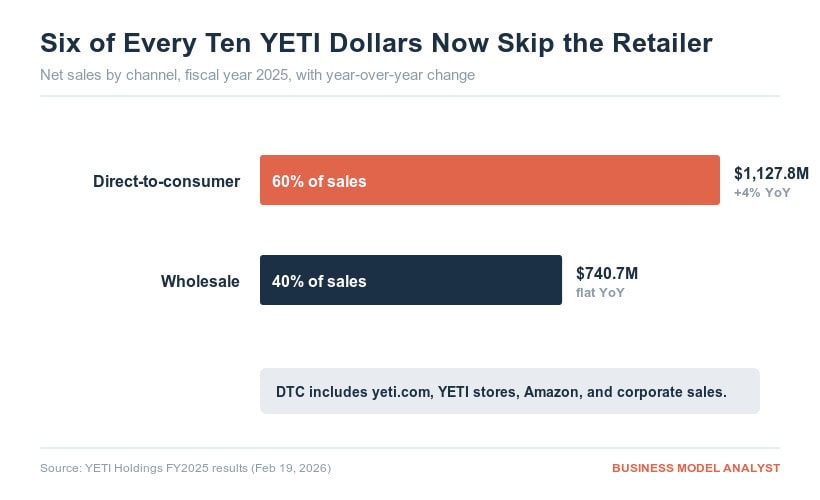
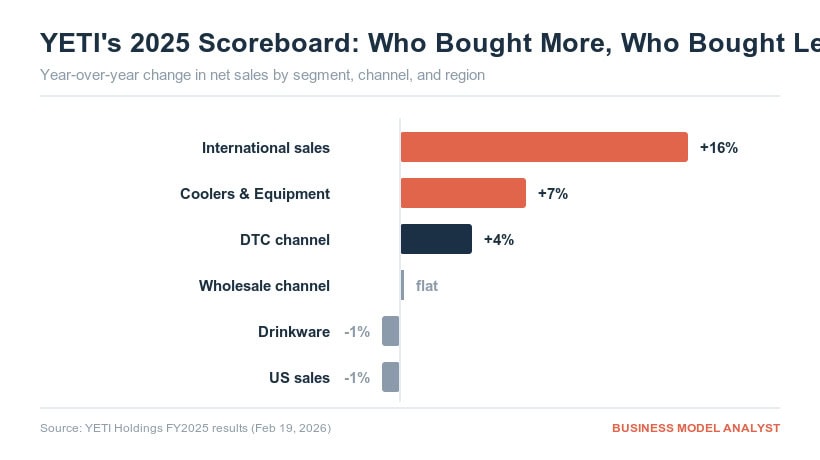
What is Yeti’s target market? Yeti’s target market is affluent, quality-driven consumers who buy premium insulated drinkware, coolers, and outdoor gear. It spans four groups: the original core of hunters, anglers, and ranchers; a much larger everyday premium buyer who uses Yeti products for commuting, the office, the gym, and the beach; corporate and B2B buyers purchasing customized drinkware for gifting and events; and a fast-growing international consumer in Australia, Europe, Canada, and Japan. In fiscal 2025, drinkware accounted for 58% of net sales, direct-to-consumer accounted for 60%, and international sales grew 16% while US sales fell 1%.
Yeti at a Glance
| Metric | Fiscal 2025 (ended January 3, 2026) |
|---|---|
| Net sales | $1,868.5 million (up 2%) |
| Drinkware | $1,085.8 million (58% of sales, down 1%) |
| Coolers & Equipment | $748.5 million (40% of sales, up 7%) |
| Direct-to-consumer | $1,127.8 million (60% of sales, up 4%) |
| Wholesale | $740.7 million (40% of sales, roughly flat) |
| US sales | $1,474.1 million (79% of sales, down 1%) |
| International sales | $394.4 million (21% of sales, up 16%) |
| Adjusted gross margin | 57.4% |
| Headquarters | Austin, Texas |
The Four Customers Yeti Actually Serves
Yeti does not report customer segments. It reports categories, channels, and regions. Reading those three splits against each other gives you a far more reliable segmentation map than the demographic profiles floating around the internet, most of which cite precise household income figures with no source attached.
The tension is obvious once it is on a page. Yeti’s marketing speaks to the first group. Yeti’s revenue comes from the second. And Yeti’s growth now comes from the fourth.
Demographics: What Can Be Verified, and What Cannot
Search “Yeti customer demographics” and you will get confident claims that the median Yeti household earns more than $125,000 and that 70% hold a bachelor’s degree. Those numbers appear on multiple content sites without a single source between them. We are not going to repeat them.
What can be established:
| Dimension | Profile | Basis |
|---|---|---|
| Income | Skews affluent. A Rambler tumbler is priced at a multiple of a supermarket equivalent, and Yeti has held a 57% to 58% adjusted gross margin while refusing to compete on price | Company margin disclosures and price positioning |
| Gender | Started male-dominated through hunting and fishing. Broadened substantially through drinkware, colorways, and seasonal drops | Company commentary on drinkware and colorway expansion driving new consumers |
| Age | Broad adult range, weighted toward working-age buyers with discretionary income rather than teens | Product mix and price points |
| Geography | 79% United States, with Australia, Europe, Canada, and Japan as the growth markets | FY2025 regional disclosure |
| Household type | Suburban families, tailgaters, boaters, campers, plus urban professionals who never leave the city | Category breadth and use-occasion positioning |
The honest summary: Yeti’s demographic is defined less by age or gender than by willingness to pay a premium for durability that most buyers will never actually test. That is a psychographic dressed as a demographic, and it is the reason Yeti’s audience has been able to widen so far without the brand snapping.
The Segmentation That Actually Explains 2025
Yeti’s fiscal 2025 splits the target market cleanly into two halves moving in opposite directions.
The half that stalled. US sales fell 1%. Drinkware fell 1%. The American everyday-premium drinkware buyer, the customer who carried Yeti from 2014 onward, is saturated, discount-hunting, and being fought over by Stanley, Owala, Hydro Flask, and a dozen cheaper lookalikes. Yeti itself blamed a promotional market environment and cautious wholesale buying. In plain terms: everybody who wants a $40 cup already owns three.
The half that is compounding. International sales grew 16% to $394.4 million, and 25% in the fourth quarter alone. Coolers and Equipment grew 7%, driven by bags, soft coolers, and cargo. Australia and Europe led, and Japan launched in the second quarter of 2025 with an ecommerce debut planned for 2026 and Korea and China behind it.
Two customers, one company. The US drinkware buyer is a retention problem. The international equipment buyer is an acquisition opportunity. Yeti’s 2026 guidance of 6% to 8% sales growth is, functionally, a bet that the second one outruns the first.
Psychographics: Buying an Identity, Not an Insulated Cup
Yeti sells the same thing Patagonia sells, just to a different tribe. Where the Patagonia target market buys ideology, the Yeti buyer buys competence. The product says: I am the kind of person who might need this.
Three psychographic drivers hold the audience together:
- Overbuilt as a value system. The appeal is not that the cooler keeps ice for six days. It is that it could, if you ever went somewhere for six days.
- Tribal signaling without politics. The Yeti sticker on a truck window operates like a fraternity pin for a specific American culture: fishing, hunting, tailgating, boating, ranching. Yeti has been careful never to spend that equity on anything divisive.
- Permanence as a rebuke to disposability. Buy once, cry once. It justifies the price and it makes the purchase feel like a moral position rather than a splurge.
The vulnerability inside all of this is that the everyday buyer never tests the claim. If a competitor delivers 80% of the performance at 50% of the price, and nobody is measuring, the premium is defended by brand alone. That is precisely the fight Yeti is now in.
Channel Behavior: How the Target Market Buys
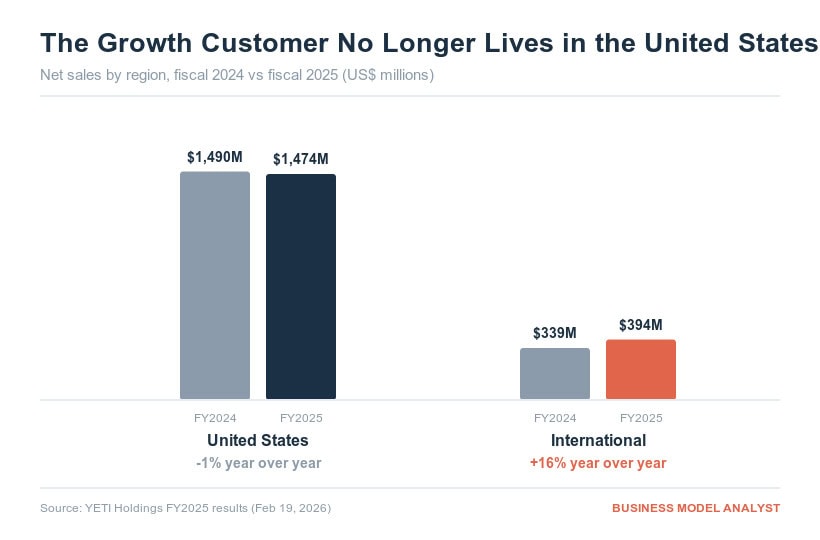
Sixty percent of Yeti’s revenue is direct-to-consumer, and that channel is doing more work every year. But DTC at Yeti is not one thing. It bundles four distinct buying behaviors:
| DTC sub-channel | Behavior it captures |
|---|---|
| Yeti.com | Brand loyalists, customizers, full-price buyers |
| Amazon Marketplace | Convenience buyers and comparison shoppers, the ones most exposed to Owala and Stanley |
| Yeti retail stores | Discovery and gifting, plus regional brand-building |
| Corporate sales | B2B bulk customization, the least discussed and most defensible piece |
Corporate sales deserve more attention than they get. A laser-etched Yeti Rambler with a company logo is a gift the recipient actually keeps, which makes Yeti one of the few consumer brands with a genuine swag moat. It also happens to be a segment where price sensitivity is low and the buyer is a procurement manager, not a shopper deciding between four tumblers on Amazon.
Wholesale, meanwhile, was roughly flat, with US retail partners keeping inventories tight. Yeti noted that sell-through outpaced sell-in, which means the end consumer was buying faster than retailers were restocking. That is a retailer-confidence story, not a demand story, and it is worth separating the two.
The Competitive Set, by Who They Steal From
| Competitor | Which Yeti segment it attacks | Weapon |
|---|---|---|
| Stanley | Everyday premium drinkware buyer | Viral culture, Quencher form factor, cupholder fit |
| Owala | Everyday premium drinkware buyer | Lid design, lower price, Amazon dominance |
| Hydro Flask | Younger lifestyle drinkware buyer | Colorways, established campus presence |
| RTIC | Core outdoor cooler buyer | Near-identical build at a lower price |
| Igloo, Coleman | Casual and budget cooler buyer | Distribution and price |
| Traeger, Solo Stove | Adjacent outdoor-lifestyle wallet | Competing for the same premium backyard spend |
For the full field, see our breakdown of Yeti competitors.
Note where the pressure sits. Nobody is seriously attacking the hunting-guide cooler segment, because that segment is small and Yeti owns it. The attack is entirely on the mass drinkware buyer, which is where 58% of the revenue lives. That is an uncomfortable structural fact and it explains the flat US drinkware line better than any macro commentary.
How Yeti Is Buying Its Way Into New Segments
Three acquisitions since 2024 map directly onto target-market expansion rather than cost synergy:
| Acquisition | Price | Segment it unlocks |
|---|---|---|
| Mystery Ranch (2024) | $36.2 million | Technical backpacks. Military, hunting, and serious hiking users. Fed into the Ranchero and Skala lines |
| Butter Pat (2024) | Not disclosed | Cast iron cookware. The home-and-hearth premium buyer |
| Helimix shaker bottle assets (2025) | $38.0 million | Sport, health, and wellness. Launched as the Yonder shaker bottle in Q4 2025 |
The Helimix deal is the most revealing. A shaker bottle is a gym product. It puts Yeti in front of a fitness consumer who has no relationship with hunting, fishing, or coolers, and who currently buys from Blender Bottle or Owala. That is a deliberate widening of the demographic funnel at the exact moment the outdoor-lifestyle drinkware buyer has stopped growing.
FAQ
Who is Yeti’s target market? Affluent consumers willing to pay a premium for durable outdoor products. It splits into four groups: core outdoor users (hunters, anglers, ranchers), everyday premium consumers who buy drinkware for daily use, corporate and B2B buyers purchasing customized gifting, and international consumers in Australia, Europe, Canada, and Japan.
Is Yeti still an outdoor brand or a lifestyle brand? Financially, it is a lifestyle brand with outdoor credibility. Drinkware, mostly used in cars, offices, and gyms, was 58% of fiscal 2025 net sales. The outdoor gear line supplies the brand permission that lets Yeti charge lifestyle prices.
Why is Yeti’s US business flat? Yeti cited a promotional market environment, cautious wholesale buying, and inventory constraints from a supply chain transition. Underneath those is a saturation problem: US premium drinkware is crowded and heavily discounted, and Stanley and Owala are fighting for the same buyer.
Where is Yeti growing? Outside the United States. International sales rose 16% in fiscal 2025 to $394.4 million and 25% in the fourth quarter, led by Australia and Europe, with Japan launched in 2025 and Korea and China in the pipeline. International is now 21% of the business.
Who are Yeti’s main competitors? Stanley, Owala, and Hydro Flask in drinkware, RTIC and Igloo in coolers, and adjacent premium outdoor-lifestyle brands competing for the same discretionary spend. Detail in our Yeti SWOT analysis.
Does Yeti sell to businesses? Yes. Corporate sales are part of its direct-to-consumer channel and cover customized, laser-etched drinkware and gear for gifting and events. Yeti named corporate sales as one of the drivers of DTC growth in the fourth quarter of 2025.
The Business Model Analyst Take
Yeti’s target market has quietly become two target markets, and the company’s valuation depends on which one you think it is.
The bull case is that Yeti is an early-stage global premium brand with 21% international mix, a category expansion engine buying its way into fitness and cookware, and a 57% gross margin that proves the pricing power is real. The bear case is that 58% of revenue comes from a saturated American cup market under attack from cheaper, trendier rivals, and that the outdoor heritage which justifies the price is a story most customers experience only through a logo.
Both are true. That is what makes Yeti interesting.
The strategic question the numbers force is uncomfortable: Yeti’s brand is built on a customer who buys coolers, and its business is built on a customer who buys cups. Those two people used to be the same person. In 2026, increasingly, they are not. Every dollar Yeti spends defending the drinkware buyer is a dollar it does not spend converting the international equipment buyer, who is growing sixteen times faster.
Watch the international mix. Management has signaled it wants that number materially higher. If it reaches 30% while gross margin holds, Yeti will have successfully swapped one target market for another without anybody noticing. If drinkware keeps sliding and international stalls, the premium unwinds fast, because a lifestyle brand without growth is just an expensive cup.