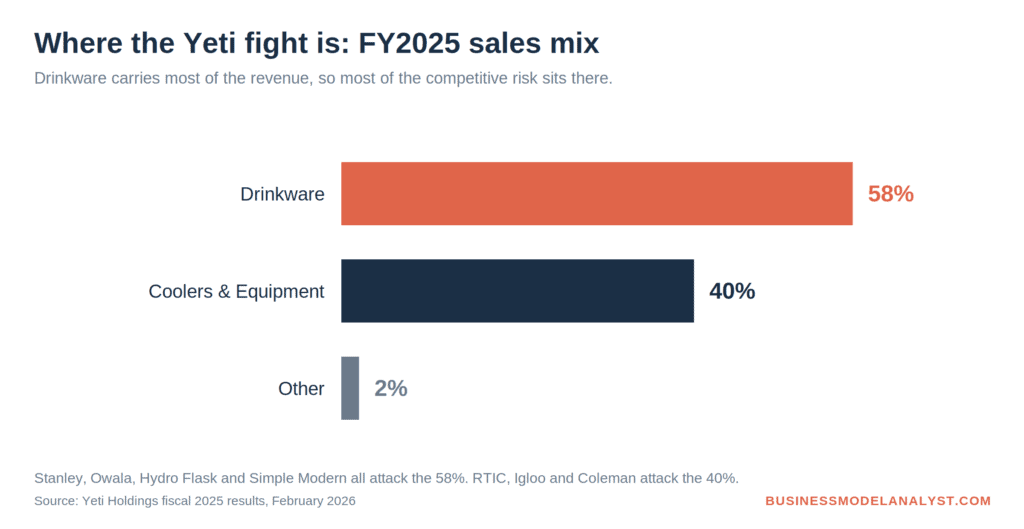
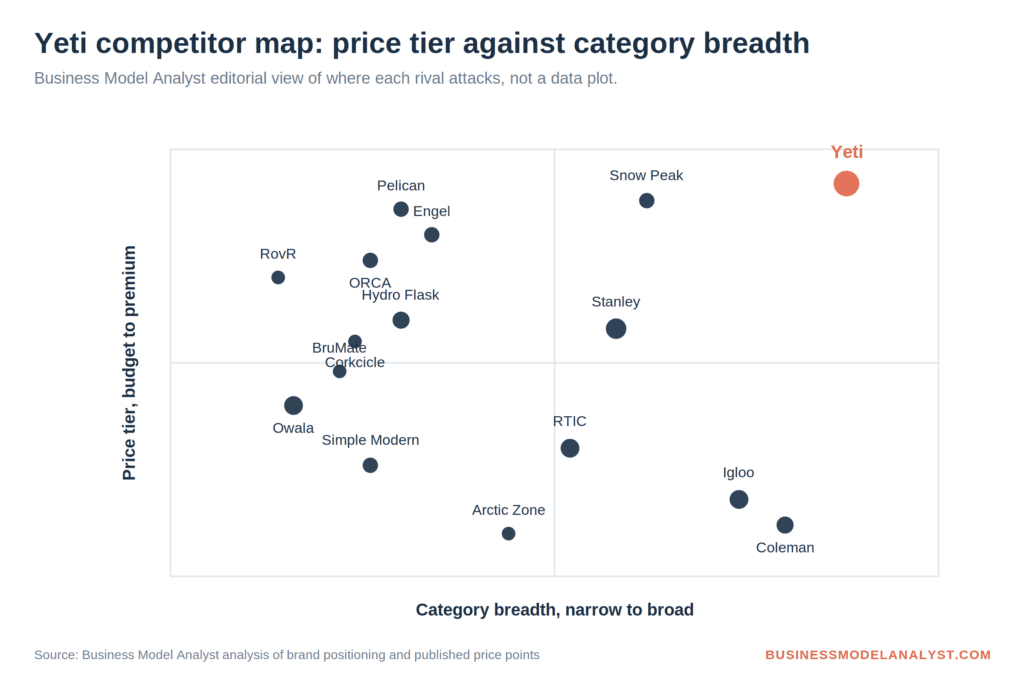
Yeti competitors, defined: Yeti’s competitors are the brands fighting it for premium insulated drinkware and cooler spend. The field splits into four groups: drinkware challengers (Stanley, Owala, Hydro Flask, Simple Modern, BrüMate), premium cooler rivals (RTIC, ORCA, Engel, Pelican, RovR), mass-market volume players (Igloo, Coleman, Arctic Zone), and premium lifestyle brands (Snow Peak, Corkcicle). Drinkware accounted for 58% of Yeti’s fiscal 2025 sales, so most of the competitive pressure lands there.
Most Yeti competitor lists get the map wrong. They pad the field with backpack makers and camping-stove companies, then describe every rival with the same sentence: cheaper than Yeti, almost as good. That framing was accurate in 2017, when Yeti’s problem was a Houston startup selling lookalike coolers at half price. It stopped being accurate the moment a 113-year-old thermos brand turned a $45 tumbler into a TikTok collectible and took the drinkware category away from everyone.
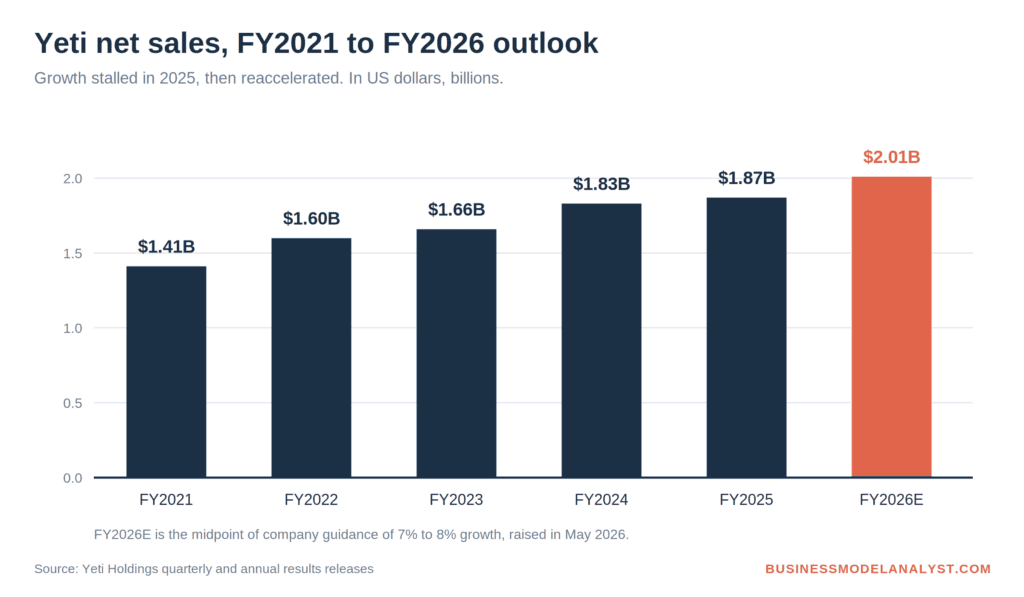
Yeti finished fiscal 2025 with adjusted net sales of $1.87 billion, up 2%. That single number holds the whole story. The company grew, barely, while US drinkware went sideways under attack from Stanley and Owala, and coolers and international markets carried the year. Then Yeti hit back: first quarter 2026 sales rose 8.3% to $380.4 million, wholesale grew 19%, and management raised full-year guidance.
This piece maps the 15 companies that matter, ranked by how much revenue each one puts at risk, with current financials for the ones that disclose them.
Yeti at a glance
How the field actually splits
Yeti sells two businesses that face two different sets of enemies.
The drinkware business generated 58% of fiscal 2025 revenue and competes against brands with no cooler heritage at all. Stanley, Owala and Simple Modern never built a rotomolded anything. They compete on lids, colors and social proof.
The coolers and equipment business generated 40% and competes against the price-attack brands Yeti sued a decade ago, plus the mass-market incumbents that were selling coolers before Yeti existed.
Grouping those two fights into one ranked list of “alternatives” hides the thing that matters: a $30 Owala bottle and a $250 RTIC hard cooler take money from Yeti in ways that require completely different responses.
Group one: the drinkware challengers
1. Stanley
Stanley is the competitor that changed the category. Pacific Market International bought the brand in 2002 and ran it as a rugged thermos business until 2020, when it hired Terence Reilly from Crocs. Revenue went from $73 million in 2019 to roughly $750 million in 2023 on the back of the Quencher, seasonal color drops and manufactured scarcity. Our Stanley marketing strategy breakdown covers how that playbook worked.
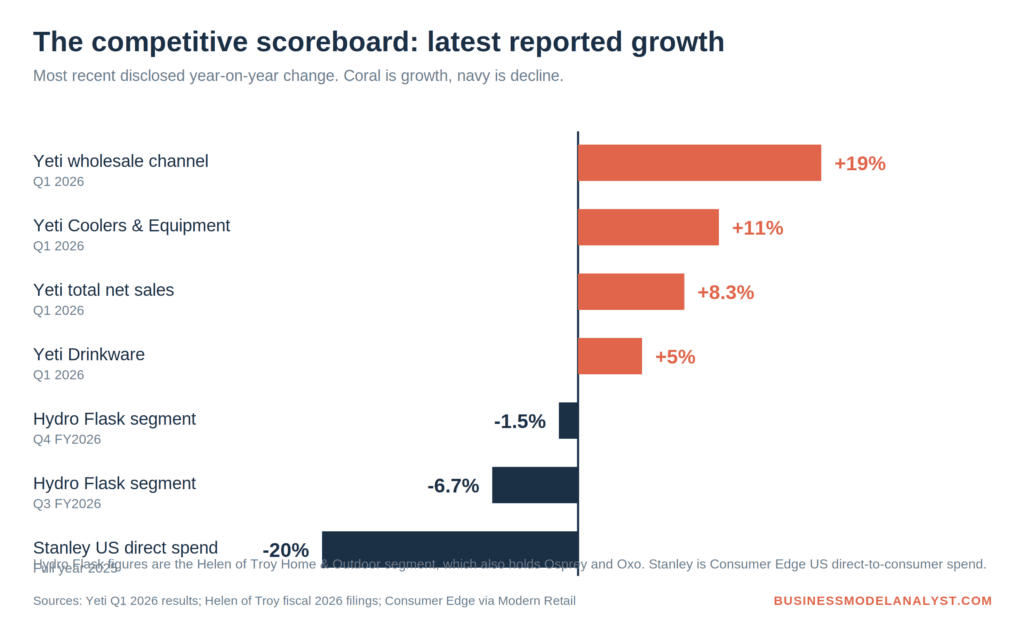
The frenzy has cooled. Consumer Edge data cited by Modern Retail shows US direct-to-consumer spend on Stanley grew more than 300% in 2022 and fell about 20% in 2025, with 2026 running hot and cold quarter to quarter. Stanley still holds roughly 30% of US direct-to-consumer drinkware spend, which makes it the largest single threat to Yeti’s biggest category.
Two self-inflicted wounds hurt: the January 2024 lead controversy over the vacuum-sealing pellet, and a December 2024 recall of 2.4 million travel mugs after 91 reports of lids detaching and 38 burn injuries worldwide. The related lead class action was dismissed in April 2026.
Stanley’s answer to saturation looks a lot like Yeti’s. Global brand president Matt Navarro has pushed the company into bags, coolers, sports sponsorships and international markets. Between mid-February and mid-April 2026, Stanley launched the Vitalize Collection of backpacks and totes, the Clutch Bottle and the Flowstate Spring Bottle. Its first cooler-bag line in 2024 drew a waitlist of roughly 50,000 people inside two weeks.
2. Owala
Owala is the brand that beat Stanley at its own game with a better lid. It overtook Stanley as the best-selling stainless steel water bottle in the United States in 2023, driven by the patented FreeSip spout that lets you sip or swig without tilting. E-commerce tracking by Particl found monthly sales volume up more than 400% and revenue up more than 200% between January and August 2024.
Owala sits below Yeti on price and narrower on range, which makes it dangerous in a specific way: it takes the entry-level buyer who might otherwise have bought a Yeti Rambler as a first premium bottle. Yeti loses the customer before the relationship starts. In August 2025 Owala launched customizable double-insulated bottles with color-changing technology, aimed at the same young buyer.
3. Hydro Flask
Hydro Flask is the cautionary tale in this group. Helen of Troy owns it inside the Home & Outdoor segment alongside Osprey and Oxo, and that segment has been shrinking. Sales fell 10.3% in the first quarter of fiscal 2026, 6.7% in the third, and 1.5% in the fourth, with the company blaming competition, softer demand and retailer inventory rebalancing in insulated beverageware.
The write-down tells the rest of the story. Helen of Troy booked $414.4 million in non-cash impairment charges in the first quarter of fiscal 2026, cutting goodwill by $317.0 million and other intangibles by $97.4 million. It ran through three CEOs in a year before G. Scott Uzzell took over.
Hydro Flask is not gone. Management said it beat plan in the quarter ended February 2026 on the strength of new launches, including the Micro Flask built for the Japanese market. But a brand this impaired competes on discount, which pressures Yeti’s pricing without threatening its position.
4. Simple Modern
Simple Modern attacks from underneath. It sells insulated tumblers and bottles at Walmart, Target and Amazon at prices well below Stanley and Yeti, with fast trend-following on colors and lid formats. The company has no outdoor heritage and does not pretend to have one. For a shopper who wants the look of a $45 cup for $20, Simple Modern closes the gap. Yeti cannot follow it down without damaging the premium positioning that produces a 57% gross margin.
5. BrüMate
BrüMate carved out the alcohol-adjacent corner of insulated drinkware: wine tumblers, can coolers, growlers and the Hopsulator line. Based in Denver, it competes on personality and use case rather than durability claims. The overlap with Yeti is narrow but real, since Yeti sells the same tailgate and campsite occasion through its Rambler and Colster products.
Group two: the premium cooler rivals
6. RTIC
RTIC remains the most direct threat to Yeti’s cooler business, and the two have history. Brothers John and Jim Jacobsen launched RTIC in 2015 selling rotomolded coolers that looked a lot like Yeti’s at roughly half the price, with the tagline “Over Built, Not Over Priced.” Yeti sued for patent, trade dress and trademark infringement plus unfair competition.
The interesting detail: Yeti’s claim centered on rubberized T-shaped latches rather than the cooler shape itself, which suggests its lawyers doubted a broad design patent would survive scrutiny. RTIC settled in February 2017, paid an undisclosed sum, stopped selling the disputed hard coolers, soft coolers and drinkware, and redesigned them.
RTIC redesigned and kept going. It sells direct to consumer, prices at a visible discount to Yeti, and has since expanded into drinkware and bags. The lawsuit bought Yeti time. It did not remove the competitor.
7. ORCA
Outdoor Recreation Company of America launched in 2012 and competes on American manufacturing, extended ice retention and a wider color and customization range than Yeti offers. It targets the buyer who wants premium performance without the Yeti logo, which is a small but durable segment.
8. Engel
Engel has built insulated coolers since 1962 and holds a strong position with anglers and hunters. Its dry-box and live-bait products give it credibility in commercial and serious sport-fishing channels where Yeti competes as a lifestyle brand. Engel also sells drinkware and bags, making it one of the few rivals matching Yeti’s category breadth at a lower price point.
9. Pelican
Pelican comes at Yeti from the opposite direction: it built its reputation on protective cases for cameras, weapons and industrial equipment, then applied that engineering to coolers. Pelican Elite coolers carry a lifetime guarantee and often beat Yeti on published ice-retention claims. For the buyer who treats a cooler as equipment rather than an accessory, Pelican is the credible alternative.
10. RovR
RovR occupies the wheeled-cooler niche Yeti has never owned outright. Its all-terrain wheels, tow handles and modular accessory system solve a transport problem that Yeti’s hard coolers create. Small brand, narrow category, but it takes the campsite and festival buyer who values mobility over brand.
Group three: the volume players
11. Igloo
Igloo has manufactured coolers from Katy, Texas since 1947 and sells more units than Yeti will ever sell, through Costco, Target, Academy and Dick’s Sporting Goods at $80 to $140 price points. It competes on distribution and scale rather than performance.
Igloo’s 2025 was rough. In February it recalled about 1,060,000 90-quart Flip & Tow rolling coolers in the United States, plus 47,000 in Canada and 23,000 in Mexico, after reports that the tow handle could pinch and amputate fingertips. It expanded the recall in May by another 130,000 US units, bringing the total to nearly 1.2 million. By the expansion date Igloo had logged 78 reports of fingertip injuries, including 26 amputations, bone fractures or lacerations. A class action followed in Pennsylvania federal court.
For Yeti, a competitor’s safety recall is free brand reinforcement. Durability claims land harder when the budget option is recalling a million units.
12. Coleman
Coleman is the default cooler in American garages and the volume anchor of the category. Owned by Newell Brands, it sells at every mass retailer at prices Yeti will never approach. Coleman does not threaten Yeti’s core customer. It defines the price floor that makes Yeti’s positioning legible, and it captures the buyer who decides a $400 cooler is absurd.
13. Arctic Zone
Arctic Zone competes in soft coolers, lunch bags and backpack coolers at mass-market prices, with recycled-material sourcing as a differentiator. Its overlap with Yeti sits in the soft-cooler category, where Yeti’s Hopper line carries a substantial premium for comparable everyday use.
Group four: the premium lifestyle brands
14. Snow Peak
Snow Peak has built Japanese camping equipment since 1958 and competes with Yeti for the same premium outdoor customer through a different door. It sells tents, cookware, furniture and titanium drinkware with design credibility Yeti has been trying to buy. Its strength in Asia, Europe and Australia matters more as Yeti pushes international, which reached roughly 21% of sales and grew 25% in the fourth quarter of 2025.
15. Corkcicle
Corkcicle sells insulated drinkware as a design object rather than outdoor gear, competing on finish, shape and gifting appeal. It takes the office and corporate-gift buyer, which overlaps with Yeti’s corporate sales program inside its direct-to-consumer channel.
Yeti competitors compared
What Yeti is doing about it
Yeti has answered the drinkware squeeze by refusing to fight on price and buying its way into categories where nobody has a foothold yet.
It paid $36.2 million for Mystery Ranch in early 2024, then used that design capability to launch the Skala hike pack family, where demand has outrun supply. It paid $38 million for Helimix, which puts Yeti into shaker bottles and opens the gym and wellness occasion. Butter Pat brought cookware, including skillets and a ranch pan. None of these are large yet. All of them extend the brand into premium durable goods where Stanley and Owala have no permission to follow.
The geographic answer is working faster. International sales grew 25% in the fourth quarter of 2025 and 9% in the first quarter of 2026, with Japan launched in the second quarter of 2025 and management guiding international toward 23% of full-year sales. Yeti is selling the same drinkware to markets that have not saturated yet.
The first quarter of 2026 suggests the counterattack is landing. Wholesale grew 19%, its strongest quarter in more than three years. Coolers and equipment grew 11% to $156.1 million. US drinkware returned to growth. Our Yeti target market analysis covers who is buying each half of that business.
The unresolved risk is margin. Tariffs cost Yeti $0.35 of adjusted EPS in 2025, and full-year gross margin guidance of 56.5% to 57.0% implies continued pressure. A premium brand that cannot hold its margin eventually stops being a premium brand.
Frequently asked questions
Who is Yeti’s biggest competitor? Stanley, by revenue at risk. Stanley holds roughly 30% of US direct-to-consumer drinkware spend, and drinkware was 58% of Yeti’s fiscal 2025 sales. In coolers, RTIC is the closest direct substitute.
Is Yeti losing market share? In US drinkware, Yeti lost ground through 2025 to Stanley and Owala amid a promotional market. It recovered in the first quarter of 2026, when drinkware grew 5% and US drinkware returned to growth. Coolers and equipment and international sales have grown throughout.
Why is Yeti so expensive compared to alternatives? Yeti prices for a 57.4% adjusted gross margin, which funds product development, marketing and the acquisitions taking it into bags, cookware and fitness. Rivals like RTIC and Simple Modern skip that spending and pass the savings on, which is why they undercut Yeti by half without matching its category range.
Did Yeti sue RTIC? Yes. Yeti filed suit in 2016 alleging patent, trade dress and trademark infringement plus unfair competition, focused on rubberized T-shaped latches. RTIC settled in February 2017, paid an undisclosed sum, ceased sales of the disputed products and redesigned them.
What is a good cheaper alternative to a Yeti cooler? RTIC gives the closest performance-per-dollar match on rotomolded hard coolers. Engel and ORCA sit between RTIC and Yeti on price with strong ice retention. Igloo and Coleman serve the buyer who wants a cooler rather than a premium cooler.
Is Stanley a Yeti competitor or a different category? Both brands compete head-on in insulated drinkware, which is Yeti’s largest category. Stanley has also entered coolers and bags since 2024, moving further into Yeti’s territory.
The Business Model Analyst Take
The old story about Yeti competitors was a price story: rivals sell the same thing for less, and Yeti defends with lawsuits and brand. That story is finished. Yeti won the price war against RTIC in court in 2017 and kept its margin.
The current fight is a category fight, and Yeti is not the one losing it. Stanley took the drinkware category from everyone in 2023, then discovered that a viral product has a half-life. US direct spend on Stanley fell about 20% in 2025. Hydro Flask’s parent wrote off $414.4 million. Owala won the bottle segment with a lid and now has to prove it can do something else. Igloo recalled 1.2 million coolers.
Yeti sat at $1.87 billion through the worst of it and came out of the first quarter of 2026 growing 8% with wholesale up 19%. The company that spent five years being told it was overpriced turned out to have the only balance sheet in the category strong enough to buy Mystery Ranch, Helimix and Butter Pat while the fashionable competitors were managing recalls and impairments.
The threat worth watching is not Stanley. It is the tariff line. Yeti’s entire argument rests on a 57% gross margin, and that margin has already given up 120 basis points. Competitors cannot take Yeti’s customer at current prices. Cost inflation can force Yeti to raise them until somebody can.