
Host cities are declaring economic victory. The data says the tournament was a pricing event, not a demand event, and the difference decides who actually got paid.
The 2026 World Cup ended Sunday with Spain beating Argentina, and US host cities are counting the money. Bank of America logged the strongest national card-spending growth in over four years. Hotels in host markets pushed revenue per available room up roughly 26% on match days. But occupancy in those same markets was down 1.3 percentage points through the first 17 days of the tournament, and leisure and hospitality shed 61,000 jobs in June. The tournament did not bring more customers. It gave sellers permission to raise prices on the customers who were already coming.
Every mega-event produces two stories. The first one is anecdotal, immediate, and true: a bar owner in Phoenixville, Pennsylvania grossed $13,000 in a single day with the power out and a broken toilet. The second one shows up weeks later in occupancy tables and payroll surveys, and it almost never matches the first. Both stories are running right now, and the gap between them is the most useful thing operators can learn from this tournament.
What Happened
Bank of America reported that total US credit and debit card spending rose 6.3% year over year in June, the strongest growth in more than four years. That number has been widely repeated as a host-city figure. It is not. It is the national number, and the bank’s own analysis attributes much of it to falling gas prices freeing up discretionary spend. The host-city figure across the full group stage was 5.4%.
The genuinely striking number inside the BofA data is the split. Local spending in host cities rose about 2.7%. Non-local spending, meaning people transacting outside their home metro area, rose 17.4%. Visitors did show up and they did open their wallets. The question is what they displaced.
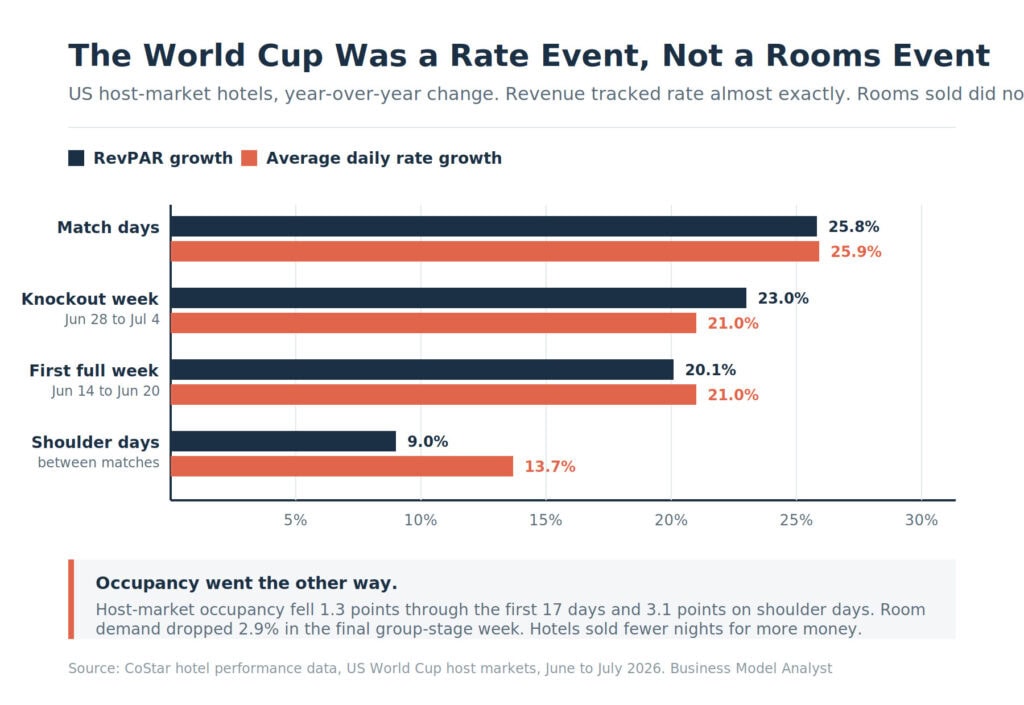
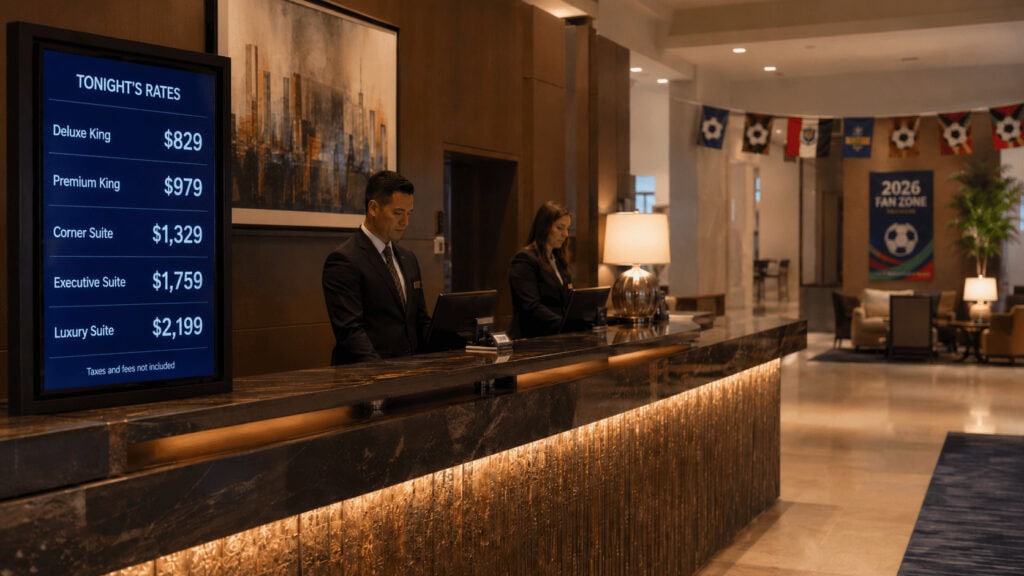
Hotels give the clearest answer. According to CoStar, match days across US host markets produced a 25.8% RevPAR gain, on a 25.9% increase in average daily rate, with occupancy essentially flat. On shoulder days, the days between matches, RevPAR rose 9% on a 13.7% rate increase while occupancy fell 3.1 percentage points. Every host market except San Francisco lost occupancy on shoulder days. During the final week of the group stage, host markets posted a 16.7% RevPAR increase on a 2.9% decline in room demand.
Read that sequence again. Revenue went up. Rooms sold went down.
Then the labor data landed. FIFA had projected the tournament would support roughly 185,000 full-time-equivalent jobs in the United States. The Bureau of Labor Statistics reported that leisure and hospitality employment fell by 61,000 in June, the single largest drag on a weak 57,000-job national print, with accommodation and food services accounting for 54,600 of the losses. BLS attributed it to weaker than usual seasonal hiring.
The Backstory
The pessimism was real and it was recent. In March, FIFA released thousands of blocked hotel rooms back into host-city inventory, and the Greater Philadelphia Hotel Association alone cancelled around 2,000 of its 10,000 held reservations. A survey of more than 200 hotels across the 11 US host cities by the American Hotel and Lodging Association found nearly 80% reporting bookings below forecast, with some operators calling the tournament a non-event for their business.
CoStar and Tourism Economics kept cutting their forecast. In February they modeled a 1.7% national RevPAR lift for June and July. By April that was down to 1.2% in June and 1.5% in July. Full-year contribution fell from 0.6% to 0.4%.
Then the tournament started and the rate curve went vertical. Miami posted a 51.6% RevPAR increase in the week ending June 27 on a 51.1% ADR gain, with occupancy up 0.3 percentage points. Kansas City ran nearly 50% RevPAR growth in the semifinal window. Philadelphia cleared 74% on a weekend where its match landed on top of Fourth of July and America 250 events.
None of those gains came from selling more rooms. They came from selling the same rooms at a different price.
The Plan
The operator playbook that worked was narrow and it was not complicated: hold rate, do not chase occupancy, and accept that your base business is going to walk.
Hotels in host markets systematically displaced business travel to make room for tournament demand, then priced the replacement demand at a premium the displaced traveler would never have paid. CoStar noted explicitly that during the Fourth of July week, host-market occupancy finally rose 1.1 percentage points, and part of the reason was simply that there was less business travel available to displace that week.
That is not a growth strategy. It is a margin strategy executed against a fixed asset with a hard capacity ceiling. A hotel cannot build more rooms for a five-week event. The only lever it owns is price. So the entire industry pulled that lever at once, and the aggregate result looks like a boom in the revenue line and a contraction in the volume line.
Restaurants and bars had a genuinely different experience, which is why the anecdotes are so much sunnier than the spreadsheets. A bar has elastic capacity within a fixed footprint: more turns, more taps, more staff behind the counter on a given night. That is why a Philadelphia sports bar could run Super Bowl numbers daily for a month while the hotel three blocks away sold fewer room nights than last July.
The Business Model Angle
This is a textbook case of a demand shock that redistributes rather than creates, and the redistribution runs in two directions at once.
Geographically, it moved down-market. Philadelphia, Kansas City, Dallas and Houston picked up advance European flight bookings. Los Angeles, Miami and New York lost them. The second-tier host cities had spare capacity and a low baseline, so incremental demand showed up as pure gain. The gateway cities were already full of summer tourists, so tournament visitors mostly replaced visitors who would have come anyway. Victor Matheson, the sports economist at Holy Cross who has spent a career on this exact question, put it plainly: a tourist who would have gone to Denver went to Kansas City instead. For the national economy, that nets to roughly zero.
Structurally, it moved up the capital stack. The gains landed with whoever owned pricing power over a scarce, fixed asset. That means hotel owners, FIFA’s rights and hospitality business, and the resale marketplace taking a fee from both sides of every ticket trade. It did not mean labor. You cannot hire 185,000 people to sell a room you were already going to sell at a higher price.
We flagged this shape on the day the tournament opened: FIFA runs an asset-light rights platform that pushes operating cost onto hosts while keeping the central revenue, and the real story would be the gap between projected windfall and realized one. Five weeks later the gap has a number attached. FIFA’s headline projection was a $17 billion boost to US GDP. Even taken at face value, that is under 0.1% of a $30 trillion economy. The tournament was never going to move the macro. It was always going to move the margin, and it did.
The Risk
The obvious counterargument is that this analysis is premature and slightly unfair, and it deserves a real hearing.
Bank of America’s card data excludes foreign-issued cards entirely. The single largest category of genuinely new money, spending by international visitors, is invisible in the dataset everyone is quoting. The true non-local number is higher than 17.4% and nobody yet knows by how much. Full accounting will take months.
The June jobs number is also noisy. BLS framed it as weak seasonal hiring rather than outright layoffs, the household survey that month was strange in every direction, and April and May were both revised down by a combined 74,000. Reading a single month’s leisure and hospitality print as a verdict on the World Cup is a stretch, and the tournament ran through July 19, meaning most of the knockout-stage activity falls in a jobs report that has not been published yet.
And the substitution argument has a limit. Displacement logic says the money would have been spent somewhere regardless, but that assumes a fixed national spending pool. Lower-income households, per BofA, increased brick-and-mortar spending during the tournament while higher-income households eased off. That pattern looks less like substitution and more like activation, people going out who otherwise would have stayed in. Some share of this was new consumption, not moved consumption.
The honest position: hotels are a clean case of rate over rooms, and that is not seriously arguable. The broader economy is genuinely undetermined and will stay that way until the international spending data arrives.
Quick Questions
Did the World Cup boost the US economy? Marginally at best. FIFA projected $17 billion, which is under 0.1% of US GDP. Card spending rose 6.3% nationally in June, but the bank attributed much of that to lower gas prices and unrelated online promotions rather than the tournament.
Which host cities benefited most? Second-tier markets. Philadelphia, Kansas City, Dallas and Houston gained advance European flight bookings. Los Angeles, Miami and New York lost them. Cities with spare capacity converted tournament demand into net gain; already-full cities mostly swapped one visitor for another.
Did hotels actually fill up? No. Host-market occupancy was down 1.3 percentage points through the first 17 days and fell 3.1 points on non-match days. Revenue rose because rates rose roughly 21% to 26%, not because more rooms sold.
What about the 185,000 jobs FIFA promised? Leisure and hospitality employment fell by 61,000 in June, with accommodation and food services down 54,600. There is no evidence yet of tournament-driven hiring at any meaningful scale.
Who actually made money? Owners of fixed, scarce assets with pricing power: hotels, FIFA’s rights and hospitality business, ticket resale platforms, and individual bars and restaurants that could add turns without adding capacity.
The Business Model Analyst Take
The clearest lesson here has nothing to do with soccer, and it is one that catches operators in every industry.
When a demand spike hits a business with fixed capacity, revenue growth and demand growth stop being the same measurement. Hotels in host cities posted numbers that look like a boom and lived through something closer to a mix shift. If you were reading RevPAR alone, you saw a triumph. If you were reading room nights, you saw a decline. Both were true simultaneously, and the operators who understood which one they were looking at made better decisions than the ones who did not.
The second lesson is about who captures a windfall. It went to the parties holding scarce assets and pricing authority, and it bypassed labor almost entirely. That is the default outcome of any capacity-constrained demand event, and it is worth internalizing before the next one, because a 25% revenue gain that comes entirely from rate is a fundamentally different business result than a 25% gain that comes from volume. The first one ends the day the event ends. The second one sometimes leaves you with customers.
Matheson gave the best one-line summary anyone will produce on this tournament, and it holds up against every dataset we checked. The World Cup made the country happy. There is not much evidence it made the country rich.
Reporting from The Wall Street Journal, with data from CoStar, the Bank of America Institute, the US Bureau of Labor Statistics, Cirium, and the American Hotel and Lodging Association.