
Wingstop SWOT analysis in one line: Wingstop runs one of the most profitable franchise machines in fast food, and in 2025 it posted its first same-store sales decline in 22 years while opening a record 493 restaurants.
What is a Wingstop SWOT analysis? A SWOT analysis of Wingstop Inc. (NASDAQ: WING) maps the internal strengths and weaknesses of the wing chain against the external opportunities and threats in its market. Wingstop operates 3,153 restaurants worldwide as of March 28, 2026, roughly 98% of them owned by franchisees the company calls brand partners.
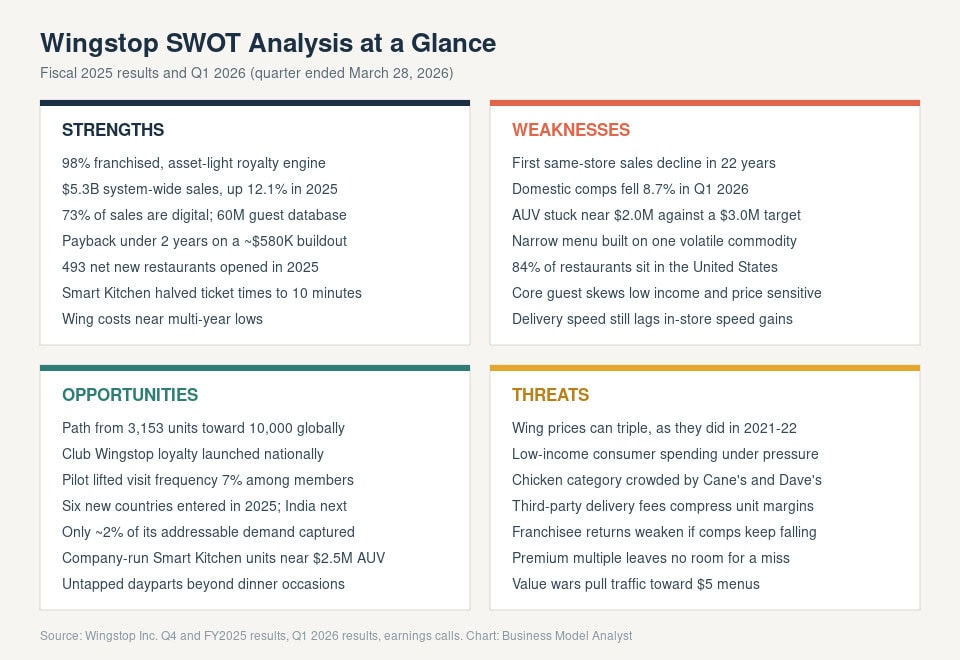
- Core strength: An asset-light franchise model that generated $5.3 billion in system-wide sales on just $696.9 million of company revenue in fiscal 2025.
- Core weakness: Domestic same-store sales fell 3.3% in 2025 and 8.7% in the first quarter of 2026.
- Core opportunity: A path from 3,153 restaurants toward a stated ambition of more than 10,000 globally, plus the national rollout of Club Wingstop.
- Core threat: Wholesale wing prices sit near multi-year lows, and the only direction they have travelled from here before is straight up.
Wingstop spent two decades as the stock market’s favorite restaurant story. Franchisees earned back their buildout in under two years. Comparable sales climbed for 21 straight years. Then the streak broke.
In fiscal 2025 the chain reported a 3.3% drop in domestic same-store sales, the first annual decline since 2003. The first quarter of 2026 came in worse at negative 8.7%. Meanwhile the company grew system-wide sales 12.1%, opened 493 restaurants, entered six new countries, and lifted adjusted EBITDA 15.2%. Two stories are running at once, and the SWOT below separates them.
Wingstop Company Overview
| Attribute | Detail |
|---|---|
| Company | Wingstop Inc. |
| Ticker | NASDAQ: WING |
| Founded | 1994, Garland, Texas |
| Headquarters | Dallas, Texas |
| CEO | Michael Skipworth |
| CFO | Alex Kaleida |
| Restaurants | 3,153 system-wide (March 28, 2026) |
| Ownership split | 2,596 US franchised, 57 US company-owned, 500 international |
| Fiscal 2025 revenue | $696.9 million |
| Fiscal 2025 system-wide sales | $5.3 billion |
| Fiscal 2025 adjusted EBITDA | $244.2 million |
| Digital sales mix | 72.5% of system-wide sales (Q1 2026) |
| Domestic AUV | Approximately $2.0 million |
Franchisees pay a 6% royalty on gross sales plus a national advertising fund contribution that Wingstop raised to 5.3% in 2024. That combination, applied across $5.3 billion of system sales, is the entire engine. Wingstop sells almost no food. It sells the right to sell food, and it collects a slice of every order.
Strengths
| Strength | The evidence |
|---|---|
| Asset-light franchise model | 98% of restaurants owned by brand partners; company revenue is mostly royalties and ad fund fees |
| Franchisee returns | Roughly $580,000 buildout, payback under two years, cash-on-cash returns above 50% |
| Development pipeline | 493 net new restaurants in 2025, 97 more in Q1 2026, unit growth of 17% |
| Digital dominance | 72.5% of system-wide sales come through digital channels; 60 million guests in the MyWingstop database |
| Operational rebuild | Smart Kitchen deployed across all 2,586 domestic restaurants in 10 months, cutting ticket times from about 20 minutes to 10 |
| Commodity position | Wholesale wing costs near multi-year lows, protecting brand partner margins |
The royalty engine keeps running while the stores struggle
Look at the divergence in the chart below. Domestic same-store sales collapsed, and system-wide sales still grew 12.1% in 2025 and 5.9% in Q1 2026. Wingstop grows by adding restaurants, not by squeezing more out of the ones it has. As long as brand partners keep signing development agreements, the royalty line keeps climbing even when guest traffic falls.
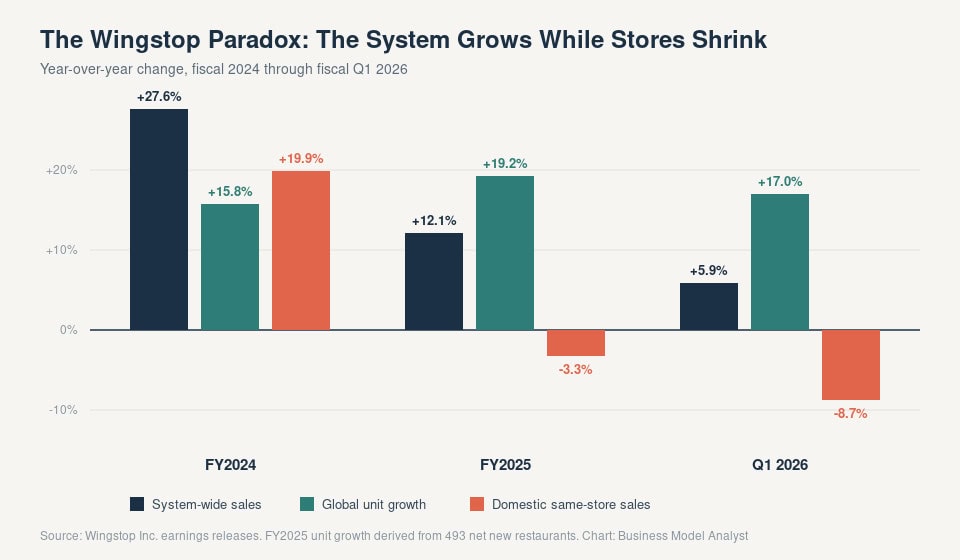
That is the structural advantage of a 98% franchised model. Wingstop carries almost no restaurant-level cost, so a bad quarter at store level lands on brand partners first and on the franchisor second. Adjusted EBITDA rose 9.9% in the same quarter that comps fell 8.7%. Few restaurant companies can absorb a traffic shock that cleanly.
The unit economics still recruit operators
A Wingstop costs roughly $580,000 to build and pays that back in under two years. Cash-on-cash returns run above 50%. Those numbers explain why the development pipeline sits at a record level despite the comp decline, and why brand partners are opening restaurants at a 17% annual clip in the middle of a consumer slowdown. CFO Alex Kaleida has been explicit that protecting brand partner profitability comes before chasing traffic with discounts.
Digital is the moat nobody talks about
Nearly three quarters of Wingstop’s system sales arrive digitally, a mix almost no scaled restaurant chain matches. The MyWingstop database holds 60 million guest profiles. Wingstop knows what you ordered, when, and at what price, which is the raw material for the loyalty program it launched nationally at the end of the second quarter of 2026.
Weaknesses
| Weakness | The evidence |
|---|---|
| Broken comp streak | Domestic same-store sales fell 3.3% in 2025, the first decline in 22 years |
| Accelerating decline | Q4 2025 comps fell 5.8%; Q1 2026 fell 8.7% |
| Stalled AUV | Domestic average unit volume flat near $2.0 million against a $3.0 million target |
| Menu concentration | Revenue depends on one protein cut with a violent price history |
| Geographic concentration | 2,653 of 3,153 restaurants sit in the United States |
| Customer income skew | Core guests trade down first when fuel and rent rise |
| Delivery gap | In-store speed improved 15%, delivery times did not follow |
The comp decline is not entirely weather
Management attributed roughly 4 percentage points of the Q1 2026 decline to winter storms that closed more than 700 restaurants and to a spike in fuel prices. Take management at its word and the underlying comp still landed near negative 5%, in line with Q4. Skipworth called the quarter disappointing. The problem predates the storms.
Cannibalization hides inside the unit growth
Wingstop added 493 restaurants in 2025 into a domestic base of about 2,500. New units open inside trade areas the existing units already serve, and those transferred orders come out of the comp base. Nobody at Wingstop breaks out the cannibalization figure, and the company would rather you read the comp decline as a macro story. Some portion of it is a self-inflicted wound from the fastest development pace in the brand’s history.
One protein, one country
Wingstop sells wings. Strip away fries and sides and the menu rests on a commodity whose wholesale price ran from about $1.00 per pound to $3.24 per pound between 2020 and January 2022. Add the geographic picture, with 84% of restaurants in the United States, and a single market’s consumer slump becomes the whole company’s problem. Compare that to Chick-fil-A, which anchors on a chicken breast sandwich and a far more diversified daypart mix.
Opportunities
| Opportunity | The size of the prize |
|---|---|
| Unit expansion | From 3,153 restaurants toward a stated target of more than 10,000 globally |
| AUV expansion | From $2.0 million to a $3.0 million target, with company-run Smart Kitchen units already near $2.5 million |
| Club Wingstop loyalty | Pilot enrolled nearly 50% of active guests and lifted visit frequency 7% |
| International growth | Six new countries entered in 2025; India planned for 2026 |
| Share of demand | Management estimates it captures about 2% of its addressable demand against a 20% goal |
| New dayparts | Faster service times open lunch occasions the brand never competed for |
The AUV ladder is the whole investment case
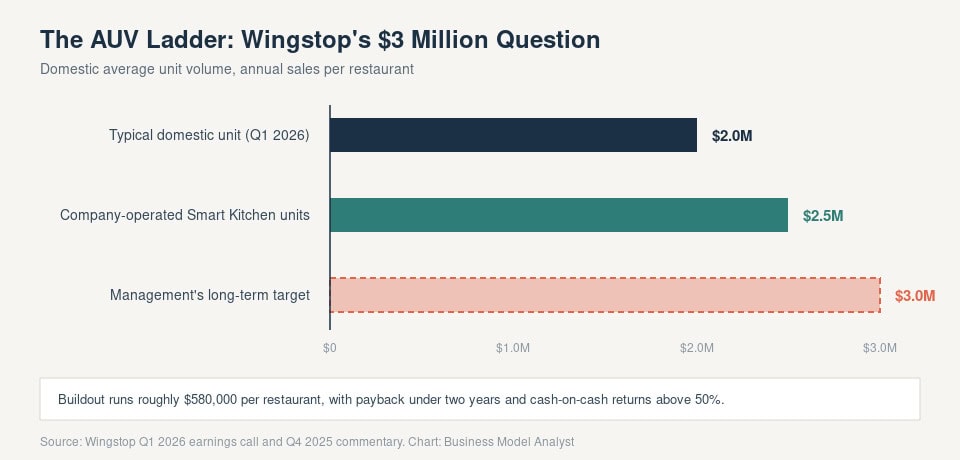
Company-operated restaurants running Smart Kitchen posted average unit volumes near $2.5 million and outperformed the franchised base. That is the proof point Wingstop leans on when it defends the $3 million target. If the tech genuinely lifts volumes rather than reflecting better-sited corporate stores, every existing restaurant has 50% of upside sitting on the table with no additional capital.
Texas, where Smart Kitchen has the longest tenure, outperformed the rest of the country in Q1 2026. California, under heavier macro pressure, did not move. Skeptics will note that Texas outperforming California in a consumer downturn has a simpler explanation than kitchen software.
Club Wingstop arrives at the right moment
The loyalty pilot enrolled nearly half of active guests in test markets and lifted frequency 7% among enrollees. More than 30% of new guests signed up. Wingstop designed the program around merchandise, content, and access rather than discounts, which protects the brand partner P&L. Kaleida expects it to be margin accretive over time. A frequency-driven program is the correct answer to a traffic problem, and the timing lines up with the comp trough.
International is the underweighted story
Wingstop entered six countries in 2025 and opened more than 100 restaurants outside the United States. International units generate higher average volumes than domestic ones, helped by experiential House of Flavors locations. India lands in 2026. With 500 international restaurants against 2,653 domestic, the global runway is barely touched, and it dilutes the single-market risk that defines the weakness column.
Threats
| Threat | Why it bites |
|---|---|
| Wing price reversal | Wholesale wings hit $3.24 per pound in January 2022; they sit near $1.05 today |
| Consumer pressure | Fuel and grocery inflation hit Wingstop’s core low-income guest first |
| Chicken competition | Raising Cane’s, Dave’s Hot Chicken, Popeyes, and Buffalo Wild Wings all chase the same occasion |
| Delivery economics | Third-party platforms take a cut of the majority of orders |
| Value wars | Rivals push $5 menus while Wingstop refuses to build a cheap value tier |
| Valuation risk | Shares trade near a 36x forward earnings multiple against a hospitality average around 18x |
| Franchisee fatigue | Sustained comp declines eventually slow the development pipeline |
The commodity cushion is temporary
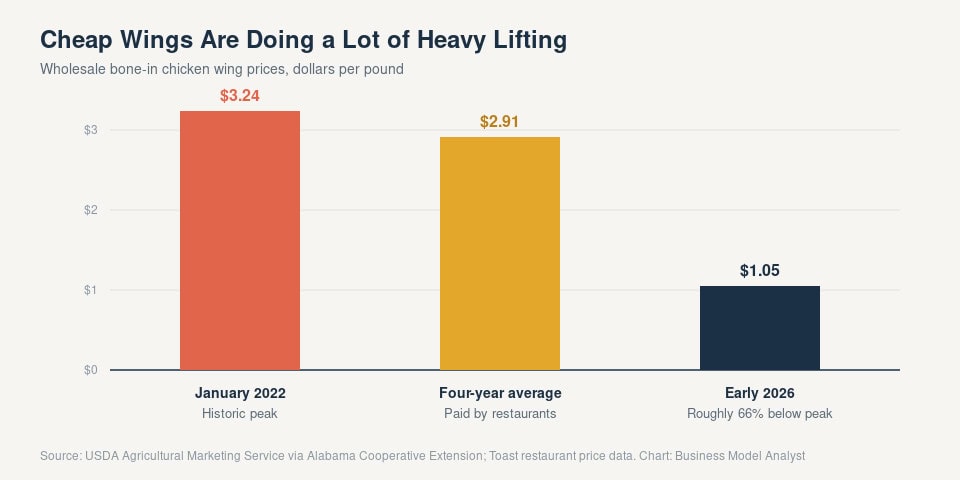
Cheap wings are quietly propping up brand partner margins through the comp decline. Wingstop reported improving franchisee margins in Q1 2026 despite the sales drop, and low commodity costs explain much of that. Wing prices are mean-reverting and the mean sits far above today’s level. A return toward $3 per pound while comps are still negative would hit brand partner cash flow from both directions at once, and the development pipeline is the first thing that breaks.
Wingstop will not fight the value war
Kaleida told analysts that training a guest to visit for a $3 item is not who Wingstop is. That discipline protects the model and cedes the value-seeking customer to competitors running aggressive bundles. The bet is that group occasions and flavor loyalty hold up better than price-led traffic. In a prolonged consumer downturn, that bet gets tested every quarter.
The market has already repriced the story
Shares traded near $173 in mid-2026 against a 52-week high of $388.14. Short interest sits near 19% of the float. The stock still carries a forward multiple around double the hospitality average, which means the recovery is priced as a matter of when, not if. Any quarter that pushes the recovery further out gets punished hard.
Wingstop by the Numbers
| Metric | Fiscal 2024 | Fiscal 2025 | Q1 2026 |
|---|---|---|---|
| System-wide sales | $4.8 billion | $5.3 billion (+12.1%) | $1.4 billion (+5.9%) |
| Total revenue | $625.8 million | $696.9 million (+11.4%) | $183.7 million (+7.4%) |
| Domestic same-store sales | +19.9% | -3.3% | -8.7% |
| Net income | $108.7 million | $174.3 million | $29.9 million |
| Adjusted EBITDA | $212.0 million | $244.2 million (+15.2%) | $65.4 million (+9.9%) |
| Net new restaurants | 349 | 493 | 97 |
| Digital sales mix | 70.3% (Q4) | 73.2% (Q4) | 72.5% |
One number in that table deserves an asterisk. Fiscal 2025 net income jumped 60.3%, which looks like a company thriving. It is not operating income. Wingstop booked a $97.2 million gain on the sale of its stake in Lemon Pepper Holdings, its former UK master franchisee, in the first quarter of 2025. Adjusted net income, which strips that out, rose 3.8%. Most SWOT write-ups on the web quote the 60.3% and move on.
How Wingstop Compares
| Brand | Model | Approximate scale | Positioning |
|---|---|---|---|
| Wingstop | ~98% franchised | 3,153 restaurants, $5.3B system sales | Wings, flavors, digital and carryout |
| Chick-fil-A | Operator model, single unit | ~3,000 US restaurants | Chicken sandwich, service, closed Sundays |
| Raising Cane’s | Company-owned | Growing US footprint | Chicken fingers, one core combo |
| Buffalo Wild Wings | Franchised and company | Casual dining plus BWW Go | Wings with sports bar occasion |
| Popeyes | Franchised | Global QSR scale | Chicken sandwich and bone-in |
Wingstop’s differentiation is not the wing. Anyone can fry a wing. The differentiation is a small-footprint, low-labor kitchen with no dining room to speak of, feeding a digital order pipe that fills group occasions. That is a franchise business model tuned for capital efficiency rather than for square footage.
Frequently Asked Questions
Is Wingstop in trouble in 2026? Wingstop faces a traffic problem, not a solvency problem. Domestic same-store sales fell 8.7% in Q1 2026, yet system-wide sales grew 5.9%, adjusted EBITDA rose 9.9%, and the company opened 97 restaurants. The franchisor model absorbs weak store traffic better than a company-operated chain would.
Why are Wingstop’s same-store sales falling? Management points to pressure on lower-income consumers, higher fuel prices, and winter storms that closed more than 700 restaurants in January 2026. Aggressive new-unit development inside existing trade areas also transfers sales away from the comp base.
How profitable is a Wingstop franchise? Brand partners invest roughly $580,000 to open a restaurant, generate about $2.0 million in average annual sales, and report cash-on-cash returns above 50% with payback in under two years. They pay a 6% royalty plus a 5.3% advertising fund contribution.
What is Wingstop’s biggest weakness? Concentration. The chain depends on one protein, one country for 84% of its restaurants, and one price-sensitive customer segment. Any shock to wing costs or to low-income spending hits the whole system at once.
What is Club Wingstop? Club Wingstop is the company’s first national loyalty program, rolled out at the end of the second quarter of 2026 after a 2025 pilot. Nearly half of active guests in test markets enrolled, and enrolled guests visited 7% more often. The rewards emphasize merchandise and experiences rather than discounts.
How many Wingstop restaurants are there? Wingstop operated 3,153 restaurants as of March 28, 2026, including 2,653 in the United States and 500 international locations. Management has stated an ambition to exceed 10,000 restaurants globally.
The Business Model Analyst Take
Wingstop is running two businesses, and only one of them is broken.
The franchisor business works. Royalties on $5.3 billion of system sales, a record development pipeline, EBITDA growing double digits through a traffic recession, and franchisee returns strong enough to keep brand partners writing checks. Nothing in the Q1 2026 numbers threatens that structure.
The restaurant business is under real strain. Eight straight quarters of deterioration in a chain that had not seen a down year since 2003 is a trend, and blaming January weather does not survive contact with the Q4 2025 print. The AUV has been flat at $2 million while management talks about $3 million, and that gap is where the entire growth story lives.
The tension to watch is the one between those two businesses. Wingstop can keep growing system sales by opening restaurants into a shrinking comp base for a while, and every new unit opened into a soft trade area drags the average down further. That works until brand partner cash flow cracks. The commodity cushion of $1 wings is holding franchisee margins together right now, and the moment wings normalize toward $2.50 with comps still negative, the development pipeline slows and the royalty engine loses its only growth lever.
Club Wingstop and Smart Kitchen are the right answers. Frequency and speed beat discounting for a brand that refuses to compete on price. Whether they land fast enough to stabilize comps before wing prices turn is the question, and Wingstop’s Q2 2026 report on July 29 is the next hard data point.