
IBM’s worst day ever wasn’t about one soft quarter. It was the market repricing whether a 115-year-old company can lead the AI era, or just survive it.
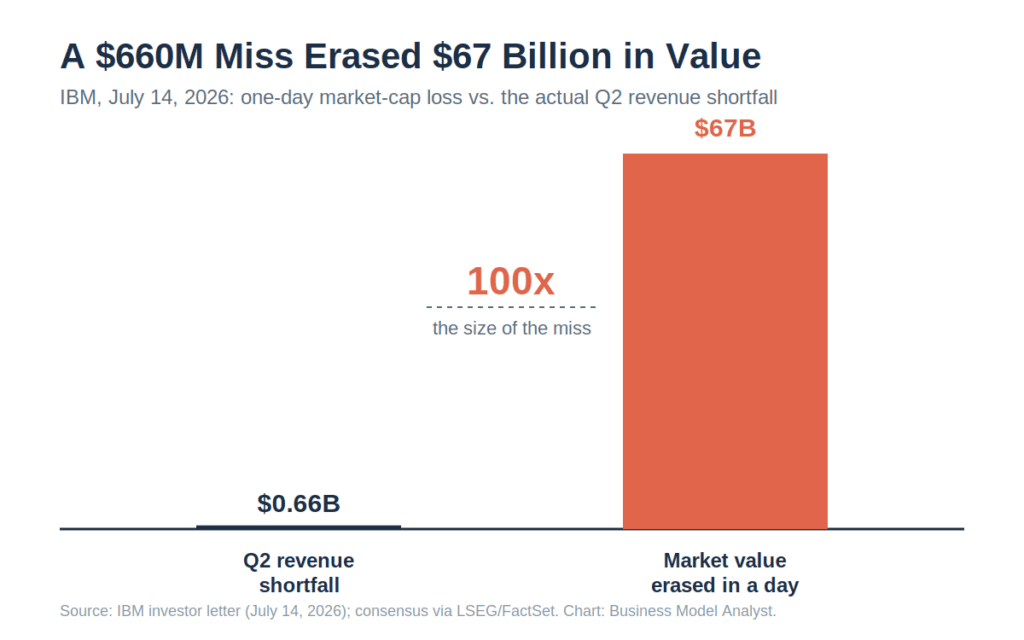
On July 14, 2026, IBM warned that its Q2 revenue would land near $17.2 billion, about $660 million short of Wall Street’s estimate. The stock fell 25%, erasing roughly $67 billion in value. That is close to 100 times the size of the miss. The gap between those two numbers is the whole story.
Here is the part most coverage skipped: a $660 million shortfall does not wipe out $67 billion in market cap because investors are angry about one quarter. It happens because a single data point forces them to question a thesis they had been paying a premium for. IBM’s crash was not a reaction to the number. It was a reaction to what the number implied.
What Happened
Before markets opened on Tuesday, IBM did something it almost never does. It sent shareholders an unscheduled letter admitting the quarter had gone badly, a full eight days before its scheduled July 22 earnings release.
“This quarter we faltered,” CEO Arvind Krishna wrote. “We did not adapt and move quickly enough, and numerous large deals failed to close on the timelines we expected, driving the majority of our shortfall.”
The market’s verdict was brutal. IBM closed down 25.21% at $217.05, its steepest single-day drop on record, worse than the 23.7% it lost on Black Monday in 1987. Records tracking the stock go back to 1968, and IBM has traded on the NYSE since 1916. The selloff spread: Salesforce fell about 4%, Microsoft nearly 3%, and the broad software ETF dropped 2%. When a blue chip this old moves this hard, it drags a sector with it.
The Backstory
To see why the reaction was so violent, you have to understand what IBM had promised. Under Krishna, IBM sold investors a clean story: it had transformed from a slow hardware company into a software-and-AI growth engine, anchored by its $34 billion Red Hat acquisition. And the story was working. Just one quarter earlier, in Q1 2026, revenue grew about 9% year over year and beat expectations.
So Q2 was not just a miss. It was a reversal of the exact narrative that justified IBM’s valuation. Growth of roughly 1% where double digits were expected does not read as a bad quarter. It reads as a broken premise.
The Plan
Krishna’s letter pinned the shortfall on three things: large deals slipping past the quarter’s end, clients distracted by industry-wide cybersecurity concerns, and a rollout of the new z17 mainframe that ran into delays and rising chip costs.
But the deeper cause sits upstream, in the memory market. A global shortage of memory chips, driven by AI data centers soaking up supply, has pushed hardware prices up since late 2025. Facing higher prices ahead, IBM’s enterprise customers rushed to lock in servers, storage, and memory in the quarter’s final weeks to secure allocation before costs rose further. That spending had to come from somewhere. It came out of the budget lines earmarked for IBM’s software and services.
The Business Model Angle
This is where IBM’s crash stops being an AI story and becomes a business-model story.
IBM’s profit is dangerously concentrated. Software makes up only about 45% of revenue but delivers close to two-thirds of profit, according to J.P. Morgan. The reason is margin: in Q1 2026, IBM’s software segment ran an 82.8% gross margin, versus 56.9% for infrastructure and 27.5% for consulting. Software is not just a business line at IBM. It is the profit engine, and everything else is comparatively thin.
Now layer in how IBM actually sells. Unlike cloud providers that rent computing capacity by the minute, IBM depends on large enterprise accounts signing big, discrete deals on upgrade cycles they fully control. Those customers can defer. When budgets tighten, a mainframe upgrade or a software renewal is exactly the kind of line item a CFO pushes to next quarter.
Put those two facts together and the fragility is obvious. IBM’s most profitable segment rides on the most deferrable kind of revenue, sold to a concentrated base of customers who can say “not this quarter” whenever they want. The memory shortage did not attack IBM directly. It just tightened its customers’ budgets, and IBM’s high-margin software was the first thing they postponed. The disruption arrived through its clients’ spreadsheets, not through a competitor’s product. You can see the full shape of this model in IBM’s business model, where software and consulting drive the bulk of revenue.
There is a neat symmetry worth noting. The same memory shortage crushing IBM is minting fortunes for the chipmakers on the other side of it. We covered that supply side in why Wall Street calls Micron the next Nvidia. IBM is the demand-side casualty of the exact shortage those companies are cashing in on. In any capex shock, value does not vanish. It moves. It is moving toward whoever controls the scarce input, and away from whoever depends on customers who can wait.
The Risk
The real debate now is cyclical versus structural, and IBM’s future hinges on which one this is.
The bull case is timing. Vice Chairman Gary Cohn suggested the spending shift may be temporary, and that deferred deals could simply close in Q3 once memory supply normalizes. If so, this was a scheduling problem dressed up as a crisis, and DataRobot CEO Debanjan Saha may be right that “the punishment doesn’t fit the crime.”
The bear case is structural, and it is the one that should worry IBM. If AI infrastructure is permanently claiming a larger slice of enterprise IT budgets, then the money flowing into servers and memory is not coming back to IBM’s software and services. It has been reallocated for good. Under that reading, IBM does not have a bad quarter. It has a shrinking share of a budget it used to own.
The market clearly leaned bearish. HSBC cut its rating to “Reduce,” and the drop pushed IBM’s market cap below $200 billion, leaving a company that once towered over the industry now dwarfed by Broadcom near $1.8 trillion and AMD around $800 billion. Wall Street is already discussing whether an activist investor shows up, or whether IBM gets pressured to break itself apart.
Quick Questions
Why did IBM stock drop 25% over a small miss? Because the $660 million revenue shortfall was tiny, but what it signaled was not. IBM’s valuation rested on a story of steady software-led growth. A quarter of roughly 1% growth, right after 9% the quarter before, broke that story and forced investors to reprice IBM’s whole future.
What caused IBM’s Q2 2026 shortfall? Large deals slipped past the quarter’s close, a memory chip shortage pushed clients to front-load hardware spending instead of buying software, the new z17 mainframe rollout was delayed, and cybersecurity concerns distracted enterprise buyers.
Is IBM’s problem temporary or permanent? That is the open question. IBM says deferred deals may close later. Skeptics argue AI infrastructure is permanently absorbing a larger share of enterprise IT budgets at the expense of IBM’s high-margin software. The July 22 earnings call should offer the first real evidence either way.
When does IBM report full Q2 results? July 22, 2026. Investors will be watching whether the lost revenue reappears in Q3 guidance or whether the weakness looks like a lasting demand shift.
The Business Model Analyst Take
IBM’s crash is a lesson in where profit really lives, and how exposed it can be. The company did nothing dishonest here. Krishna’s early warning was arguably the most transparent move a CEO could make. But transparency does not fix the underlying design flaw, and the market saw the flaw clearly.
The uncomfortable truth is that IBM built a high-margin software business on top of a low-agility sales model. The margins say “modern software company.” The revenue mechanics say “legacy enterprise vendor waiting on big accounts to sign.” When those two things point in opposite directions, the market eventually prices the weaker one. For founders, the takeaway is sharper than any headline about AI: it is not enough to have great margins. You have to ask how deferrable your revenue is, and how concentrated your customers are. IBM just showed what happens when the answer to both is “very.” The AI era did not break IBM’s model. It exposed a fragility that was there all along.
Reporting based on IBM’s July 14, 2026 investor letter, The Wall Street Journal, CNBC, Forbes, and consensus estimates via LSEG and FactSet.