
Modern financial platforms have incorporated a smooth UX design and mobile-first investing habits that make it natural for users to visit these apps often. These tools have now become lifestyle products that people enjoy throughout their day and not just to perform tasks such as paying bills.
The Evolution of the Banking Interface
Traditional banking has lost many of the advantages it held, slowly, over the last two decades. For instance, consumers can access interest rates that are the same or even higher with modern fintech platforms than with older banks. The evolution of fintech from mere banking tools to lifestyle apps is due to the increased demand for solutions that offer flexibility, aesthetics, and intuitive visualisations.
Many traditional banks focus mainly on utility, which means users log in exclusively to perform tasks like checking balances or paying bills, with little to nothing more besides.
However, modern fintech apps have discarded the spreadsheet aesthetic in favour of warm colour palettes and social features that help users feel in control. Bill payments, investing, tax reporting, or simple analysis are faster and better with apps designed for the modern user.
Why Modern Financial Platforms Have to Move Beyond Utility
There are several reasons why financial platforms have grown from mere utility to all-in-one lifestyle companions. The primary reasons are functionality, market share, consumer expectations, and the merging of finance and commerce. The fintech goal is simple: improve user experience for the majority of consumers while growing their revenue/profit.
Core Banking Availability
Banking infrastructure is now available to any tech company that meets regulatory requirements. Today, any fintech can easily offer cards, checking accounts, local and cross-border payments, and more through APIs. This results in a level playing field where the basic banking feature is democratised and identical.
As a result, new fintech companies that want a piece of the market share must go beyond simply offering banking services. For example, Wise built its niche by focusing on cheap, fast international transfers using real exchange rates, capturing the global expat and freelancer market that traditional banks were overcharging. Klarna took the simple concept of instalment payments and turned it into a shopping discovery platform, with curated stores, price drop alerts, and wish lists that appealed to younger online shoppers.
Mobile-First Investing
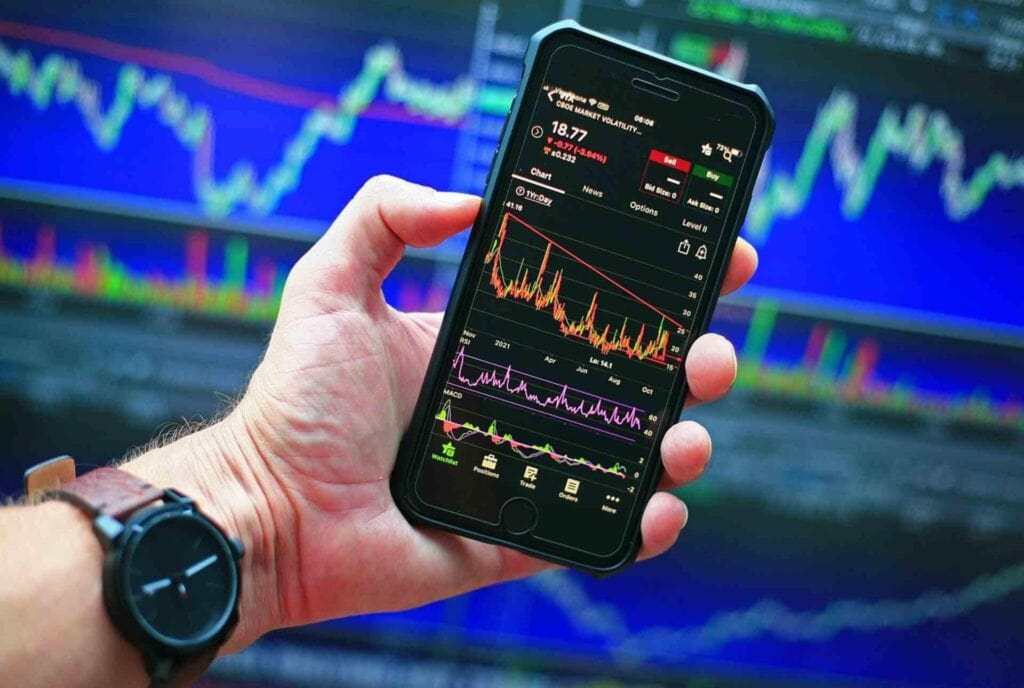
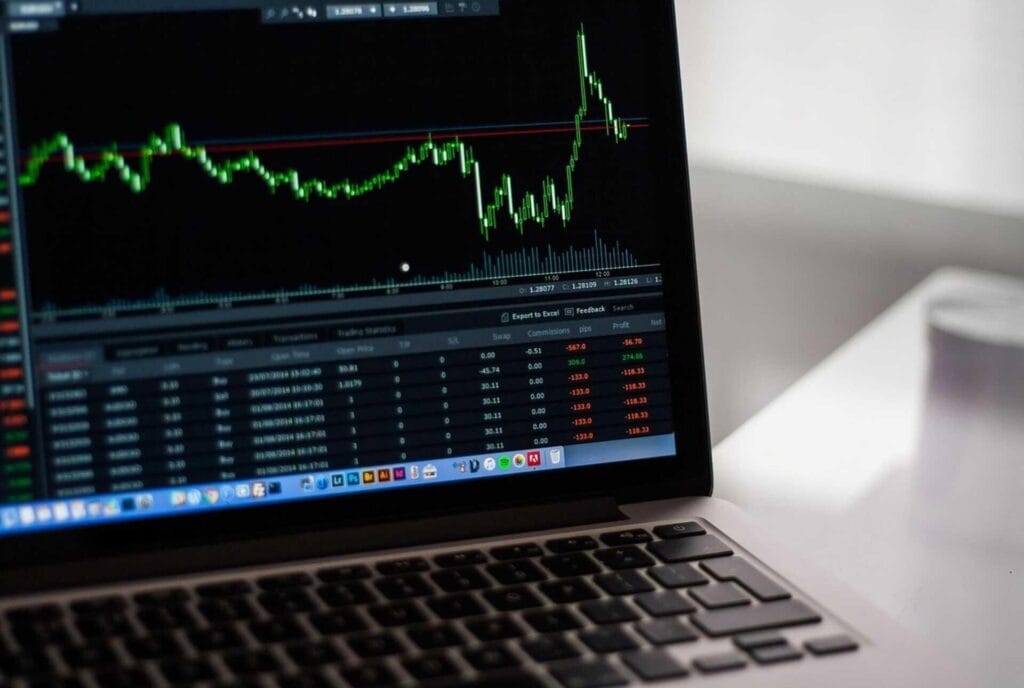
The way people invest has changed alongside the way they bank. Investing used to be reserved for financial professionals who understood the market and had access to the right tools. Today, most people know how to trade, and they can do it right from their phone. Dedicated trading platforms such as OANDA have made this possible by building mobile apps that are simple to use, with clean interfaces and educational resources that make it easier for newcomers to learn the basics. Users can open positions, monitor their portfolios, and read market analysis without leaving the app. Many now check their positions daily and treat investing as part of their normal routine rather than a separate, intimidating activity. Some have moved further into advanced strategies such as CFD trading directly from their phones, which would have required a desktop terminal and a broker on the phone just a few years ago.
The Fight for Daily Active Users (DAU)
Fintech revolves around consumers, and that’s why every financial provider fights to increase their customer numbers and get more of the market share. The DAU is a key performance indicator that fintech firms use to measure revenue generation and popularity. But the competition is stiff; fintechs must be creative to attract and retain consumers.
This is why modern platforms are going out of their way to gather feedback and roll out features that help consumers every day.
Hyper-Personalisation and Branding
Fintech apps have rebranded as lifestyle champions. They have made a distinct image from traditional banks. Modern fintechs tell consumers who they are and give them an identity in the digital world. They do this by leveraging advanced AI and machine learning to predict user needs and nudge them into subscriptions and other actions.
With that inroad, fintechs now play a major role in the lives of billions, especially in delivering financial education and incentivising discipline. They celebrate milestones and login streaks and create communities for their users. All of these help consumers to make better financial decisions.
Improved Trust in Modern FinTech
Over the years, the fintech industry has largely overcome the challenge of gaining consumers’ trust. But modern consumers have now moved from reluctance to transact billions on digital wallets and investment platforms. They trust these fintech firms because they comply with regulations such as the FCA’s, and prioritise safety over trends.
As trust increases, more consumers adopt fintech to perform tasks. So, for instance, a consumer may initially download an app for higher deposit rates, but after months of use, may then trust the app enough to actively trade markets. In response, the fintech platform rolls out additional features to keep users committed.
Final thoughts
Modern financial platforms have brought lasting changes to how individuals and organisations engage in financial activities. The benefits far outweigh any challenge and present opportunities for improvement. Access to modern fintech today means performing many functions from a single, convenient place. The best part is that there is more to come. Right now, some fintech apps, like digital wallets and payments, run on wearables, and in the future, active trading may be possible on smart glasses.