
The New York Times this week called the coming wave of AI computing power an “inescapable deluge,” with hundreds of data centers about to switch on from the American Midwest to the Persian Gulf. Buried a few paragraphs into that story is the line that actually matters for most households: the build-out is stoking protests over how data centers “raise electricity prices,” and it is shaping up as a defining issue for November’s midterms.
That is not a side effect. It is the business model. For the first time in a century, a single class of customer is big enough, concentrated enough, and rich enough to reset the price of electricity for everyone else on the grid. And through a quiet quirk of how regulated utilities work, a chunk of AI’s single largest operating cost is being billed to people who will never run a training job.
Here is how the cheapest input in the AI economy ended up on your power bill.
What Happened
The clearest evidence is in the capacity market run by PJM Interconnection, the grid operator that serves about 67 million people across 13 states and Washington, D.C. A capacity auction is a forward market: generators get paid today to promise power will be there in a future year. When demand forecasts spike, the clearing price spikes, and every customer in the region pays it.
The price has gone vertical. It cleared at $28.92 per megawatt-day for the 2024/25 delivery year, then jumped to a record $269.92, then $329.17, and in the December 2025 auction it hit $333.44, the maximum price federal regulators allow. That is the third record-high auction in a row, and even at the ceiling PJM still came up roughly 6,600 megawatts short of its own reliability target.
PJM’s independent market monitor, Monitoring Analytics, put a number on the cause. Data centers accounted for about 40 percent of the charges in that latest $16.4 billion auction. The Institute for Energy Economics and Financial Analysis estimated data centers drove 63 percent of the price increase in the prior auction, translating to roughly $9.3 billion in extra costs recovered from customers in a single year.
Those costs are already showing up. Pepco residential customers in Washington, D.C. saw bills rise about $21 a month starting in June 2025. AEP Ohio customers absorbed roughly a 10 to 15 percent increase over the same capacity year, with commercial customers facing as much as 29 percent.
The Numbers That Matter
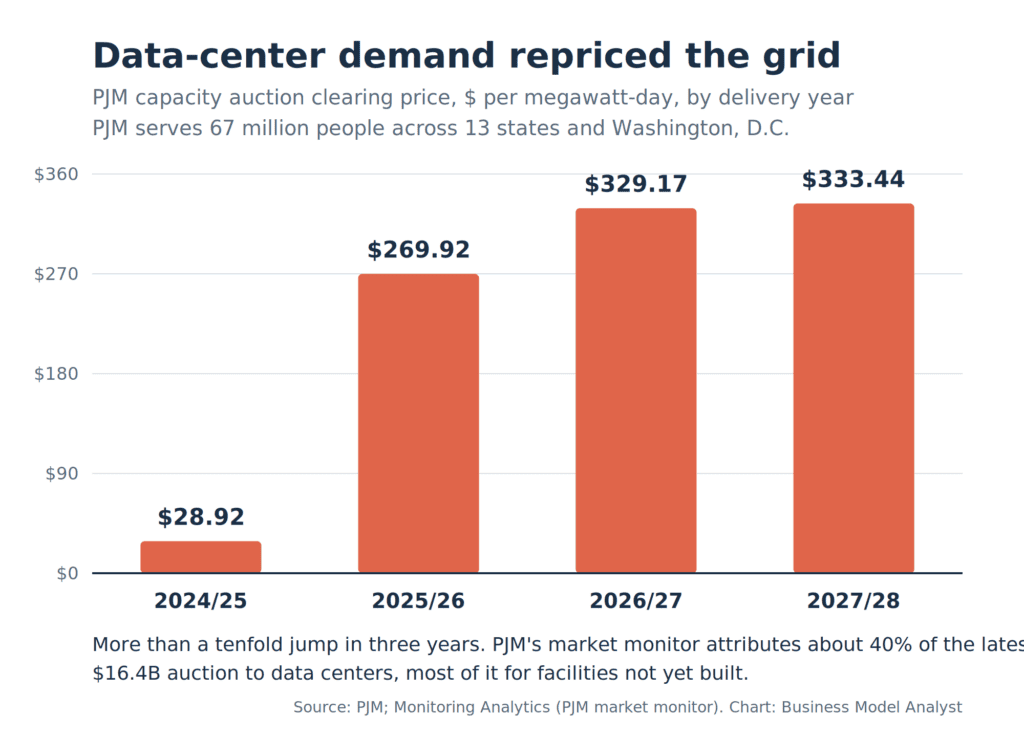
PJM’s capacity price rose more than tenfold in three years. The grid operator’s own market monitor attributes roughly 40 percent of the latest $16.4 billion auction to data centers, and most of that to facilities that have not been built yet.
The Real Story
The mechanism is older and duller than the AI hype around it. When a giant new customer wants power, the local utility builds transmission lines, substations, and generation to serve it. Then it recovers that cost across its entire customer base, because socializing infrastructure cost is simply how the regulated utility model has always worked. Ari Peskoe, who directs the Electricity Law Initiative at Harvard Law School, has made the point bluntly: utilities build, and “we all pay for it.”
Two features turn that ordinary mechanism into a wealth transfer. First, data centers can outbid almost anyone for power. Electricity is only about 20 percent of a data center’s total cost base, according to McKinsey, and these are among the most profitable facilities ever built, so a hyperscaler’s willingness to pay for firm power dwarfs a household’s. Second, residential ratepayers are captive. They cannot shop for a different grid. So when data-center demand pushes the capacity price to its cap, the AI operator shrugs and a retiree in Ohio does not.
The “cheap electricity” that makes a location attractive for a data center is therefore not entirely cheap. Part of the discount is a cross-subsidy paid by the people already on the wires. For years that was invisible. It is not anymore.
The Escape Hatch Nobody Priced In
Here is the twist that makes this a genuine business-model story and not just a grievance. The moment regulators try to force data centers to pay their own way, the biggest operators can simply leave the shared grid.
The Times noted that Elon Musk’s xAI loaded its Memphis facility with its own natural gas turbines. That is the template. In Ohio, a 2025 law cleared the way for on-site generation, and AEP Ohio and Amazon are now building a 73-megawatt Bloom Energy fuel-cell array in Hilliard, positioned as the largest such installation in North America. This is the “bring your own power” model, and it is spreading.
Behind-the-meter generation looks like a win for ratepayers, because a data center that makes its own power stops leaning on the shared grid. But it hollows out the cost-sharing base and dodges the very cost-allocation rules regulators are writing, while concentrating new pollution next to whichever community hosts the turbines. The same maneuver that shields ratepayers also lets the largest players opt out of the social contract entirely.
What Nobody Else Is Reporting
The sharpest number in this whole story is one the mainstream coverage tends to bury. Of the roughly $6.5 billion in data-center-related charges in that latest PJM auction, the market monitor found that about $6.2 billion came from data centers that have not been built yet. In other words, ratepayers are pre-paying, today, for capacity reserved to serve speculative facilities that may never come online.
That is not a rounding error. It is the majority of the data-center cost, and it rests on demand forecasts that have a poor track record. The energy research group RMI has documented how utilities routinely over-forecast large-load demand and build plants for load that never materializes. AEP Ohio itself, after new rules forced discipline, cut its projected data-center demand from a headline 30,000 megawatts to about 5,700. Critics argued the 30,000 figure was always a speculative media number rather than a real planning forecast. Either way, the gap tells you how soft these numbers are, and households are being charged against them in advance.
The Counterargument
The strongest case against the “hidden tax” framing has three parts.
First, the regulatory system is already correcting. Ohio’s Public Utilities Commission approved a data-center tariff in July 2025 that forces large centers to pay for at least 85 percent of the capacity they reserve for up to 12 years, whether they use it or not. It drew support from the state consumer counsel, commission staff, and even Walmart, and it is being copied in Michigan, Indiana, and elsewhere. If take-or-pay tariffs spread, the cross-subsidy shrinks.
Second, some analysts argue data centers can and do pay premiums, so the market is functioning, not failing. If they are willing to pay the highest rates, the argument goes, that is a price signal, not a theft.
Third, free-market critics like the Buckeye Institute warn the tariffs may backfire. Charge the most mobile customers the highest markup and they relocate or go off-grid, but the transmission gets built anyway, and ratepayers are left holding it. On that view the problem is not who pays but a planning system straining to serve demand it cannot accurately predict.
The Risk
For anyone building, financing, or siting AI infrastructure, the real exposure here is that a load-bearing assumption is being repriced. Cheap, socialized power was a free subsidy that made the unit economics of the scaling-law bet look better than they were. That subsidy is closing. Take-or-pay tariffs shift stranded-asset risk from ratepayers onto data-center operators, which is exactly where the political wind is blowing it. If AI demand disappoints, someone eats billions in idle capacity, and the identity of that someone is being rewritten in real time.
The political risk is just as concrete. Data centers have become, in the words of one Jefferies research note, the “villain” of the affordability debate. Virginia has moved to strip a $1.6 billion tax break for data-center equipment. Georgia voters ousted two incumbent utility commissioners. President Trump has leaned into a ratepayer-protection message. Moratoriums, tariffs, and tax rollbacks are multiplying state by state. The era of frictionless siting on the promise of cheap local power is ending.
What to Watch
Watch the Ohio Supreme Court, where the state’s manufacturers are challenging the AEP tariff, because that ruling sets the template other states will copy or avoid. Watch whether federal regulators adopt Monitoring Analytics’ proposal to pull speculative data-center load out of the base capacity auction, which would end the pre-paying-for-phantom-demand problem overnight. Watch the alternative cost-sharing models: Missouri returns 65 percent of extra revenue from large customers to everyone else, and Texas leans on demand flexibility instead. And watch the November midterms, which are shaping up as the first national referendum on who pays for the power behind the AI boom, a build-out that is also colliding with a shortage of the electricians needed to wire it.
The Business Model Analyst Take
The AI industry’s dirtiest open secret is not water usage or carbon. It is that one of its cheapest inputs was quietly financed by households through a hundred-year-old cost-socialization mechanism that worked beautifully right up until people noticed. Now they have noticed, and this repricing is structural, not cyclical.
That leaves the industry two exits, both of which raise its real cost of doing business. It can internalize the true cost of power through take-or-pay tariffs and direct contracts, which dents the economics the whole scaling-law thesis is underwritten on. Or it can defect off-grid with behind-the-meter generation, which fixes the ratepayer optics but loads capital risk and local pollution onto the operator and its host town. Either way, “free electricity as a siting subsidy” is over.
For founders and investors, the lesson generalizes past energy. When a business model depends on an externalized cost that nobody is auditing, the model is not as profitable as it looks. It is borrowing against a bill that eventually arrives. The most durable question in AI right now is not who has the most compute. It is who is quietly paying for it, and what happens to the economics when that subsidy gets clawed back. The companies renting capacity from landlords like Amazon are about to find out whether the power was ever really cheap, or just cheap for them.