
The Wall Street Journal found people bidding themselves into bankruptcy on the live shopping app. The more revealing number is the one Whatnot gave the reporters about its own cut.
Whatnot told the Journal it collects roughly 6% of every sale. Run the company’s published fee schedule against the small orders its auction format produces and you get 11% to 14%. Divide the revenue reported around its last funding round by its reported 2025 gross merchandise volume and you get 12.5%. Whatnot is charging close to what eBay charges, on a product engineered to generate many times the orders.
Sean Harding spent $1,362,687.31 on Whatnot in four months. His wife found out and filed for divorce. He resigned, emptied his retirement account, sold the house, the car and the cards, and then went back and spent another $37,000 this year.
That is the story the Journal published on August 4. The number that deserves equal attention appears eleven paragraphs in, delivered by a company spokeswoman as a throwaway: Whatnot collects an average of about 6% of every sale globally.
What Happened
Hanna Krueger and Sarah Nassauer spent the piece on Whatnot’s design. Auctions run on 45-second countdown clocks. Bidding happens with a swipe, no confirmation screen, no checkout. Hosts scream at the chat to bid faster. An algorithm decides which show you land in. Mark Leiser, who taught digital law at Leiden University, called the cumulative effect a degradation of consent.
CEO Grant LaFontaine rejected that reading and pointed to the app’s 4.7 rating. He said addiction and overspending have not shown up as significant problems in the company’s internal or external data. He also described a queue of friction features: optional spending limits and watch-time caps introduced last year, a spending pause that started rolling out last week, a passcode-restricted buying step in testing, and flags aimed at users whose spending velocity spikes.
The company disclosed the shape of the business alongside all this. Whatnot added more than 20 million accounts in 2025. Sellers moved over $8 billion in goods, roughly double 2024. Fashion buyers alone bought more than 12 million items a month. The platform hosts over 550,000 hours of live shows a week. About 1,200 people work there, a third of them on trust and safety.
The Backstory
LaFontaine and Logan Head started Whatnot in 2019 as a place to trade Funko Pops. They added live shows in 2020 after watching people auction figurines on Instagram, then stacked on Pokemon cards, sports cards, coins, sneakers, fashion, knives, horse tack, live plants and, in 2026, fish and steak.
Investors kept paying more each round. Whatnot closed a $265 million Series E in January 2025 at close to $5 billion. Ten months later it closed a $225 million Series F co-led by DST Global and CapitalG at $11.5 billion, with Sequoia and Alkeon joining and existing holders taking up to $126 million off the table through a tender. Total raised sits near $970 million.
The seller side matured alongside the buyer side. One in eight Whatnot sellers now works the platform full time. Sellers crossed a billion cumulative orders in June 2026. Whatnot connected to Shopify in April so merchants could sync inventory across both systems, which is the sort of plumbing you build when you want larger sellers to treat you as a channel rather than a hobby.
We covered the seller economics of this format in June, when a Nebraska coin dealer streamed for 177 hours straight and sold $2,047,000 of coins. His margin after giveaways, platform fees and cost of goods was the twist in that story. This one runs the same arithmetic from the platform’s side of the table.
The Plan
Whatnot publishes its fees. Sellers in the US, Canada and Australia pay an 8% commission on the item price plus a payment processing fee of 2.9% plus 30 cents on the total order. UK and EU sellers pay 6.67% plus VAT. Electronics run 5%, coins and money 4%. Whatnot’s own worked example puts a $50 sale at $5.75 in fees and a $44.25 payout.
That flat 30 cents does more work than anything else in the schedule. On a $200 order it costs a seller 0.15% and disappears. On a $10 order it costs 3% and dominates. The effective rate therefore climbs as orders get smaller, which is the opposite of how buyers assume marketplace pricing works.
Whatnot’s format manufactures small orders. Bidding opens at a dollar. The swipe bar submits a few dollars over the current high bid. Card breaks sell slots, not boxes. Third-party estimates put average order value somewhere between $18 and $28, and at those sizes the schedule returns between 12.0% and 12.6%.
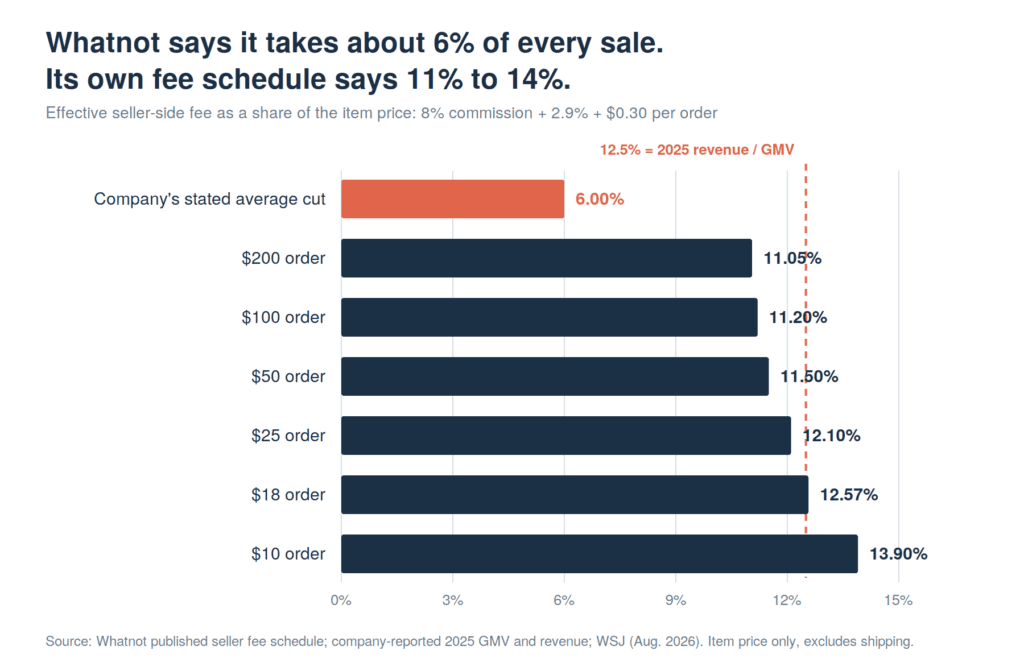
Two independent paths land in the same place. The fee schedule applied to Whatnot’s actual order sizes gives about 12.5%. Revenue reported around the Series F, roughly $1 billion against $8 billion of 2025 GMV, gives 12.5%. The Journal’s 6% is the commission line with the processing fee and the flat charge removed, and with the discounted categories averaged in.
For comparison, eBay’s take rate reached 13.95% in FY2025, up from 10.10% in 2019. Whatnot got to within 1.5 points of that in six years. eBay needed twenty six.
The Business Model Angle
Take rate is the profit lever in any marketplace, and platforms almost never raise the headline number. They own the payments, sell the visibility back to sellers, or bundle mandatory services. Whatnot did something different and more elegant: it built a product whose native transaction size sits exactly where the flat fee bites hardest, then quoted the commission line to reporters.
Look at where Whatnot has cut. Since January 14, 2026, the platform charges 0% base commission on the portion of any order above $1,500 in select categories. Coins run at 4%. Electronics at 5%. Every concession sits at the high-ticket end, which is the end where Fanatics Live competes for graded cards, where sellers do the math before they list, and where a fee complaint turns into a trade-press story.
Nobody audits the fee on a $14 Pokemon card. That is where the money is, and the format produces those orders by the tens of millions.
This reframes the engagement metrics. Users averaging 95 minutes a day and month-over-month retention above 80% are not vanity numbers for a marketplace running a low order value. They are the requirement. At an $18 order Whatnot earns about $2.26. A buyer who shops twice a year is worth $4.50. The model needs the buyer who shops twice a night, and the product is built to produce that buyer.
The valuation assumes it keeps working. At $11.5 billion against $8 billion of GMV, investors paid 1.44 times volume. eBay trades near 0.65 times its GMV. Whatnot carries more than double eBay’s multiple on the same fundamental business, with the premium resting on continued volume doubling rather than on further take rate expansion, because the take rate is already there.
The Risk
Paul Lesko has filed arbitration demands for nearly 70 clients alleging that Whatnot’s randomized box breaks and repack breaks violate California’s ban on illegal lotteries and the state’s specific prohibition on trading card grab bags, and that the company’s conduct amounts to racketeering. His 132-page complaint calls Whatnot an unregulated online casino. A separate suit under the California False Claims Act, filed in July 2025 against Whatnot and Fanatics Live, was unsealed this year.
Whatnot rejects the characterization and notes that buyers walk away with a card. That distinction is doing heavy lifting given that the arbitration is structured to hurt regardless of outcome. Whatnot’s own terms push disputes into private arbitration, and Lesko is filing dozens of individual demands rather than one class action. Filing fees on the company side run $1,500 to $3,000 per case.
The exposure concentration is the part worth watching. Lesko’s clients have spent more than $252 million on the platform between them. That averages $3.6 million a person. Whatnot says breakers make up 4% of its sellers and has declined to say what share of revenue they generate, which is the sort of number a company discloses when the answer is small.
Every friction feature LaFontaine described removes revenue. A passcode step before purchase, a spending pause, a velocity flag: each one targets the exact behavior that makes a 12.5% take rate on an $18 order work. Whatnot is building a brake and hoping the growth curve does not notice.
One more inconsistency sits in the company’s own reporting. Whatnot’s 2026 State of Live Selling Report puts live shopping across North America and Europe at $22 billion and claims nearly 60% share. Sixty percent of $22 billion is $13.2 billion. Whatnot’s global GMV that year was $8 billion. The two figures come from the same document and do not reconcile.
Quick Questions
Is 12.5% high for a marketplace? It sits at the upper middle. Etsy takes about 24% of gross merchandise sales. Uber’s blended rate runs near 27%. eBay reached 13.95% in FY2025. Amazon’s headline referral fee is 15% and its all-in FBA cost lands closer to 50%.
Does the fee schedule really vary that much by order size? Yes, because of the flat 30 cents. A $10 order carries a 13.90% effective rate. A $200 order carries 11.05%. Whatnot’s published $50 example matches the formula exactly.
Why would Whatnot quote 6% then? The 6% figure describes an average commission line across geographies and categories, excluding processing. It is defensible as stated and misleading as understood.
Are card breaks gambling? Courts have not ruled. Lesko argues the randomized slot assignment makes it a lottery. Whatnot argues buyers always receive a card, so nobody walks away with nothing. That specific distinction is what an arbitrator will have to decide.
Is Whatnot going public? No filing exists. The Series F carried the structure of a pre-IPO round, including a secondary tender, and observers expect a listing in late 2026 or 2027.
The Business Model Analyst Take
The Journal wrote a consumer-harm story and it is a good one. The business story sitting underneath it is that Whatnot has already completed the take rate journey eBay spent two decades on, and almost nobody has noticed because the company describes its cut using the one component that sounds modest.
That matters for anyone building a marketplace. The received wisdom says you enter with a low take rate, buy volume, then ratchet the fee once sellers are locked in. eBay ran that play and it worked on the income statement while active buyers fell 22% and GMV shrank. Whatnot skipped the ratchet by choosing a transaction size where a fixed per-order fee delivers the same result without a headline number anyone can complain about.
The vulnerability is that the strategy requires the buying behavior described in the Journal’s article. eBay’s model survives a customer who shops twice a year. Whatnot’s does not. Which means the friction tools, the arbitration claims and any eventual regulatory line on card breaks are not reputational side issues for this company. They are load-bearing.
Watch two things. First, whether Whatnot discloses average order value or order counts ahead of an IPO, because that single figure converts the fee schedule into a verifiable take rate. Second, whether the effective rate moves after the passcode step ships. If it holds, LaFontaine was right that overspending is not the engine. If it slips, the Journal wrote a business story and filed it under retail.