
The Series G disclosed merchandise volume, buyers, orders and livestream hours. The one number that sets the multiple has not moved in public since last year.
Whatnot closed a $545 million Series G on August 5 at a $20 billion valuation, nearly double the $11.5 billion it carried nine months ago. Measured against merchandise volume, investors paid less per dollar this round than they did last October. Measured against the only revenue figure Whatnot has put in public, they paid nearly twice as much. Both statements are true, and the gap between them is the entire question the round poses.
Grant LaFontaine gave the game away in the announcement coverage. Asked about the number, Whatnot’s CEO told Fortune that when the company raises, it pulls its own multiples back into a valuation range it can “grow into.” Founders do not usually describe their own mark as a target to catch up to. LaFontaine did, and he was right to.
What Happened
Iconiq, Lightspeed and Avra led the round. Kleiner Perkins, Wellington Management and Standard Capital, the new firm of former Y Combinator partner Dalton Caldwell, came in fresh. Andreessen Horowitz, Bond, DST Global, Greycroft, Y Combinator and Alphabet’s CapitalG all returned. Robinhood’s Ventures Fund I disclosed a $30 million check. Whatnot has now raised roughly $1.5 billion since 2019.
The company released a volume-heavy set of numbers alongside the raise. Gross merchandise volume in the first half of 2026 passed $8 billion, matching the whole of 2025 in six months. Buyers more than doubled over twelve months. More than 650,000 people sign up each week. The platform hosts over 550,000 hours of live shows weekly, and it crossed one billion cumulative orders in June. Sellers who have passed $1 million in lifetime sales more than doubled year over year.
None of those figures is revenue. The revenue number in circulation comes from an earlier Inc. interview, where Whatnot said it was on track to surpass $1 billion for the year. The Information reported in December that Whatnot was targeting close to $1 billion for 2025. Both numbers start with a one.
The Backstory
Whatnot has repriced itself roughly every ten months. A $150 million Series C valued it at $1.5 billion in 2021. A $265 million Series E landed near $5 billion in January 2025. DST Global and CapitalG co-led a $225 million Series F at $11.5 billion last October, with a tender of up to $126 million letting early holders sell. Each round has arrived with a bigger GMV figure attached.
We ran the fee arithmetic yesterday in our breakdown of Whatnot’s take rate. Two independent paths, the published fee schedule applied to real order sizes and reported revenue divided by reported GMV, both landed near 12.5%. That is the number that converts merchandise volume into money, and it sits close to where eBay ended FY2025 at 13.95%. On the seller side, a Nebraska coin dealer’s $2 million livestream marathon showed what those fees do to a thin-margin category.
Hold that 12.5% in mind. Everything below turns on whether it survived the past twelve months.
The Plan
LaFontaine said the money goes toward seller tools, more AI in the selling flow, buyer acquisition, trust investment and new markets. Whatnot’s own blog post to sellers framed the raise as the largest in live shopping and pointed the proceeds at seller growth and platform trust.
Read that list as a fee forecast. Buyer acquisition and trust spending are cost lines, not revenue lines. Category expansion into fresh food, groceries and fashion moves the mix toward smaller tickets and thinner categories. International growth moves it toward the UK and EU schedule, which charges 6.67% plus VAT against 8% in the US. And since January 14, Whatnot has taken zero commission on anything above $1,500, plus reduced rates of 5% on electronics and 4% on coins.
Every one of those moves buys volume with rate. That is a defensible strategy against TikTok Shop, which undercuts on commission, and against Fanatics Live at the high-ticket end. It also means GMV and revenue have stopped moving together.
The Business Model Angle
Price the round against merchandise volume first. At Series F, $11.5 billion against $8 billion of 2025 GMV worked out to 1.44 times. If Whatnot finishes 2026 near $18 billion of GMV, which is conservative given that the first half alone cleared $8 billion, then $20 billion works out to about 1.11 times. Land the year at $16 billion and it is 1.25 times. Land it at $20 billion and it is parity. On volume, this round is cheaper than the last one in every scenario.
Now price it against revenue. At Series F, $11.5 billion against roughly $1 billion put the multiple at 11.5 times. At Series G, the company’s stated revenue floor of $1 billion puts it at 20 times.
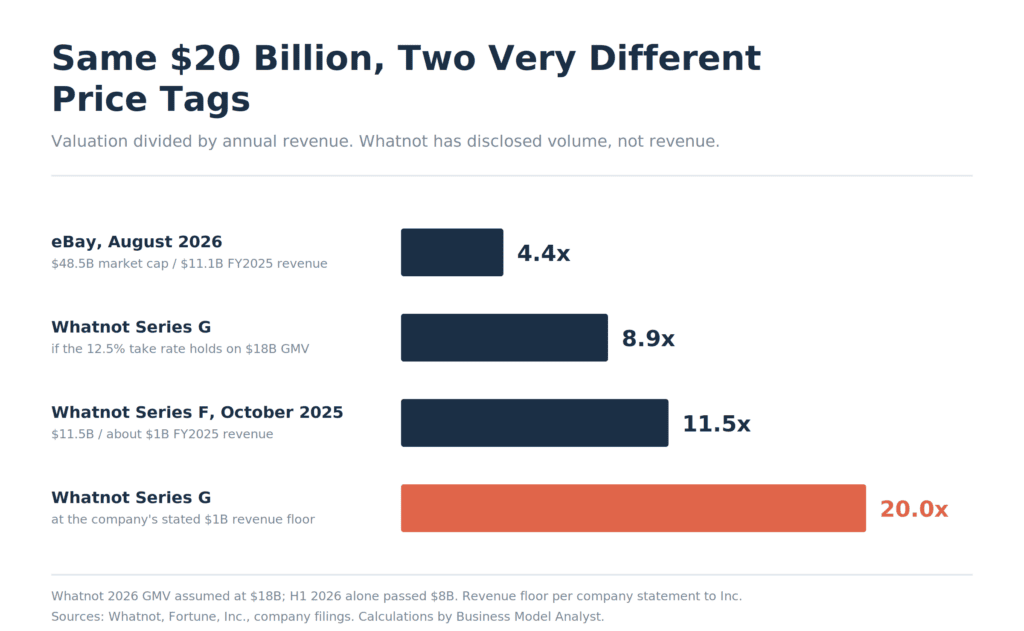
Two multiples cannot move in opposite directions unless the take rate is falling. Keep 12.5% on $18 billion of volume and Whatnot earns $2.25 billion this year, which prices the round at 8.9 times revenue and makes it the cheapest capital the company has ever raised. Hold revenue at the stated $1 billion floor against that same volume and the blended take rate has fallen to about 5.6%, and investors paid 20 times for a company that gave away half its rate to buy growth.
That 5.6% deserves a second look. A Whatnot spokeswoman told the Wall Street Journal this week that the platform takes about 6% of every sale globally. We treated that as a commission-only figure describing something narrower than the effective rate, and on a single order it still is. The mix math opens a second reading. She may have been describing where the blended rate is heading.
The honest answer is that nobody outside the cap table knows. Whatnot’s investors saw the audited revenue line. The rest of us have a floor from an interview that predates the half-year results, and a company that chose to announce seven volume metrics and zero revenue metrics on the day it doubled its price.
The Risk
The strongest case against this reading is that the $1 billion figure is stale and deliberately conservative. Companies quote floors, not forecasts, and Whatnot has never published a revenue number it had to defend. If 2026 revenue lands near $2.2 billion, this round priced at 8.9 times revenue against eBay’s 4.4 times, which is a growth premium rather than a bubble, and the volume multiple compression means Iconiq and Lightspeed bought the discipline LaFontaine described. Watch for any revenue figure above $1.5 billion in the next six months. That would settle it.
Three other pressures sit on the rate. Paul Lesko has filed arbitration demands for roughly 70 clients who spent a combined $252 million, arguing the platform runs as an unregulated casino, and Whatnot disputes the characterization. Mass arbitration costs the company $1,500 to $3,000 per filing before anyone argues merits. Trust and safety already consumes about a third of headcount. Regulatory or contractual friction on the auction mechanics would hit exactly the low-ticket, high-velocity orders where the fee schedule earns most, a point we covered in how take rate works as a business model lever.
Then there is the market claim. Whatnot says it holds about 60% of a US live commerce market worth more than $22 billion. Sixty percent of $22 billion is $13.2 billion. Whatnot’s own global volume is running above that. A company cannot be a minority of a market it has outgrown, which means the next leg of growth has to come from creating demand rather than taking share.
One more thing worth naming. Venture funding in the first half of 2026 ran $412.7 billion in the US, and AI companies took $355.9 billion of it. Whatnot raising $545 million against that backdrop reads as vindication in most coverage. It also means Iconiq and Lightspeed were choosing among very few non-AI assets with proven consumer volume, and scarcity on the buy side does not always produce careful pricing.
Quick Questions
Is $20 billion expensive for a marketplace? On merchandise volume, no. Whatnot at roughly 1.1 times GMV sits above eBay’s 0.61 times, which is the gap you would expect between a business doubling and one shrinking. On revenue, it depends on a number Whatnot has not published.
How does this compare to public retailers? Best Buy carries a market cap near $17.2 billion and Lululemon near $14 billion. Both are liquid common stock net of debt. A $20 billion private post-money sits on preferred shares with liquidation preferences attached, so the two are not the same unit.
Why does the take rate matter more than GMV? GMV is the money passing through. Revenue is the money Whatnot keeps. A platform can double volume and earn less if it cut its rate to get there.
Was Whatnot profitable? It was not, as of mid-2025, and the company has not said otherwise since.
When does Whatnot go public? LaFontaine says he would prefer to stay private as long as possible while acknowledging the calculus changes. Filing would force the revenue disclosure this round did not require.
Who else is chasing this market? TikTok Shop competes on commission, Fanatics Live competes at the high-ticket collectibles end, and Amazon and YouTube keep adding live features. Facebook and Instagram shut their live shopping products in 2023.
The Business Model Analyst Take
Marketplaces get valued on volume when they are young and on take rate when they are grown. Whatnot is being valued on volume at $20 billion, and its CEO said out loud that he priced the round below what he could have taken so the business could catch up to it. Both of those are signs of a company that knows its revenue line is not yet the story it wants told.
That is not damning. Amazon spent two decades trading volume for rate, and the biggest venture rounds in history mostly went to companies underwriting exactly this bet. Whatnot has the rarest asset in consumer internet, a marketplace with working network effects, and it earned its place among the fastest-growing companies in the world on merit.
The thing to track is not the valuation. It is the first time Whatnot publishes a revenue figure that starts with a two. Until then, the $20 billion rests on volume, and volume bought with fee concessions is the most expensive kind.