
Whataburger operates 78% of its 1,161 restaurants itself, asks franchisees for a $12.5 million net worth, and hands finished markets to partners once the receipts exist. The burger is the product. Going first is the business.
The Whataburger business model
Whataburger is a majority company-operated burger chain that funds new geographies with its own balance sheet, proves them with company restaurants, then sells or joint-ventures those markets to capitalized partners while keeping its mature Texas base under direct ownership. Revenue comes from three layers: restaurant sales it books in full, royalties and marketing fees on franchised units, and licensing income from grocery products. BDT & MSD Partners has held the majority stake since 2019; the Dobson family retains a minority position.
Whataburger at a glance
| Item | Figure |
|---|---|
| Founded | August 1950, Corpus Christi, Texas, by Harmon Dobson and Paul Burton |
| Headquarters | San Antonio, Texas, since 2009 |
| Owner | BDT & MSD Partners (majority since June 2019); Dobson family (minority) |
| CEO | Debbie Stroud, since January 1, 2025 |
| US systemwide sales, fiscal 2025 | $4,311 million |
| Restaurants, fiscal 2025 | 1,161 (908 company, 253 franchised) |
| Net units added, fiscal 2025 | +76 |
| Average unit volume | $3,914,000 |
| States | 17, with 774 restaurants in Texas as of February 2026 |
| Operating hours | 24 hours a day since 1982; breakfast 11 p.m. to 11 a.m. |
| Employees | More than 50,000, called Family Members |
What Whataburger is selling to its franchisees
Read the franchise requirements and the model stops looking like fast food. Whataburger asks for a $12.5 million net worth and a commitment to open five restaurants inside five years, and it directs applicants toward new territories rather than open ground in existing ones. Liquid capital requirements have been reported anywhere from $1.2 million to $5 million depending on the vintage of the page you read, but the net worth threshold and the five-in-five development commitment show up consistently.
That screen eliminates the career restaurant operator who wants to buy a job. It selects for a different buyer, and the roster proves it. Made to Order Holdings, which runs the Georgia units, belongs to Travis Goff of Goff Capital, a Fort Worth family office. WAB Venture took Arkansas and Oklahoma. KMO Burger, which now holds every restaurant in the Kansas City and Springfield markets, counts Patrick Mahomes among its owners.
None of those groups bought an operating system. They bought a geography where Whataburger has demand it has not yet served, and they brought the capital to build it out.
The Texas core stays company-owned
Texas holds 774 of the 1,180 restaurants counted in February 2026, about 66% of the system. Against a Texas population of roughly 32.1 million, that works out to one Whataburger for every 41,474 residents. McDonald’s runs one restaurant for every 25,067 Americans nationally. Whataburger has built its home state to 60% of the store density the largest chain in the country maintains across all fifty states.
Texas is close to full. It also throws off $3.9 million a year per building, and Whataburger keeps every dollar of it because it owns the restaurants. A franchisor in the same position collects a reported 4% to 5% royalty and a 2% to 2.5% marketing fee, then watches the operator keep the rest. Chick-fil-A’s fee structure lets it capture an unusual share of its system, and we ran that arithmetic in the Chick-fil-A business model teardown. Whataburger reaches a similar place by a blunter route: it never sold the restaurants in the first place.
Selling Texas down would convert a mature, high-volume, fully-amortized asset into a thin fee stream. Nobody at BDT wants that trade. The 253 franchised restaurants sit at roughly 62% of the 406-unit non-Texas footprint by count, and while the two sets are not identical because legacy Texas franchises still exist from the 1950s and 1960s, the direction is unmistakable. Franchising happens where Whataburger is new.
Kansas City, in two acts
Whataburger entered Kansas and Missouri in 2022 with 16 company-owned restaurants. KMO Burger, already a franchise partner, opened 13 more. On May 14, 2025, Whataburger contributed all 16 of its own restaurants to a joint venture and KMO took over operations of all 29. Every hourly employee moved onto KMO’s payroll.
Whataburger paid to prove that market and then stopped owning it.
The company does not publish its Franchise Disclosure Document, so the cost has to be modeled from reported ranges. At the midpoint of the $1.2 million to $3.0 million per-restaurant investment those ranges describe, 16 restaurants absorbed about $33.6 million of Whataburger’s capital. A franchisor that had let a partner build them instead would have collected 16 initial fees at a reported $45,000 each, or $720,000, and spent nothing. The swing between those two paths runs to roughly $34 million on a single metro.
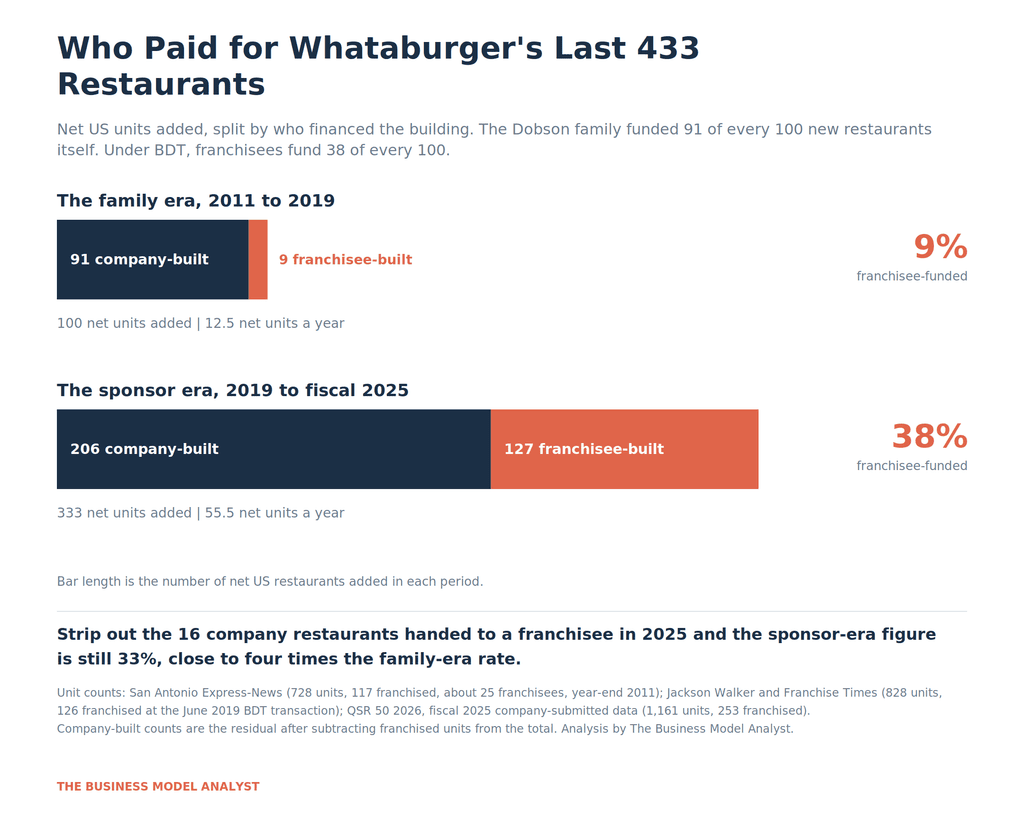
The reason Whataburger pays that bill is that nobody else can. A new market has no operating history. A franchisee cannot underwrite it, and a lender will not finance it against a comparable set that does not exist. Whataburger’s own balance sheet is the only capital that can price the risk of the first Missouri restaurant. Once 16 of them have two or three years of receipts, the market becomes financeable for somebody else, and Whataburger sells.
Restaurant Brands International runs a version of this in reverse, buying an existing franchisee and refranchising it after a remodel, which we covered in the Burger King refranchising piece. Whataburger builds the asset rather than buying it, and the purpose is geographic reach rather than margin repair.
Who paid for the last 433 restaurants
The ownership change shows up cleanly in the unit counts.
At the end of 2011, Whataburger ran 728 restaurants in ten states. The Dobson family owned 611 of them, and about 25 franchisees held the other 117. When BDT bought its majority stake in June 2019, the system had reached 828 restaurants with 126 franchised. By fiscal 2025 the count stood at 1,161 with 253 franchised.
Across the eight family years, Whataburger added 100 net restaurants and 9 of them were franchisee-funded. Across the six sponsor years, it added 333 and 127 were franchisee-funded.
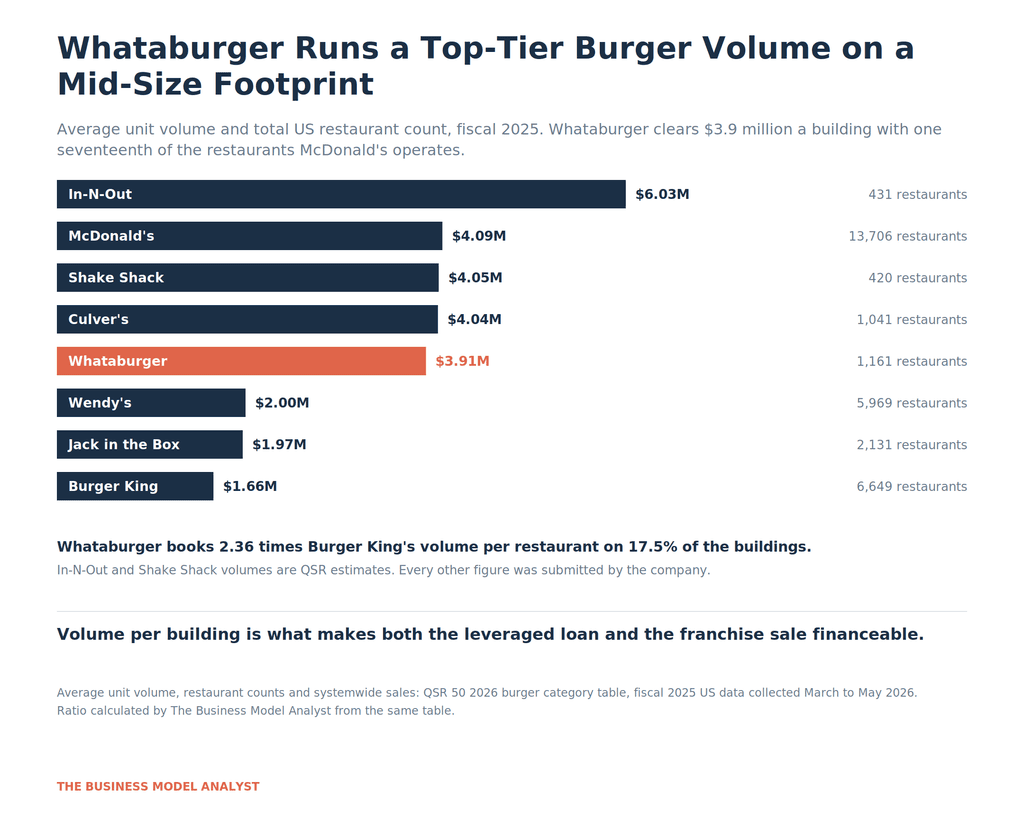
The franchisee share of new buildings went from 9% to 38%. Strip out the 16 Kansas City restaurants that changed hands in 2025 without a new building going up, and the honest sponsor-era figure is 33%, still close to four times the family rate.
The pace changed with it. The family added 12.5 net restaurants a year. BDT has added 55.5.
Both numbers matter, and they are the same number viewed twice. Whataburger did not learn to build faster. It found a second source of construction money and started spending its own capital on markets instead of on buildings.
The volume that makes it financeable
None of this works at a normal burger volume.
Whataburger clears $3,914,000 per restaurant. That puts it fifth in the QSR 50 burger table, behind In-N-Out, McDonald’s, Shake Shack and Culver’s, and ahead of every high-unit-count competitor it faces.
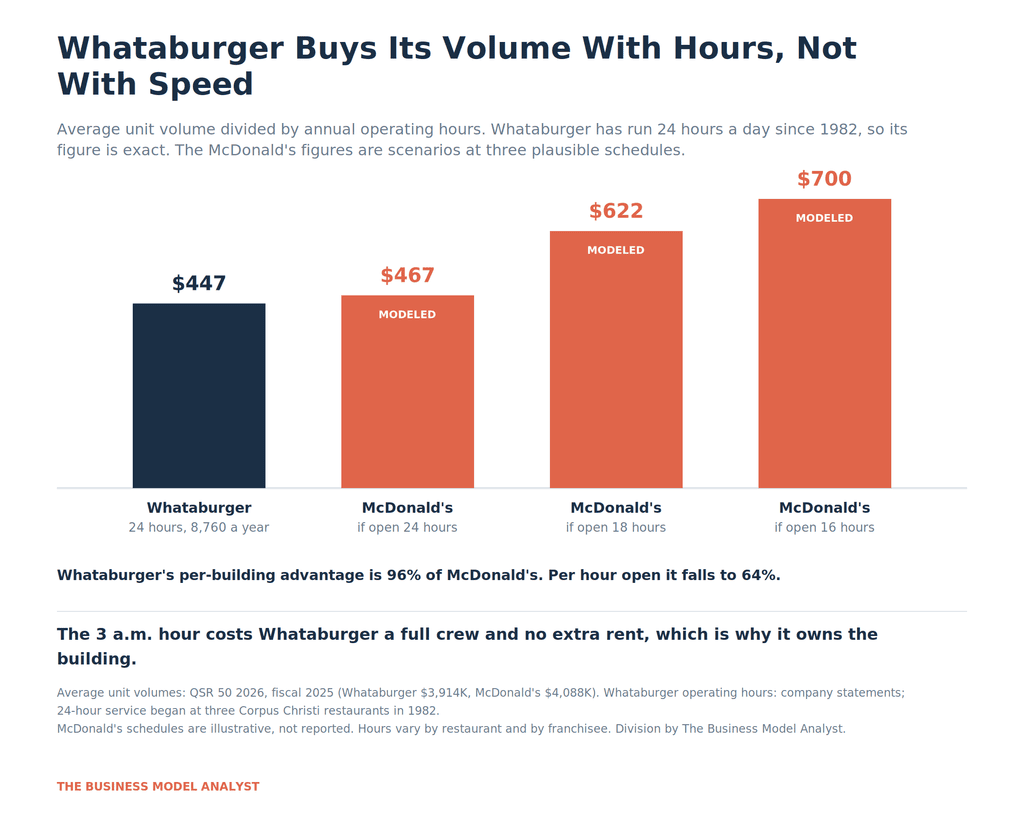
Set it against Burger King. Whataburger books 2.36 times the volume per restaurant on 17.5% of the buildings, and produces 38.9% of Burger King’s systemwide sales from that much smaller footprint.
Volume per building is the collateral for the whole structure. It supports the leveraged loan, since Whatabrands LLC carries a 2024 first lien Term Loan B priced at one-month Term SOFR plus 250 basis points, marked at a 6.82% coupon and maturing August 3, 2028, according to mutual fund holdings filed with the SEC. It supports the franchise sale, because a $12.5 million net worth requirement only makes sense against restaurants that clear four million dollars.
Raising Cane’s borrowed at 50 basis points tighter and stretched its maturity to 2031, which is the trade a chain makes when it gives up franchising altogether. Whataburger kept both funding sources and pays a little more for the loan.
The clock is a capital argument
Three Corpus Christi restaurants started running 24 hours in 1982, and the company never backed off. Breakfast runs from 11 p.m. to 11 a.m., a twelve-hour window that catches the late shift going home and the early shift heading out.
Divide the volume by the hours and the picture inverts.
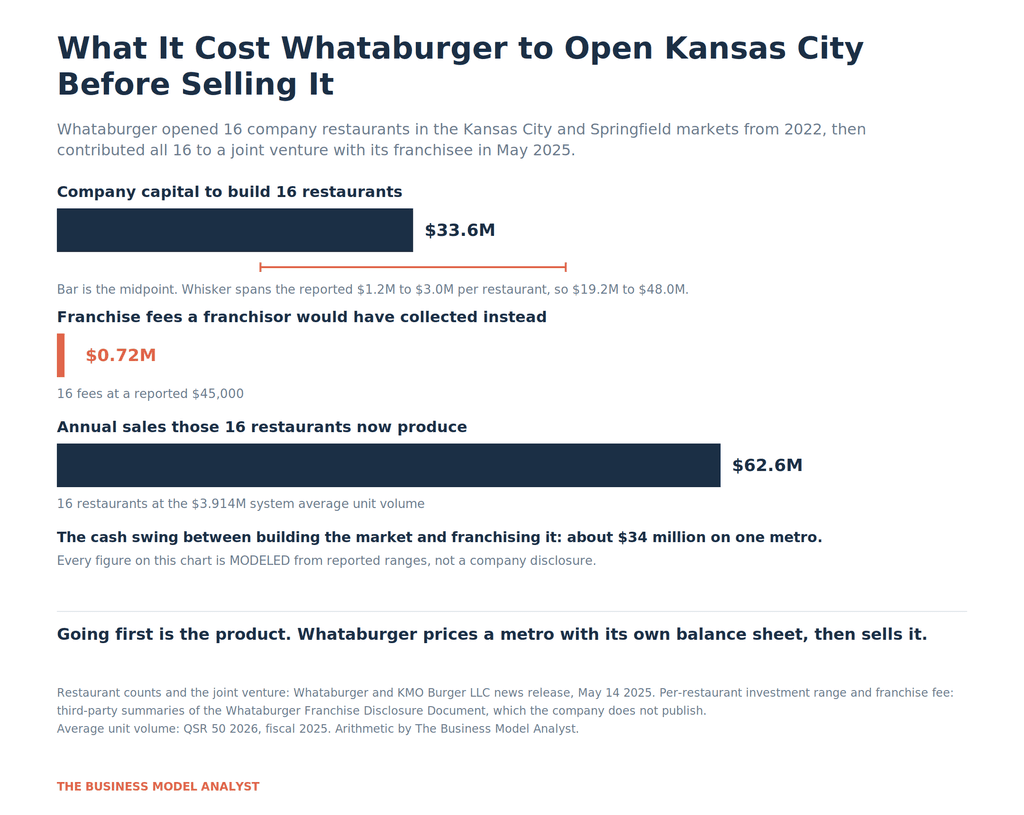
Whataburger earns $447 for every hour it is open, and that figure is exact because the hours are known. McDonald’s schedules vary by restaurant and by franchisee, so any comparison has to run as a scenario, but at an eighteen-hour day McDonald’s would clear $622 an hour. Whataburger’s advantage per building is 96% of McDonald’s. Per hour open it drops to 64%.
Whataburger buys its volume with duration. The 3 a.m. hour costs a full crew and zero additional rent, insurance or depreciation, which is a good trade for whoever owns the building. Chick-fil-A runs the opposite play, closing one day a week and still producing more revenue per day open than anyone, which our forthcoming Chick-fil-A value chain analysis quantifies.
The clock also travels. Nostalgia for an orange A-frame does not exist in North Carolina. Demand for hot food at two in the morning does.
The operating model underneath it
The restaurant itself has stayed close to what Harmon Dobson built. Whataburger cooks to order, so the patty hits the grill after the customer orders rather than before. Stroud puts the trade plainly: you wait a minute or two longer and the burger arrives hot. Customization carries the menu, from the Whataburger Jr. and the Justaburger up through the Triple Meat, plus the Whatachick’n line the company has been expanding as customers shift toward chicken.
Made to order collides with a 24-hour drive-thru model, and the company knows it. Whataburger is installing new kitchen flow and new equipment to shorten the wait without changing the cooking method. It launched a $3, $4 and $5 Whatadeal menu in January 2026, and it is rebuilding the app on the theory that the digital customer should get the same experience as the one in the parking lot.
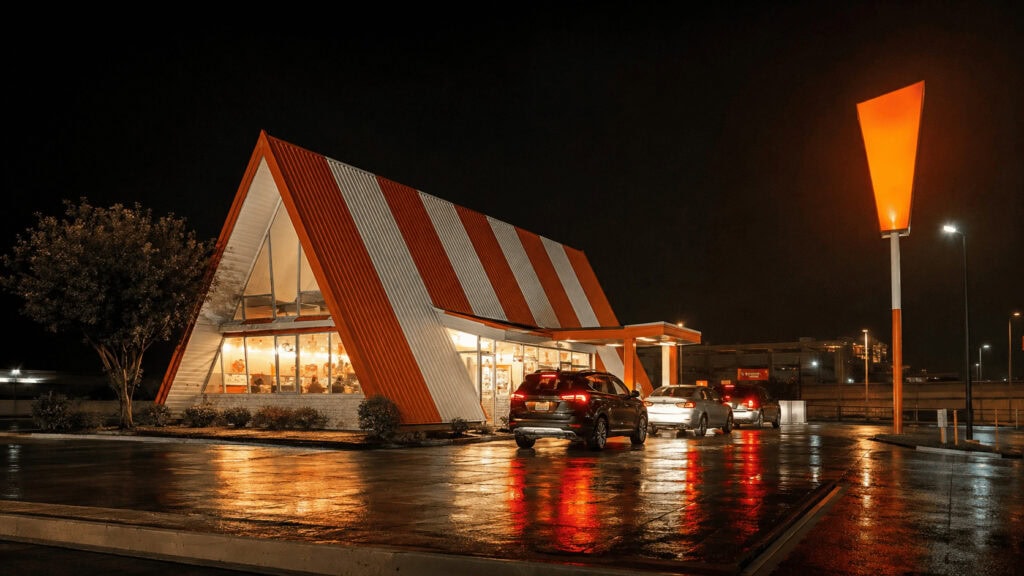
The building matters too. Whataburger dropped the classic A-frame from its newer prototypes and heard about it from customers and staff, so the next prototype restores the orange-and-white stripe and starts going up in 2027. New restaurants run double drive-thrus and curbside.
One revenue line sits outside all of this. Whataburger has sold its sauces at H-E-B since 2014 and has since added bacon and pancake mix to grocery shelves well beyond its restaurant footprint. That business collects royalty income and requires no restaurants at all, which makes it the cheapest way the company keeps the brand alive in states it has not entered yet. A shopper in Ohio can buy the Fancy Ketchup years before a Whataburger opens nearby, and that shopper is part of the demand a franchisee eventually pays for.
How the model makes money
| Layer | What it is | Who funds the building | What Whataburger keeps |
|---|---|---|---|
| Company restaurants | 908 units, the Texas core plus new-market entries | Whataburger | The entire sales line, and the entire cost line |
| Franchised restaurants | 253 units, concentrated outside Texas | Franchisee | Reported 4% to 5% royalty plus 2% to 2.5% marketing fee |
| Joint ventures | KMO Burger holds 29 restaurants in Missouri and Kansas | Partner, with Whataburger contributing built assets | An equity position plus the fee stream |
| Grocery licensing | Sauces since 2014 at H-E-B, plus bacon and pancake mix nationally | Licensee | Royalty income with no restaurant capital attached |
| Market entry | Company-first openings in states with no operating history | Whataburger | The right to sell a proven market later |
The bottom row is the one that does not appear on anyone’s income statement, and it is the one the model runs on.
What could break it
The brand is a depleting asset outside Texas. What Whataburger sells a franchisee in Charlotte is 76 years of Texas identity showing up as pent-up demand, carried there by people who moved. Each new state spends some of that inheritance. Once a market has a Whataburger on the corner, the transplant story stops working and the restaurant competes on food, price and speed like everyone else.
Pruning has started. Whataburger closed eight corporate restaurants across three states in December 2025 for poor performance. Reported 2026 opening plans range from 40-plus, per a company spokesperson, to more than 70. A gap that wide suggests the number is still moving.
The company owns 78% of its own cost exposure. Ground beef ran $6.885 a pound in July 2026, up 11.5% year over year, with the US cattle herd at its smallest since 1951. A franchised system spreads that across hundreds of independent balance sheets. Whataburger absorbs it on one. McDonald’s earns its franchisor margin whatever beef costs, a split we broke down in the McDonald’s landlord margin analysis.
Made-to-order costs seconds. Stroud has said the company is installing new kitchen flow and equipment to cut the wait without changing the cooking. Every second in the drive-thru window is a real constraint on a chain whose volume depends on throughput across 24 hours.
The loan matures in 2028. The Term Loan B comes due before the 1,800-restaurant ambitions attributed to BDT can be finished, which puts a refinancing in the middle of the build.
Texas concentration cuts both ways. Two thirds of the system sits in one state’s economy, one state’s weather and one state’s labor market.
What the model adds up to
Whataburger answers a question every chain has to answer and most answer once. McDonald’s decided in the 1950s that franchisees would pay for the buildings, and it has collected rent and royalties ever since; the mechanics are in our McDonald’s business model breakdown. In-N-Out decided it would pay for all of them itself and accepted a slower growth rate as the price. Both answers are permanent.
Whataburger answers it by market. Texas is finished, so Whataburger owns it. North Carolina is unproven, so Whataburger buys it, opens it, and then sells it to someone with a checkbook and a reason to want the region. The company is not choosing between the company-operated model and the franchise business model. It runs both, sorted by how much operating history a market has.
That explains the leadership too. Debbie Stroud spent 27 years at McDonald’s and five at Starbucks, where she oversaw more than 10,000 retail stores and worked the licensed side of the business. Todd Ewen joined as chief development officer in March 2025 from McDonald’s, where he worked in development and real estate. BDT did not hire burger people. It hired the people who know how to open markets and manage the operators who buy them.
Frequently asked questions
Is Whataburger a franchise? Partly. Of 1,161 restaurants in fiscal 2025, 253 were franchised and 908 were company-operated. Whataburger franchised its first restaurant in 1953 in Alice, Texas, stopped granting new franchises for around two decades, and reopened the program after BDT bought its majority stake in 2019.
Who owns Whataburger? BDT & MSD Partners, a Chicago merchant bank formed by the 2023 combination of BDT Capital Partners and Michael Dell’s investment office, holds the majority stake it acquired in June 2019. The Dobson family, descendants of founder Harmon Dobson, retains a minority position and board seats.
How much does a Whataburger franchise cost? Whataburger does not publish its Franchise Disclosure Document. Third-party summaries report a total investment of roughly $1.2 million to $3 million per restaurant, an initial fee near $45,000, a 4% to 5% royalty and a 2% to 2.5% marketing fee. The company’s own stated requirements include a $12.5 million net worth and a commitment to open five restaurants in five years. Anyone evaluating the opportunity should work from the current FDD rather than these figures.
How much does a Whataburger restaurant make? The average unit volume was $3,914,000 in fiscal 2025, according to the QSR 50. That ranks fifth among major US burger chains and about 2.36 times Burger King’s per-restaurant volume.
Why is Whataburger only in the South? The chain grew out of Corpus Christi and built Texas to near-saturation before expanding. It reached 17 states by 2025 and closed its California operations back in 1987. Expansion has followed the supply chain and the Sun Belt population, with North Carolina the most recent addition.
Why is Whataburger open 24 hours? The company started 24-hour service at three Corpus Christi restaurants in 1982 and has kept it as a core format. The overnight hours add revenue against fixed occupancy costs, which matters more to Whataburger than to competitors because Whataburger owns most of its restaurants.
Is Whataburger profitable? Whataburger does not publish financial statements. The clearest public signal is the debt: Whatabrands LLC’s 2024 first lien Term Loan B is priced at SOFR plus 250 basis points, a spread lenders reserve for borrowers they consider able to service it, and it appears in the disclosed holdings of institutional mutual funds.
The Business Model Analyst Take
The temptation with Whataburger is to write about the fancy ketchup. The interesting thing is the capital.
For 69 years the Dobson family answered “who pays for the next building” with “we do, when we can afford it,” and the chain added twelve and a half restaurants a year. BDT did not change the burger, the hours or the A-frame. It changed the funding mix, and the pace quadrupled.
The elegant part is the sequencing. Whataburger does not franchise blind markets and it does not company-operate mature ones. It spends its own money exactly where its money is the only money available, in a state where nobody has receipts yet, and then it sells that market once the receipts exist and cheaper capital will show up. Kansas City cost roughly $34 million more than franchising it would have. Whataburger got Kansas City, and then got its balance sheet back.
The risk is that the thing being sold is finite. Whataburger is monetizing 76 years of Texas identity, one state at a time, and identity does not compound. Texas took seven decades and 774 restaurants to build. North Carolina has to be earned on the food, and the eight closures last December suggest that lesson is already arriving.
Watch two numbers. The franchised share of new units tells you whether BDT still believes in its own model. The Texas share of total restaurants tells you how much of the inheritance is left.