
Bob Wright says the chain traded ingredients for savings. The co-op that buys the food has eight franchisee directors and two from Wendy’s, and Wendy’s just sent its U.S. president back to run it.
Wendy’s does not buy its own food. An independent purchasing cooperative called QSCC does, on behalf of roughly 6,400 restaurants in the U.S. and Canada, and Wendy’s holds two of the ten seats on its board. That structure decides whether the quality reset new CEO Bob Wright described to the Wall Street Journal on August 24 gets funded, because a one-percentage-point increase in food cost across the U.S. system costs about $115 million a year and Wendy’s own restaurants absorb $9.6 million of it. The other $105 million lands on franchisees who hold eight of the ten votes.
Wright told the Journal the company shortchanged ingredient quality for cost savings, that service has gone uneven, and that Wendy’s leans too hard on deals. He also announced Tariq Hassan, most recently U.S. chief marketing and customer experience officer at McDonald’s, as chief marketing and customer growth officer in a newly created role. The marketing hire got the headline. The supply-chain move ten days earlier is the one that determines whether the food gets better.
What Happened
Wright sat for a Journal interview on August 24 and laid out a five-point plan covering menu quality and value, branding and marketing, operations, digital, and restaurant economics. He said Wendy’s lost its number-two U.S. burger position because the company made quality decisions rooted in efficiency, let the value equation slip, and became over-reliant on promotional activity. On the same day Wendy’s named Hassan to the marketing role, with U.S. CMO Lindsay Radkoski departing after a transition.
Ten days before that, an August 14 filing disclosed that Pete Suerken intends to resign as president of Wendy’s U.S. business. He leaves August 31 and returns September 1 to Quality Supply Chain Co-op as president and CEO, the job he held from 2021 until Wendy’s promoted him in July 2025. Wendy’s is eliminating the U.S. president position and reviving a global chief operating officer role that has sat empty since 2019, when Wright himself last held it. The company agreed to accelerate vesting on stock units scheduled for 2027 and to pay a pro-rated cash incentive.
The numbers behind both moves came from the quarter ended June 28. U.S. same-restaurant sales fell 7.0%, the sixth consecutive decline, built from traffic down 12.5% and average check up 5.6%. U.S. systemwide sales fell 8.2% to $2,875.8 million. Wendy’s withdrew its 2026 outlook, halved the dividend, and guided to commodity inflation of 5% to 6% for the year. Burger King ran a positive 8.5% U.S. comp in the same quarter, a 1,550 basis point spread. Consumer Edge counts 17 straight months of share loss in the QSR hamburger category.
The Backstory
Wendy’s used to buy its own food. The FY2012 10-K states it plainly: prior to 2010, the system’s purchasing function was performed and paid for by Wendy’s. In the fourth quarter of 2009 the company signed a purchasing co-op relationship agreement with its franchisees and stood up Quality Supply Chain Co-op, Inc., which began operating the following year from Dublin, Ohio, a few minutes from Wendy’s headquarters.
QSCC now manages national contracts for food, proprietary paper, operating supplies and equipment across the U.S. and Canada, with pricing set on total system volume. It runs about $4 billion of buying power across 33 distribution centers, 400-plus suppliers and roughly 1,500 ship-from locations. Vendors pay sourcing fees on products sourced through the co-op and remit them to QSCC, which is how the co-op funds itself. It also collects rebates, price-variance recoveries, technology fees and convention fees from those same vendors. When sourcing fees run ahead of what the co-op needs, its board can return the excess to members.
Wendy’s described its own position in the risk factors of an earlier 10-K: the company appoints two representatives to the QSCC board, participates through its company-owned restaurants, and does not control the decisions and activities of QSCC except to ensure that suppliers meet Wendy’s quality control standards. QSCC says its board runs eight franchisee directors alongside the two from Wendy’s, with one vote per member regardless of how many restaurants that member owns.
Purchasing co-ops are standard in franchised QSR. Yum runs RSCS, where Suerken spent 13 years before joining QSCC. Arby’s has ARCOP. The structure works because it pools volume and keeps the franchisor out of the position of selling goods to its own licensees at a markup. What the structure does not do is make anyone inside it responsible for brand equity three years out.
The Plan
Wright’s five focus areas, as he framed them on the August 14 earnings call and repeated to the Journal, are menu quality and value architecture, branding and marketing that drives demand, operational execution, a digital experience that builds frequency, and restaurants as a growth engine. He told analysts Wendy’s has been leaning on a calendar of one-off promotions and collaborations instead of a consistent brand narrative. He promised a full strategic plan at the next quarterly update.
On menu, Wright wants to rebuild at the ingredient level, the item level and the category level across hamburgers, chicken, salads and the Frosty. On closures, he said Wendy’s has shut more restaurants than it opened over the past twelve months and expects more, framing closures as a tool for franchisees who need help getting their portfolios healthy. On marketing, he cited a budget in the hundreds of millions of dollars and Hassan’s record at McDonald’s, where the campaigns around adult Happy Meals and Grimace’s birthday ran on his watch before he left in January 2025.
Four of those five pillars sit inside Wendy’s own building. Wright can rewrite operating standards, redirect the national advertising fund, ship digital features and approve or refuse a franchisee’s closure request without asking anyone’s permission. Menu quality is the one that has to clear an entity across town.
The Business Model Angle
Wendy’s writes the specification. QSCC buys against it. Splitting those two functions makes cost the variable that gets optimized, because the co-op’s job is delivered cost and the co-op’s members pay it.
Run the arithmetic on what a quality reset costs. Annualize the June quarter and U.S. systemwide sales are about $11.50 billion. One percentage point of additional food cost, measured against sales, is $115.0 million a year. Company-operated restaurants generated $240.0 million of that $2,875.8 million quarterly base, or 8.35%, so Wendy’s own P&L takes $9.6 million and franchisees take $105.4 million. The split is 11 to 1 against the people voting on it.
Translated into the food line, one point of sales is a 3.08% increase in the food and paper basket. Wendy’s 2025 Franchise Disclosure Document puts cost of sales at 32.5% of revenue for 362 traditional company restaurants averaging $2.34 million in sales. That 3.08% arrives on top of the 5% to 6% commodity inflation the company already guided for 2026.
Now the return side, and the reason a franchisor and a franchisee look at the same decision and see different projects. Wendy’s charges a 4% royalty on net sales under its standard traditional agreement, and incremental royalty carries close to no incremental cost. At a 20% flow-through on incremental restaurant sales, one point of U.S. comp is worth roughly $6.14 million to Wendy’s and $21.09 million to franchisees in gross profit. Set that against each party’s share of the $115.0 million bill:
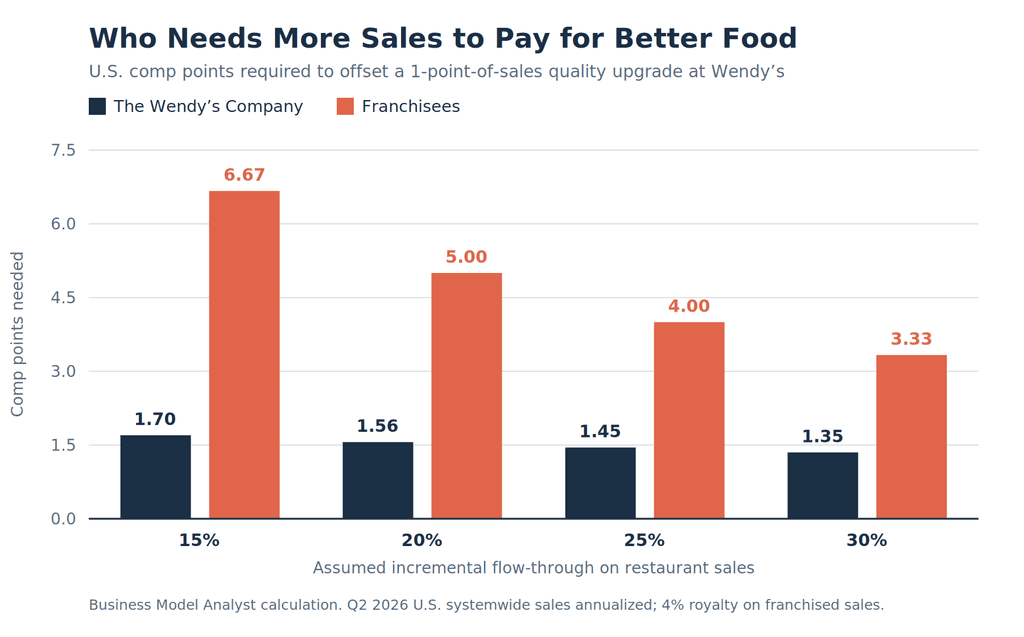
Wendy’s clears a one-point quality investment on about 1.6 points of comp. A franchisee needs 5. Same ingredient, same guest, hurdle rates three times apart, and the party with the higher hurdle holds 80% of the board.
The check line makes it worse. Wendy’s is already running check up 5.6% against traffic down 12.5%, which is arithmetic that produces the 7% comp decline the company reported. Pricing is what emptied the dining rooms. A franchisee who takes on 300 basis points of food basket cannot price for it without accelerating the traffic problem, so the money has to come out of restaurant margin.
Beef makes the timing worse still. Wendy’s built its brand on fresh, never frozen beef, which is the one spec it cannot upgrade because it is already at the top. The U.S. cattle herd sits at 86.2 million head, the smallest since 1951, with the beef cow herd at 27.6 million, the lowest since 1961. Wholesale 85% lean ground beef is up 60.7% since 2022 against 26.6% for tenderloin, so the cut Wendy’s uses inflated faster than the cuts steakhouses buy. USDA projects beef and veal prices up 10.1% in 2026 against 1.3% for pork and 0.3% for poultry. Wendy’s cheapest available quality upgrades sit in chicken and produce, which is where McDonald’s, Burger King and Popeyes are already fighting, as we covered in Burger King’s chef swap.
Set the two August announcements side by side. Hassan inherits a national advertising fund that franchisees are contractually required to fill at 3.5% of net sales, plus 0.5% for local programs, which annualizes past $500 million and which Wright directs. The quality pillar has no fund at all. Wendy’s cut its dividend to free about $53 million a year, a figure we sized per restaurant in Wendy’s Q2 royalty collapse. That entire saving covers 46% of one point of system food cost for one year. Marketing came first because marketing is the pillar that is already funded.
Which brings the Suerken move into focus. Wendy’s most senior U.S. operator, a career supply-chain executive with 13 years at Yum’s co-op behind him, is moving to the seat that negotiates the food, and Wendy’s accelerated equity to let him go. Read it generously and Wendy’s is putting its best-informed person on the interface that matters most. Read it skeptically and the man running the U.S. turnaround looked at the job and took the co-op instead. Either reading points at the same conclusion: the co-op is where the quality decision gets made, and Wright will be negotiating with a board that answers to franchisees.
The Risk
Several things could break this reading.
Wendy’s may fund the upgrade directly. Restaurant Brands answered the same 2022 problem at Burger King with a multi-hundred-million-dollar operator support program, which we broke down in Burger King’s refranchising margin. If Wright’s strategic plan carries a franchisee subsidy line, the hurdle-rate gap narrows and this becomes a capital allocation story instead of a governance one. Wendy’s balance sheet makes that hard, with Trian and Nelson Peltz holding 24.09% and a take-private process running in parallel, but hard is not impossible.
Quality upgrades do not all cost money. Suppliers reformulate, specs get tightened without price changes, and some of what Wright is describing may be execution rather than procurement. Holding temperatures, produce rotation, and bun handling cost labor and attention, not food dollars.
QSCC may be the wrong villain, and it is not clear anyone should call it a villain. The co-op says it never cuts corners and that Wendy’s remains the quality gatekeeper on specifications and supplier approval. The spec decisions Wright criticized were Wendy’s decisions. The co-op executed them, at the price the co-op negotiated, which is what a co-op is for.
Wright has done this before. At Potbelly he rebuilt the menu from the bottom up and put more than 40% of additional sales on the top line within five years, by his own account on the earnings call. That was a company-operated base at the time. He knows the difference.
Quick Questions
Does Wendy’s control what its restaurants buy? It controls the specification and approves suppliers. QSCC negotiates the contracts and the price, and Wendy’s holds two of ten board seats.
Who pays for better ingredients? Franchisees pay about 92 cents of every dollar, because company-operated restaurants generated only 8.35% of U.S. system sales last quarter.
Is this structure unusual? No. Yum uses RSCS and Arby’s uses ARCOP. The structure becomes a constraint when a franchisor wants to raise input costs during a traffic decline.
Why hire a CMO first? The advertising fund is already collected by contract and already sits under Wright’s direction. Quality has no equivalent pool.
What should investors watch? The strategic plan Wright promised for the next quarterly update, and specifically whether it names a dollar figure for franchisee support on food cost.
The Business Model Analyst Take
Asset-light franchising moves capital off the franchisor’s balance sheet. It also moves decisions. Wendy’s spun its purchasing function into a franchisee-governed co-op in 2009 and stopped paying for it, which was itself a decision rooted in efficiency and cost savings, the exact phrase Wright now uses to describe what went wrong with the food.
The lesson generalizes past burgers. If you outsource a function to an entity funded by volume and governed by the people who pay the bills, you have set that function’s optimization target, and it is not your brand. Getting it back costs more than a memo. Wright can hire a CMO in a week because the advertising money is already in the account. Rebuilding the menu requires 5,700 operators to accept a hurdle rate three times his own, in a quarter when their traffic is down 12.5%, while beef runs at a 75-year supply low.
Watch the subsidy line in the next strategic plan. If there isn’t one, the quality reset is a specification document, and specifications do not pay for beef.