
Wendy’s carries $2.80 billion of securitized notes at a blended 3.79% coupon. The indenture lists a change of control among the events that can start rapid amortization, and refinancing the stack at today’s rates costs up to $90 million a year.
Nelson Peltz can afford the equity. Trian and Peltz already own 24.09% of Wendy’s, and the shares closed Wednesday at $8.62, valuing the whole company at $1.64 billion. The obstacle sits one layer down. Wendy’s funds itself through a whole-business securitization, and the cheapest money in that structure was priced in June 2021, when a burger franchisor could borrow at 2.370%. Buying the company is the one action that puts those notes in play.
What Happened
The Financial Times reported Wednesday that Trian Fund Management is assembling a consortium to take Wendy’s private, with a proposal possible within weeks. Reuters and CNBC confirmed the outline through their own sources. Two co-investors surfaced: BlueFive Capital, the Abu Dhabi platform founded by former Investcorp co-CEO Hazem Ben-Gacem, and Flynn Group, the largest restaurant franchisee in the world and one of Wendy’s biggest operators.
Wendy’s opened at $7.50, touched $8.80, and closed at $8.62. Nasdaq halted the stock for volatility during the morning. The move carried the shares to a seven-week high and left them roughly flat for the year. Benzinga Pro put short interest at 43.30% of the float going into the session, which explains part of the violence.
Trian’s fund holds 7.85%. Peltz personally holds 16.24%. A February 2026 filing described the stock as undervalued and disclosed that Trian had approached financing sources and potential co-investors about a range of outcomes, including taking the company private. Wendy’s told the FT it would review any Trian proposal in line with its fiduciary duties, the same formulation the board has used since February.
The timing follows Wendy’s second quarter by five days. U.S. same-restaurant sales fell 7.0%, the sixth consecutive decline. U.S. systemwide sales fell 8.2%. Management withdrew the 2026 outlook and halved the dividend. We covered that quarter in detail in Wendy’s Q2 royalty collapse.
The Backstory
Peltz bought into Wendy’s in 2005 through Trian’s first fund. He spun off Tim Hortons, merged the company into Triarc in 2008 in a $2.34 billion deal, and sat on the board for 17 years. Wendy’s named him chairman emeritus in 2024. Trian executive Peter May and Bradley Peltz still hold board seats.
He has run this play before. In May 2022, Trian disclosed it was exploring a transaction and the stock jumped 14%. Peltz walked away the following year. In September 2024 he sold 2.6 million shares at $20.30. Wednesday’s close is 42% of that price.
Wendy’s spent the interval losing ground. Kirk Tanner left for Hershey in July 2025 after 16 months. CFO Ken Cook ran the company as interim CEO and launched Project Fresh in October, built on four pillars: brand revitalization, operational excellence, system optimization, and capital allocation. System optimization meant closing 5% to 6% of the U.S. estate. Fourth-quarter U.S. comps came in at negative 11.3%. Bob Wright, who ran Potbelly and knows the Wendy’s operation from an earlier stint, took over in May 2026. Steven Cirulis arrived as CFO and chief strategy officer in June.
The Plan
Read the balance sheet before the bid. Wendy’s borrows through Wendy’s Funding, LLC, a bankruptcy-remote subsidiary that has issued senior secured notes since June 2015. The collateral is the franchise agreements, the intellectual property, and much of the real estate. Seven tranches are outstanding.
| Tranche | Coupon | Principal | Anticipated repayment |
|---|---|---|---|
| 2021-1 Class A-2-I | 2.370% | $415M | 2029 |
| 2021-1 Class A-2-II | 2.775% | $622M | 2031 |
| 2018-1 Class A-2-II | 3.884% | $433M | 2028 |
| 2019-1 Class A-2-II | 4.080% | $395M | 2029 |
| 2022-1 Class A-2-I | 4.236% | $97M | 2029 |
| 2022-1 Class A-2-II | 4.535% | $383M | 2032 |
| 2025-1 Class A-2-I | 5.422% | $450M | 2032 |
| Total | 3.789% | $2,796M |
A billion dollars of that stack, 37.1% of it, sits below 3%. Wendy’s priced those notes in June 2021 and they run to 2029 and 2031. Annual cash interest on the whole structure comes to $105.9 million.
Now price the same debt today. Wendy’s refinanced $450 million in November 2025 at 5.422%, and it did that with better comparable sales than it has now and a guidance range it had not yet pulled. Refinance the full $2.80 billion at 6.5% and the interest bill goes to $181.7 million. The increase, $75.8 million a year, is 16.1% of annualized first-half adjusted EBITDA and 96% of one quarter’s operating profit.
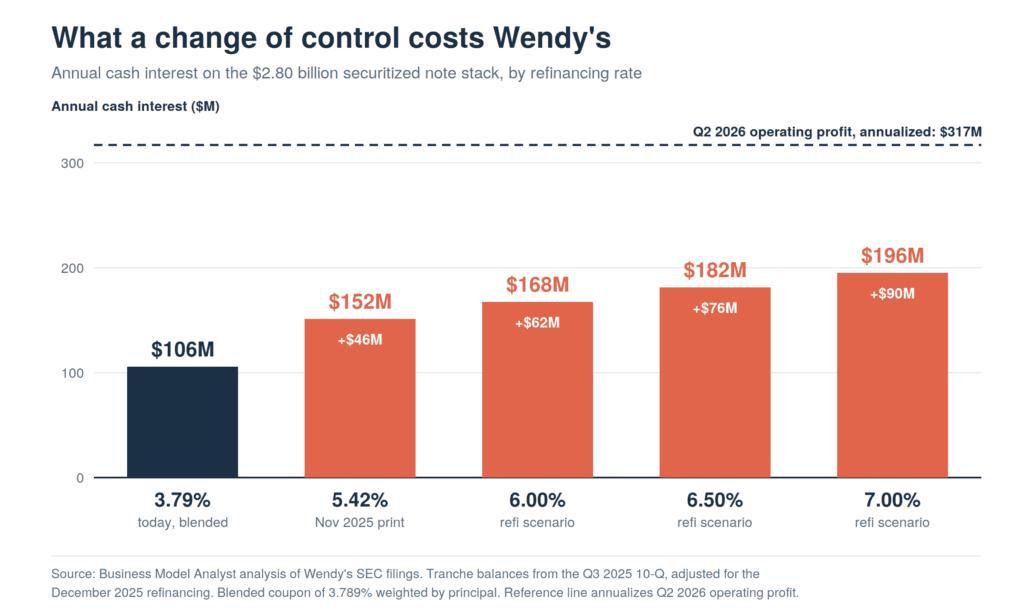
The indenture is where this becomes a deal term rather than a talking point. Wendy’s 8-K on the 2025 notes lists the rapid amortization events: failure to hold stated debt service coverage ratios, global gross sales for specified restaurants falling below set levels on measurement dates, certain manager termination events including in some circumstances a change of control of the company, an event of default, and failure to repay or refinance by the anticipated date. Two of those five are live right now. Global systemwide sales fell 6.5% in the quarter. A take-private is a change of control.
Rapid amortization diverts collection-account cash to noteholders. The equity stops receiving it. Any buyer therefore has to satisfy Midland Loan Services, the servicer that acts as Control Party, and the noteholders behind it, before the independent directors matter at all.
The Business Model Angle
Value the debt as a line item. Discount the coupon differential on each tranche to its anticipated repayment date at 6.5%, and Wendy’s below-market borrowing is worth about $194 million. At $8.62 a share, with Trian and Peltz rolling their 24.09%, the new-money equity check is roughly $1.25 billion. The cheap paper is worth 16% of that check. Most buyout theses argue about margin expansion. This one starts by arguing about a coupon nobody can reproduce.
The equity looks small against the structure.
| Price | Equity value | New-money check | Enterprise value | EV / EBITDA |
|---|---|---|---|---|
| $7.06 (pre-report) | $1,345M | $1,021M | $4,474M | 9.5x |
| $8.62 (Wed close) | $1,642M | $1,246M | $4,771M | 10.1x |
| $10.00 | $1,905M | $1,446M | $5,034M | 10.7x |
| $12.00 | $2,286M | $1,735M | $5,415M | 11.5x |
Net debt plus finance leases runs $3.13 billion, or 6.65 times annualized first-half adjusted EBITDA of $470.8 million, before a buyer adds a dollar. At $10 a share the equity is 38% of enterprise value. Wendy’s helped shrink that stub itself: buybacks retired 12.9 million shares over the past year, 6.33% of the count. The company spent $186.5 million on repurchases in the first half of 2025 and $1.9 million in the first half of 2026, stopping as the stock reached a six-year low. A board that believed its own undervaluation case had $35 million of authorization left and did not use it.
Flynn Group is the piece worth watching. Greg Flynn operates about 317 Wendy’s, 5.5% of the U.S. system, inside a portfolio of roughly 3,000 restaurants generating $5 billion of revenue. At system-average volumes those units throw off about $637 million of annual sales, which sends roughly $23 million of royalty and $28 million of advertising contributions up to the franchisor each year. Put Flynn on the ownership side and part of that $51 million becomes a payment to himself.
Restaurant Brands ran the same trade in the opposite direction when it bought Carrols for about $1 billion and put the franchisor and its largest operator inside one company, which we broke down in Burger King’s refranchising margin. Trian would arrive at the same place through the cap table instead of the balance sheet, and without consolidating a single restaurant P&L. Whoever ends up owning Wendy’s sets the royalty rate, the advertising contribution, the remodel mandate, and the closure list for 5,724 U.S. restaurants. One of the co-investors operates 317 of them. That is a related-party question the independent directors have to answer before they get to price. For the mechanics of who collects what in these systems, see our franchise business model breakdown.
The Risk
The cheap-debt argument has a clock on it. Wendy’s owes $433 million at its 2028 anticipated repayment date and another $907 million in 2029. That is 48% of the stack refinanced at market rates within three years whether or not anyone buys the company. The 2021 vintage buys time, not permanence.
Miss an anticipated repayment date and the penalty compounds. The notes step up by the greater of 5.00% or a Treasury-linked spread over the original coupon. On the 2.370% tranche that is a punitive number.
Then there is the operating case. Royalty income tracks systemwide sales one for one, with no rent layer to cushion it. Another 8% decline in global system sales strips roughly $40 million from the royalty line. Lever that cash flow further and the debt service coverage ratio becomes the binding constraint rather than the marketing budget. Morgan Stanley cut its target to $5.50 on August 10 and rates the stock Underweight. Consensus sits near $7.79, below Wednesday’s close.
The precedent is not encouraging either. LongRange Capital bought Pizza Hut’s business outside China for about $1.5 billion in June, a brand whose U.S. sales had fallen for two years, as we covered in the $2.7 billion Pizza Hut sale. Private ownership removes the quarterly scoreboard. It does not add customers.
Quick Questions
Does a take-private automatically trigger rapid amortization? No. The indenture ties rapid amortization to manager termination events, which in certain circumstances include a change of control. The structure gives the servicer and noteholders a seat at the table rather than an automatic veto.
How much equity does Trian actually need to raise? At $10 a share, about $1.45 billion of new money after rolling the existing 24.09%. BlueFive Capital reported roughly $15 billion under management in April, so the cheque size is not the constraint.
Can the buyer simply leave the debt alone? Only with consent. Even then, $1.34 billion reaches its anticipated repayment date by 2029 and gets repriced at whatever the market charges a franchisor with six straight quarters of declining comps.
Why now rather than in February? The dividend cut freed roughly $53 million a year of cash inside the entity, and the withdrawn outlook removed the forecast the board had been defending. A buyer prefers to negotiate against no guidance.
What does Flynn get out of it? Influence over the fee structure he pays into, plus a claim on the franchisor economics his own restaurants generate.
The Business Model Analyst Take
Asset-light franchising sells itself on the upside. You collect a percentage of someone else’s sales, you carry no restaurants, and the cash converts cleanly. The structure that makes that work is the securitization, and securitization is a bargain struck with lenders about who controls the cash and under what conditions. Wendy’s took the cheap money in 2021 and accepted covenants written for a system with growing sales and a stable owner. It now has neither.
The lesson generalizes past burgers. If you finance a royalty stream against forward system sales, you have sold your lenders an option on your own governance. Ownership changes, sales declines, and manager replacements all become credit events. Founders reaching for cheap structured debt should price that option honestly, because it prices itself later.
Watch three things. Whether Trian files a formal proposal or lets the report stand as a floor under the shares. Whether the servicer signals flexibility on the change-of-control provision. And whether the independent directors run an auction or negotiate with the man whose son sits on their board. For the competitive backdrop, read our Wendy’s SWOT analysis and Wendy’s marketing strategy.
The equity is a rounding error next to the capital structure. The negotiation that decides this deal happens with lenders, not shareholders.