
Investors sold wealth management stocks in February on fear of AI replacing advisors. Six months on, the damage is landing somewhere else entirely.
The short version: Wealth management leaders told CNBC that even high-net-worth clients who can afford top-tier advice are running portfolio questions and tax scenarios through ChatGPT and Claude first. The chatbots get plenty wrong, and the advisors have receipts. But the business model problem is not that AI gives better advice. It is that a client who arrives having already read a competent second opinion is a client who starts asking what the 1% fee buys.
A client walks into a review meeting holding a printout. He wants to know why his portfolio has two ETFs that appear to be the same fund. His advisor explains that one is equal-weighted and one is cap-weighted, that they track the same index but behave differently in a concentrated market, and that the pairing was deliberate. The chatbot got it wrong.
That advisor won the exchange. He also spent the first ten minutes of a paid relationship defending a decision that nobody used to question.
What Happened
CNBC reported on July 30 that wealth management executives are watching clients bring AI chatbots into the advisory relationship. Matthew Fleissig, CEO and cofounder of the registered investment advisor Pathstone, put it bluntly: “ChatGPT is the single largest investment advisor in the world right now”.
The executives interviewed described a pattern rather than a panic. Clients upload trust documents and ask questions about them days later, then get answers containing details the model invented. One advisor watched a chatbot mangle the math on a capital gains question. Another described using large language models to poke holes in a thesis, which works, while noting that on the advice side the output is wrong more often than not.
The privacy problem runs alongside the accuracy problem. A client pasting a trust deed or a 1040 into a personal consumer account is handing over identifying information under consumer terms, not the enterprise agreements that advisory firms sign with strict data controls.
None of that is new information to anyone who has used these tools on a hard problem. What makes the story worth reading twice is the timing.
The Backstory
Investors already made their judgment on this, and they made it fast.
On February 10, 2026, the custodian Altruist announced AI-powered tax planning inside Hazel, its advisor platform. The pitch: read a client’s 1040s, pay stubs, account statements, meeting notes, emails, and CRM records, apply tax logic, and produce a personalized strategy in minutes.
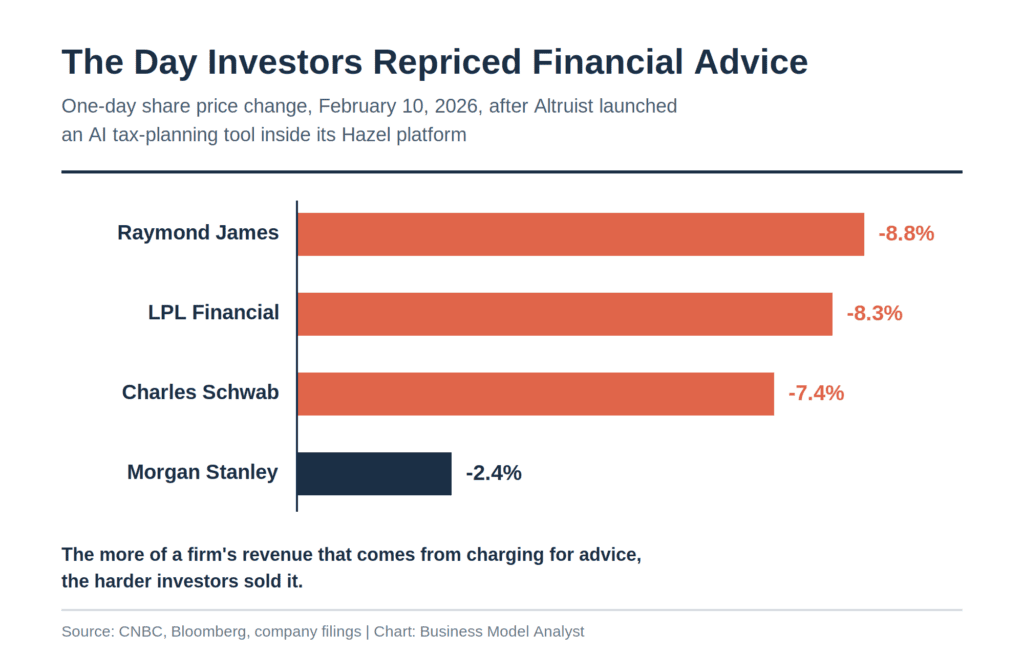
Wealth management stocks fell apart the same day. Raymond James dropped 8.8% for its worst session since March 2020, Charles Schwab sank 7.4%, and LPL Financial lost 8.3%. Morgan Stanley fell 2.4%. The selling crossed the Atlantic the next morning, with St James’s Place down 8.7% and AJ Bell down 5.1% in London trading.
Wall Street had not seen it coming. Charles Schwab was the only one of these names carrying a sell rating, and just one analyst out of 24 held it. The wealth managers were the third sector repriced on AI competition inside two weeks, after software stocks and insurance brokers.
Hazel itself is not expensive. Altruist sells it at $60 per advisor seat per month, and more than 1,000 wealth managers had used the platform since its September 2025 launch. A tool priced at $720 a year per advisor knocked roughly a tenth off the market value of firms that manage trillions.
The Plan
Every large firm is running the same play: adopt the technology internally, keep the human in front of the client.
Morgan Stanley built its advisor assistant with OpenAI and rolled it out to draft follow-up emails, summarize meetings, update the CRM, and pull research from document archives. Citi shipped a client-facing assistant that summarizes financial data and answers basic planning questions, with the scope deliberately narrow. Savvy Wealth built scenario modeling that lets an advisor ask what happens if a client retires at 62 instead of 65 and starts Roth conversions now.
The framing across all of them is identical. The advisor drives, applies judgment, and decides what reaches the client. The model handles the assembly underneath.
Regulators are circling the same line. The UK’s Mills Review, published on July 6, 2026, warned that more than a quarter of British consumers already trust AI systems for financial advice and pushed the Financial Conduct Authority to draw a clearer boundary between generic drafting and regulated recommendation. The FCA has so far declined to write AI-specific rules, preferring to apply existing principles.
The Business Model Angle
Pull apart what a wealth management client pays for and you get four layers stacked under one fee.
Portfolio construction. Commoditized twenty years ago by index funds and again a decade ago by robo-advisors charging 25 basis points. Nobody defends this layer anymore.
Planning and tax work. Labor-intensive, high-margin, and the thing advisors point to when a client asks what justifies the fee. This is the layer Hazel is eating.
Custody, execution, and fiduciary liability. Someone has to hold the assets, place the trades, and be legally accountable when something goes wrong. A chatbot cannot sign a fiduciary duty.
Behavioral coaching. Stopping a client from selling everything in March 2020. Advisors describe this as the human touch, and they are right that it matters in a crisis.
Read the layers in order and the story looks manageable. AI takes layer two, firms keep three and four, margins compress, everyone survives. That is the story the industry is telling, and it is the story Morgan Stanley’s 2.4% decline reflects while Raymond James absorbed 8.8%.
The layer model misses the actual mechanism.
Advisory fees were never priced against the cost of producing the advice. Producing a tax strategy has always been cheap relative to what firms charge for it. The fee was priced against the client’s inability to evaluate the advice independently. You paid 1% a year because you had no way to know whether the plan in front of you was good, mediocre, or self-serving, and the cost of finding out exceeded the fee.
Chatbots collapse that cost to zero. Not because the model is right. Because a client can now generate a plausible, structured, free second opinion in ninety seconds and use it as a yardstick.
Every one of those hallucinated trust details and botched capital gains calculations still does work in the client’s mind. The client does not conclude the AI is unreliable. The client concludes that the topic is contestable, that the advisor’s recommendation is one option among several, and that a conversation is now available where deference used to be.
That is fee compression arriving through a side door. The advisor keeps the client and keeps the assets. The advisor also spends more hours per client, defends more decisions, and finds it harder to raise the fee. Revenue per client stays flat while cost to serve climbs. The industry gets less profitable without ever losing a headline account.
Fleissig’s line about ChatGPT being the largest investment advisor in the world is the clearest statement of the threat, and it is not about assets. OpenAI has no custody, no fiduciary duty, and no AUM. What it has is the position of first consultation, and in advisory businesses the first consultation is where pricing power lives.
The Risk
Three reasons the disruption story could be overstated.
The liability wall is real and it is not moving. Advice becomes regulated the moment it becomes a recommendation, which is exactly why Citi built its client-facing tool narrow and why the FCA is being asked to draw the line. Any AI product that crosses into personalized recommendation inherits suitability rules, disclosure requirements, and legal exposure. The economics of taking on fiduciary liability at consumer software prices do not work.
The clients being disrupted are not the profitable ones. A household with $80,000 in a brokerage account was already lost to Vanguard and Betterment. The households that fund the industry hold complex balance sheets, illiquid holdings, family governance, and estate structures. Those problems are not text problems.
Incumbents own the data. Hazel got its valuation reaction because it sits inside a custodian with real-time account, holdings, and beneficiary records. A general-purpose chatbot working from a pasted PDF has none of that context, which is why it hallucinated the trust details in the first place. The advantage in this market belongs to whoever holds the client’s actual financial state, and that is still the custodians.
Against all three: none of them protect the fee. They protect the relationship. A firm can keep every client and every dollar of AUM and still watch its take rate slide from 100 basis points to 70 because clients now have a free reference point. That is what investors were pricing in February, and the February prices have not been proven wrong yet.
Quick Questions
Are wealthy clients actually replacing their advisors with AI? No. The wealth management leaders CNBC spoke with describe clients using chatbots as a supplement, arriving at meetings better informed and asking harder questions. The relationship holds. The pricing conversation changes.
How accurate is AI financial advice? Mixed, with a dangerous failure mode. Researchers found that chatbot guidance improves savings behavior and long-run stock allocation, while breaking down on job loss scenarios and bending toward whatever the user seems to want. Advisors report hallucinated document details and arithmetic errors on tax questions.
Why did wealth management stocks crash in February 2026? Altruist launched AI tax planning inside its Hazel platform on February 10. Investors read it as evidence that the highest-margin layer of advisory work could be automated at software prices and sold the sector, with the deepest cuts falling on the firms most dependent on advice fees.
What can a human advisor do that a chatbot cannot? Hold assets in custody, accept fiduciary liability, access a client’s real-time financial position across accounts, and stop a panicked client from liquidating during a crash. The first three are structural. The fourth is the one advisors talk about most and the one that is hardest to price.
Should I use ChatGPT for financial advice? As a free financial educator and a way to pressure-test a recommendation, it earns its keep. As a source of personalized instructions to act on, no. Never paste tax returns, trust documents, or account statements into a consumer account, because those terms differ from the enterprise agreements financial firms sign.
The Business Model Analyst Take
The February selloff was correct about the direction and wrong about the mechanism.
Investors sold Raymond James and LPL because they imagined clients firing advisors and hiring software. Six months of evidence says clients are doing something less dramatic and more corrosive: keeping the advisor and checking his work.
Wealth management has spent thirty years surviving fee compression by moving up the value stack. Trading commissions went to zero, so the industry sold portfolio construction. Robo-advisors commoditized portfolio construction, so the industry sold comprehensive planning. Planning is the layer now being automated at $60 per seat per month, and the stack has run out of rungs. What sits above planning is custody, liability, and emotional labor, and none of those support a 1% asset-based fee on their own.
The firms that come out of this intact will be the ones that stop pricing on assets and start pricing on the things AI cannot supply. Fixed retainers for complexity. Fees tied to fiduciary responsibility. Flat charges for family governance work. That transition is painful because asset-based pricing is the most profitable billing structure any professional services industry has ever invented, and nobody abandons it while it still works.
Watch the custodians rather than the advisors. Altruist, Schwab, and Fidelity hold the client’s real financial position, which is the input a chatbot cannot fabricate. The advice layer is being commoditized. The data layer is where the next decade of margin sits, and the firms that recognized this early are the ones building AI inside the custody stack instead of bolting it onto the advisor’s laptop.
One number to keep in view: a tool costing $720 per advisor per year, used by about 1,000 advisors, handed Raymond James its worst trading day since March 2020. Investors are not waiting for proof anymore.
Source: CNBC, “Wealth managers face a new challenger: their clients’ AI chatbots,” July 30, 2026. Additional reporting from Bloomberg, Business Wire, and the UK Financial Conduct Authority’s Mills Review.