
WM owns the one asset in North American waste that nobody can build a second copy of, and it is still the least profitable of the four companies competing for the same tonnage.
That tension runs through every part of this Waste Management SWOT analysis. The company holds 257 landfill sites across the United States and Canada, a network protected by permits that regulators have made close to impossible to replicate. It converts that scarcity into price increases that beat inflation year after year. In 2025 it also grew revenue 14.2% and watched its reported earnings per share fall.
The moat is real. What WM has bolted onto the moat is the open question.
What Is a SWOT Analysis?
A SWOT analysis maps four categories of factors affecting a business. Strengths and Weaknesses are internal, sitting inside the company’s control. Opportunities and Threats are external, driven by markets, regulators and competitors.
The framework earns its keep when you force each entry to point at a number or a decision. A SWOT that lists “strong brand” and “economic uncertainty” tells you nothing. One that lists “9,200 unionized employees against a peer guiding $25M to $50M of strike costs” gives you something to act on. For the method itself, see our guide on how to do a SWOT analysis.
WM at a Glance
| Metric | Full-year 2025 | Full-year 2024 |
|---|---|---|
| Revenue | $25.20B | $22.06B |
| Adjusted operating EBITDA | $7.58B | $6.56B |
| Adjusted EBITDA margin | 30.1% | 29.7% |
| Net income (GAAP) | $2.71B | $2.75B |
| Diluted EPS (GAAP) | $6.70 | $6.81 |
| Diluted EPS (adjusted) | $7.50 | $7.23 |
| Free cash flow | $2.94B | $2.32B |
| Employees | ~60,500 | ~48,000 |
Structure: five reportable segments. Collection and Disposal splits into an East Tier and a West Tier. Recycling Processing and Sales, Renewable Energy, and Healthcare Solutions make up the rest. WM groups everything outside Healthcare Solutions as the “Legacy Business.”
Physical network (Dec. 31, 2025): 257 landfill sites, 342 transfer stations, 113 recycling facilities, 49 organics facilities, 103 landfill gas projects. Also 244 closed sites carrying remediation obligations.
Leadership: Jim Fish retires as CEO on Jan. 4, 2027 after a decade in the job. President John Morris, who ran field operations and served as COO, takes over on the same date.
Strengths
1. The landfill network is a permit monopoly
Scale explains part of WM’s position. Permits explain more of it. Building a new municipal solid waste landfill in the United States means clearing federal, state and local review, surviving public opposition, and funding decades of closure and post-closure obligations before the first truck arrives. Few sponsors finish that process. WM already owns 253 solid waste landfills and four hazardous waste landfills.
The commercial value shows up through internalization. When a WM truck tips at a WM landfill, the company keeps the disposal fee instead of paying it to a rival. Third-party haulers with no disposal of their own pay WM to take their waste. Both flows run through assets that competitors cannot add capacity against.
Customer concentration reinforces it. WM’s largest customer accounted for under 5% of 2025 revenue. Most industrial businesses of this size carry a handful of accounts that can reprice the whole P&L.
2. Pricing runs ahead of cost inflation, by design
WM raised core price 6.3% across Collection and Disposal in 2025 and pulled 3.8% of yield through to revenue. The 2026 plan calls for 5.4% to 5.8% core price. Second-quarter 2026 delivered 5.7%.
Management pairs that with a stated willingness to lose business. The 10-K names it as a strategy risk: refusing lower-margin volume can hurt cash flows. Residential volumes have been falling because WM keeps walking away from contracts that price below its cost to serve. Executives expect residential volume to turn flat or positive around late 2027, once automation lowers the cost base enough to bid competitively again.
Few businesses can shed customers on purpose for three straight years. WM can because the alternative disposal options in most of its markets belong to WM.
3. The cost line keeps improving
Legacy operating expenses fell to 59.2% of revenue in 2025, an improvement of 150 basis points, which WM called its best-ever result. SG&A held at 9.5%.
Technology is doing measurable work here rather than sitting in a slide deck. WM’s SmartTruck platform, which uses route and fleet data to cut miles and stops, reached a $300 million annual EBITDA run rate by mid-2026. Automated recycling facilities run 30% cheaper per ton on labor than the legacy plants they replaced.
4. A capital return record almost nobody in industrials can match
WM raised its quarterly dividend from $0.825 to $0.945 for 2026, a 14.5% increase and the 23rd consecutive year of increases. The board authorized $3.0 billion of buybacks, with roughly $2.0 billion planned for 2026.
5. Succession handled years in advance
WM named Morris president in May 2025, moved Tara Hemmer into the COO seat in May 2026, and announced the CEO transition on Aug. 24, 2026 for a January 2027 effective date. Fish stays on as an adviser into February 2027. Compare that with the abrupt executive departures that have repriced other large caps this year. WM’s board built the bench, tested it in the operating roles, and gave the market four months of notice.
Weaknesses
1. Reported earnings went backwards during the biggest revenue year in company history
WM grew revenue 14.2% in 2025. GAAP net income fell from $2,746 million to $2,708 million, and GAAP diluted EPS slipped from $6.81 to $6.70.
Adjusted EPS tells a different story, rising from $7.23 to $7.50. Both numbers are accurate. The distance between them is what deserves attention: the gap widened from $0.42 to $0.80 in twelve months, close to double.
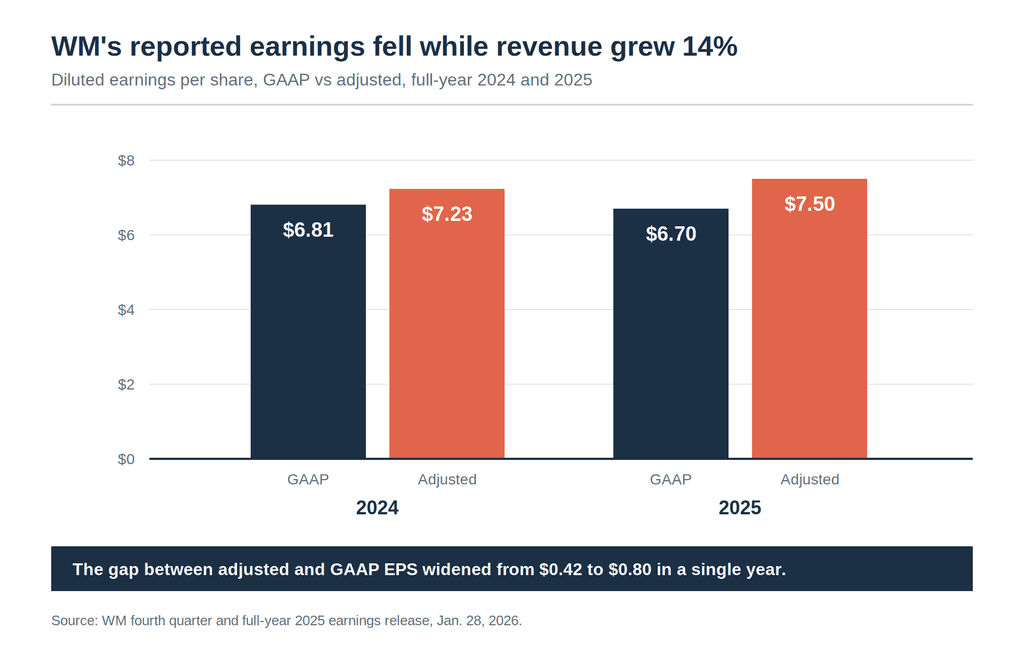
The charges sitting in that gap are Stericycle integration costs, severance and retention, and the healthcare ERP build. WM describes them as one-time. They have now run for two years.
2. WM carries the thinnest margin among the big four
Waste Connections finished 2025 at a 33.0% adjusted EBITDA margin on $9.5 billion of revenue. Republic Services hit 32.0% on $16.6 billion. GFL reached 30.0% on $6.6 billion. WM, at $25.2 billion of revenue, posted 30.1%.
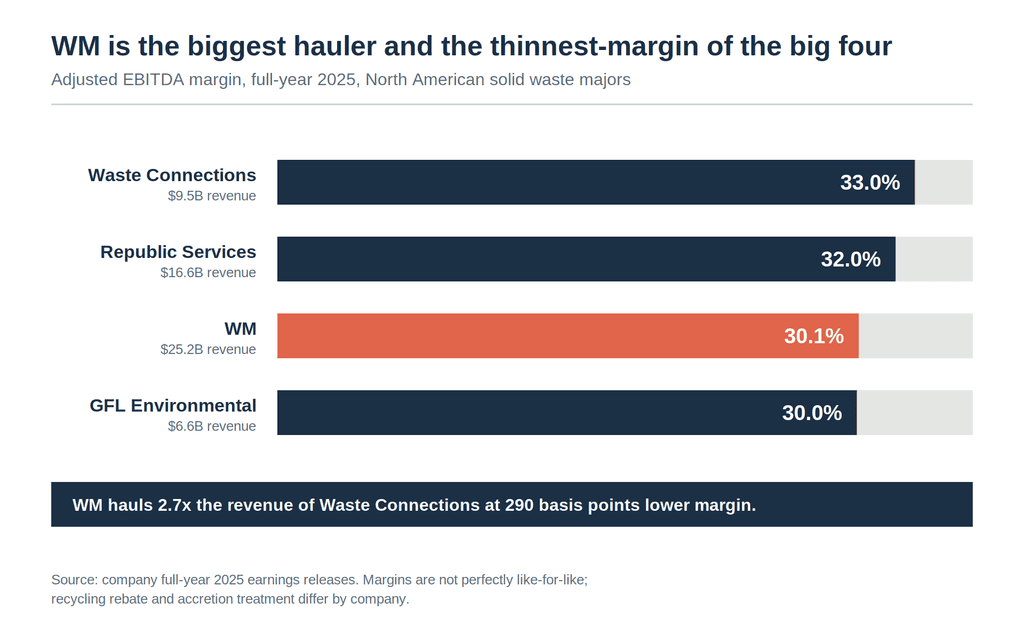
Read this one with care. WM flags in its own release that recycling contract structures produce different accounting for commodity rebates, and that companies diverge on whether they adjust for accretion expense. The comparison is directional. Even allowing for a wide margin of error, the operator with the deepest disposal network and the most route density should not be finishing last on profitability among peers running the same playbook.
3. Healthcare Solutions dilutes the business it was bought to strengthen
WM paid $7.2 billion in enterprise value for Stericycle in November 2024. In 2025, the segment produced $2,508 million of revenue, 9.9% of the company total, and $424 million of adjusted operating EBITDA, 5.6% of the company total.
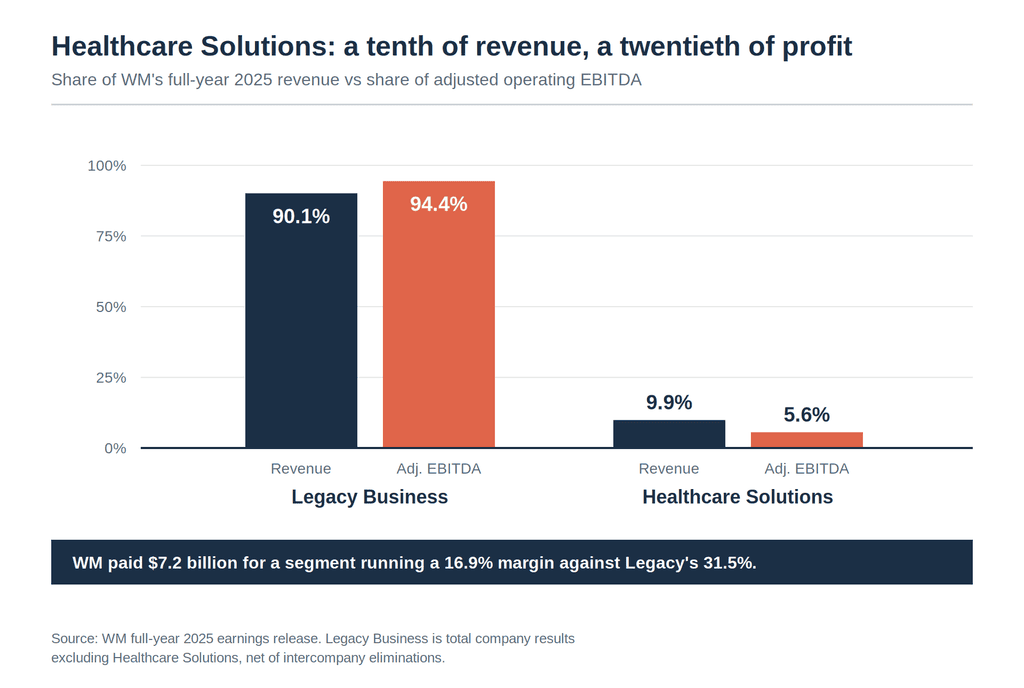
The operating gap is wide on every line:
| Full-year 2025, adjusted | Legacy Business | Healthcare Solutions |
|---|---|---|
| Operating EBITDA margin | 31.5% | 16.9% |
| Operating expenses as % of revenue | 59.1% | 62.8% |
| SG&A as % of revenue | 9.2% | 21.1% |
On 2025 numbers, the purchase price works out to 17.0 times segment adjusted EBITDA. WM’s case is that synergies pull the effective multiple well below its own. Healthcare margins have moved fast, reaching 19% by the second quarter of 2026. The direction is right. The starting point was expensive.
4. Volume has stopped contributing
Collection and Disposal volume came in at 0.1% for 2025, and 50 basis points of that came from wildfire cleanup work in the West. Strip out the fires and volume was negative.
The 2026 picture softened further. WM cut its full-year revenue outlook by roughly 0.6% in July, pointing at weaker volumes and delayed pipeline connections at renewable natural gas plants. Management attributes the commercial weakness to specific national account losses rather than a broad slowdown, and points to special waste growing 4.5%. Growth is now a pricing story with a cost story underneath it.
5. The balance sheet is still recovering from the acquisition
Funding Stericycle pushed net leverage to roughly 3.4 times against a long-term target of 2.5 to 3.0 times. WM suspended buybacks for about fifteen months and only restarted them in February 2026. Republic deployed $1.1 billion into acquisitions in 2025 and GFL nearly $1 billion. WM managed $400 million and guides $100 million to $200 million for 2026.
For a consolidator in a fragmented industry, sitting out the tuck-in market for two years has a compounding cost that no single quarter shows.
6. Safety progress has stalled
WM’s Total Recordable Incident Rate stood at 3.14 at the end of 2025 against a 2030 target of 2.0. The company states plainly that 2025 results did not show significant progress toward that goal. In a business where drivers, equipment operators and sorters make up most of the workforce, incident rates drive insurance costs, permit fitness reviews and retention.
Opportunities
1. The sustainability build is finished and the harvest starts now
WM spent heavily on renewable natural gas plants and automated recycling facilities through 2023 to 2025. That construction phase is closing. Sustainability growth capital drops to about $200 million in 2026, down more than $400 million.
The earnings from those assets keep arriving. Combined adjusted EBITDA from Recycling Processing and Sales, Renewable Energy and landfill gas royalties should grow $235 million to $255 million in 2026, and approach $1 billion in 2027 against a 2023 baseline near $300 million. Six more RNG plants and four more recycling projects come online during 2026.
One caution on how this reaches the cash flow statement. WM guides free cash flow of $3.75 billion to $3.85 billion for 2026 against $2.94 billion in 2025, an increase near $860 million. Capital reductions the company disclosed account for roughly $500 million of it.
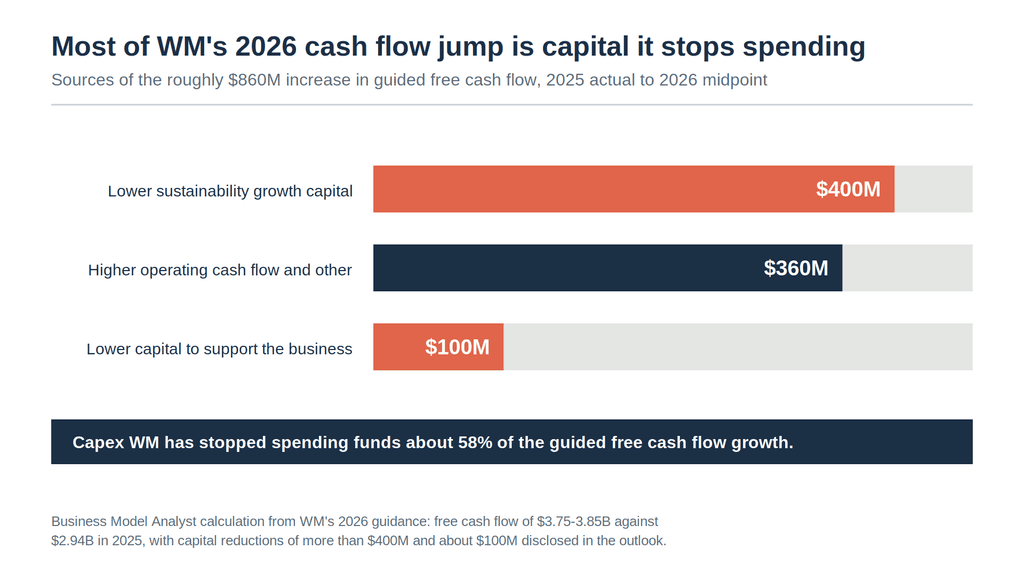
Roughly 58% of the guided cash flow growth comes from spending WM has stopped, not from earnings it has started. That is a planned harvest and WM has been open about the sequencing. It also cannot repeat. The 2027 number has to come from the assets.
2. Healthcare Solutions has $298 million of SG&A still on the table
WM has named its own target: bring Healthcare Solutions SG&A into line with the Legacy Business. The 2025 gap ran 21.1% against 9.2%, or 11.9 percentage points. Applied to $2,508 million of segment revenue, closing that gap in full is worth roughly $298 million of annual operating EBITDA, near 4% of total company adjusted EBITDA.
Nobody closes a gap like that entirely. WM has already cut segment SG&A from 38.5% of revenue in 2024 to 22.8% in 2025, and to 18% by the second quarter of 2026. Cross-selling solid waste and medical waste into the same accounts had secured $32 million of annualized EBITDA against a $50 million target by mid-2026.
3. PFAS regulation cuts both ways
The threat side gets the headlines. WM’s 10-K makes the other argument: tighter PFAS standards are expected to present business opportunities in PFAS management, treatment and disposal. Analysts have sized the treatment market above $100 billion.
Waste generators facing new limits need somewhere compliant to send contaminated material. WM owns four hazardous waste landfills, a deep well injection facility, and treatment capacity that most competitors lack. Regulation that raises the cost of disposal raises the value of permitted disposal.
4. Residential automation is the largest untapped cost pool
Residential collection carries WM’s worst economics and its heaviest labor content. The company is phasing out manual collection in favor of automated systems. Every route converted improves worker safety, cuts headcount per route, and lets WM bid on municipal contracts it currently declines. Management has put a date on it: a path to flat or positive residential volume by mid-to-late 2027.
Threats
1. The PFAS ruling landed against the industry
On Aug. 18, 2026, the D.C. Circuit Court of Appeals rejected the waste industry’s challenge and upheld the EPA’s 2024 designation of PFOA and PFOS as hazardous substances under CERCLA. The National Waste and Recycling Association, the U.S. Chamber of Commerce and others had argued the agency exceeded its authority.
Congress has passed no “passive receiver” exemption. Landfills generate none of these compounds and control none of what arrives in the waste stream, and they now sit inside a strict, retroactive liability regime.
The numbers under discussion are large. NWRA estimated in its comments that removing PFOA and PFOS from landfill leachate would raise costs 400% to 800%, between $966 million and $8.2 billion a year across US municipal solid waste landfills. Publicly owned treatment works have started refusing leachate over PFAS concerns, which leaves operators to handle it themselves. Stifel expects the industry to respond with leachate surcharges modeled on the fuel surcharges already in customer contracts. Whether customers absorb those surcharges is untested.
WM says PFAS management has already raised its landfill operating costs.
2. Renewable energy economics depend on a credit market regulators control
WM’s RNG returns rest on Renewable Identification Numbers under the federal Renewable Fuel Standard, plus state clean fuel credits. The current administration lowered 2024 blending volumes retroactively, proposed cutting 2025, proposed low volumes for 2026 and 2027, and expanded small refinery exemptions.
WM discloses the sensitivity: a $0.10 move in RFS credit value on its uncontracted volumes shifts operating EBITDA by about $6 million. Realized RFS credit prices already fell from $3.05 in 2024 to $2.49 in 2025. WM has contracted 60% of expected 2026 RNG volume at about $27 per MMBtu to blunt this, which caps the upside as well as the downside.
3. Recycling investment increased commodity exposure
Blended single-stream commodity prices fell from $92 per ton in 2024 to $75 in 2025. The 2026 plan assumes about $70. WM states that a $10 per ton move swings total company operating EBITDA by roughly $27 million.
The company has spent years shifting customers from rebate contracts to fee-for-service pricing that recovers processing costs first. That shift limits the damage. It does not eliminate it, and the automation build made the recycling segment a larger share of the whole.
4. Diversion policy attacks the landfill and the gas at the same time
Extended producer responsibility rules, organics diversion mandates, minimum recycled content laws and container deposit schemes all move tonnage away from landfills. Every diverted ton is a tipping fee WM does not collect at its highest-margin asset.
The second-order effect appears in WM’s own 10-K: regulations requiring organics diversion could reduce the volume of landfill gas produced over time, which damages the Renewable Energy segment. WM’s recycling and organics businesses compete for feedstock with the landfill business, and the landfill business supplies the raw material for the renewable energy business. The strategy contains its own headwind.
5. Peers are compounding faster from a better starting point
Republic and Waste Connections both run higher margins, both deployed roughly $1 billion each into acquisitions in 2025, and both face the same PFAS and commodity exposure with less leverage repair to finish. Republic guides 2026 revenue of $17.05 billion to $17.15 billion with adjusted EBITDA of $5.475 billion to $5.525 billion, implying continued margin expansion.
Republic’s own 2025 EBITDA reconciliation included $25 million to $50 million for labor disruptions. WM has about 9,200 employees under collective bargaining agreements out of 60,500. The sector’s exposure to work stoppages is priced, and WM is not exempt.
WM SWOT Matrix
| Helpful | Harmful | |
|---|---|---|
| Internal | Strengths<br>257 landfill sites with near-unreplicable permits<br>Core price of 6.3% against low cost inflation<br>Largest customer under 5% of revenue<br>Legacy opex at a record 59.2% of revenue<br>23 straight years of dividend increases<br>Succession planned and announced early | Weaknesses<br>GAAP EPS fell to $6.70 as revenue grew 14.2%<br>30.1% margin trails all three main peers<br>Healthcare Solutions: 9.9% of revenue, 5.6% of EBITDA<br>Volume flat, and positive only on wildfire work<br>Leverage repair cost 15 months of buybacks<br>Safety rate stuck at 3.14 against a 2.0 goal |
| External | Opportunities<br>Sustainability EBITDA approaching $1B by 2027<br>Up to $298M of Healthcare SG&A convergence<br>PFAS treatment market sized above $100B<br>Residential automation and a 2027 volume turn<br>Fragmented market open to tuck-in M&A | Threats<br>D.C. Circuit upheld PFAS CERCLA designation<br>RFS credit volumes cut for 2026 and 2027<br>$10/ton commodity move equals ~$27M EBITDA<br>EPR and organics rules shrink tonnage and gas<br>Peers buying more, at higher margins<br>9,200 union employees in a strike-exposed sector |
What the SWOT Adds Up To
Two questions sit inside this business and they have different answers.
The first is whether WM’s core asset holds. It does. Landfill permits are getting harder to obtain, not easier. Diversion policy nibbles at volume while raising the value of every remaining permitted ton. WM can price above inflation and shed unprofitable customers because most of its markets have no serious disposal alternative. That position survives PFAS costs, commodity swings and recessions. Waste volumes move with GDP; disposal scarcity does not.
The second question is whether WM allocates capital well on top of that asset. Here the record is mixed. The company spent $7.2 billion on a medical waste business running half the margin of the one it already owned, took its leverage above target, gave up more than a year of buybacks and tuck-in acquisitions, and finished 2025 with lower reported earnings per share than it started with. Meanwhile Waste Connections generated a 33.0% margin on a third of the revenue.
The bull case says the Stericycle margin curve is steep and early, that management has hit its integration marks, and that the sustainability portfolio starts paying in 2027 with the spending already behind it. The evidence supports both points. Healthcare margins reached 19% by mid-2026 from 1.0% two years earlier.
The bear case is that WM keeps buying growth that dilutes returns because organic growth in solid waste has run out of room, and that the 2026 cash flow surge flatters a business whose underlying earnings power grew far less than the headline suggests.
Morris inherits both. His first full year is 2027, the same year the sustainability assets are supposed to deliver close to $1 billion and the capex holiday ends. The gap between adjusted and reported earnings is the number to watch. It closes if the integration is done, or it stays open and the “one-time” label stops meaning anything.
Frequently Asked Questions
Is WM the same company as Waste Management? Yes. Waste Management, Inc. remains the legal name and NYSE ticker WM. The company rebranded to WM in 2022 to reflect a service range that now covers recycling, renewable energy and medical waste alongside collection and disposal.
Why did WM buy Stericycle? WM acquired Stericycle for $62.00 per share, an enterprise value near $7.2 billion including $1.4 billion of net debt, closing Nov. 4, 2024. The argument was that medical waste and secure information destruction grow faster than solid waste, and that WM’s logistics and disposal network could strip cost out of a business running heavy SG&A. WM raised its synergy target from $125 million to $250 million within three months of closing. The segment now operates as Healthcare Solutions.
What is WM’s biggest competitive advantage? Landfill permits. WM operates the largest disposal network in the United States and Canada, and new landfill capacity is close to impossible to permit. Competitors either pay WM to dispose of what they collect or haul it further, which raises their cost per ton. Route density compounds this in markets where WM holds the disposal assets.
How exposed is WM to recycling commodity prices? Less than it once was, though the exposure grew with the automation build. WM discloses that a $10 per ton change in blended single-stream prices moves total company operating EBITDA by about $27 million. Prices fell from $92 per ton in 2024 to $75 in 2025, with 2026 planned around $70. Fee-for-service contracts that recover processing costs before commodity revenue absorb part of the swing.
What does the PFAS ruling mean for WM? The D.C. Circuit upheld the EPA’s designation of PFOA and PFOS as CERCLA hazardous substances on Aug. 18, 2026, leaving landfill operators inside a strict liability regime for compounds they neither made nor chose to receive. Industry estimates put the cost of removing these compounds from landfill leachate at $966 million to $8.2 billion annually across US municipal landfills. WM will likely pass much of this through as surcharges, and its permitted disposal and treatment assets also position it to sell PFAS handling as a service.
Who is taking over as WM’s CEO? John Morris becomes President and CEO on Jan. 4, 2027, succeeding Jim Fish. Morris has spent three decades in the industry, running field operations, corporate strategy and the COO role before becoming president in May 2025. Fish stays on as an adviser through mid-February 2027.
The Business Model Analyst Take
WM sells certainty of disposal, and it owns the scarcest input required to deliver it. That is a rare position, and it explains why the company can raise prices near 6% while losing customers on purpose.
The trouble is that a moat guarantees pricing, not returns. WM has spent the last two years proving that. It deployed $7.2 billion into a segment that earns half the margin of its core, borrowed to do it, then paid for that borrowing with fifteen months of forgone buybacks and a tuck-in acquisition program cut to a quarter of its peers’. Reported earnings per share fell during the largest revenue year the company has ever had, and the distance between what WM reports and what WM adjusts to nearly doubled.
None of that breaks the business. Landfill scarcity is a structural advantage that outlasts management teams, integration charges and commodity cycles. It also means WM will never be punished quickly for capital allocation mistakes, which is precisely why they are worth watching closely.
For operators, the lesson transfers. A defensible core asset creates the temptation to buy adjacent businesses that the core cannot improve. WM’s disposal network cannot make autoclaves cheaper to run. It can only cross-sell the customers, which is real and which WM values at $50 million a year against a $7.2 billion price. If you own something scarce, the discipline is proving that whatever you attach to it earns more inside your business than it did outside.
Morris takes over the year that answer becomes visible.