
Private-equity giant Warburg Pincus is closing in on a deal to buy specialty-pharmacy company PANTHERx Rare for more than $7 billion, including debt, according to a July 10 report from The Wall Street Journal citing people familiar with the matter. The move would hand one of the industry’s most active buyers a foothold in one of healthcare’s fastest-growing corners, and it would do it with a sovereign-wealth partner riding shotgun.
What happened
Warburg Pincus is in advanced talks to acquire PANTHERx Rare, a Pittsburgh-based pharmacy that dispenses medications and coordinates patient care for rare and orphan diseases. The reported price tag of over $7 billion includes debt. The firm is not going in alone: it is partnering with the Abu Dhabi Investment Authority, the sovereign-wealth fund known as ADIA, on the purchase.
As of the WSJ report, nothing was signed. The people cautioned that a deal could come together soon but that timing could still slip, the standard hedge on any transaction that has not crossed the finish line.
The details
PANTHERx Rare is currently owned by an investor consortium that includes private-equity firm General Atlantic, alongside Nautic Partners and The Vistria Group. That group bought the business in 2022 from health insurer Centene Corp., which had acquired PANTHERx in 2020 and then sold it as part of a broader effort to streamline around its core insurance operations. The 2022 sale price was never disclosed.
If the current talks close at north of $7 billion, they would mark a substantial markup on whatever the consortium paid three years ago, and a clean exit for a group of sponsors under the same industry-wide pressure to return cash that everyone else is feeling.
Who is buying
Warburg Pincus manages more than $105 billion and is already a heavyweight in healthcare. Its portfolio in the sector includes the START Center for Cancer Research and sterile-injectable maker Simtra BioPharma Solutions. Adding a rare-disease specialty pharmacy slots neatly into a book already tilted toward high-complexity, high-margin care.
The ADIA partnership is not a first date, either. The two teamed up last year to invest in India’s IDFC FIRST Bank. Pairing a buyout firm with a sovereign-wealth fund on a large check has become a defining feature of 2026 dealmaking, and this fits the template exactly.
The deal also lands in the middle of a busy stretch for Warburg. In recent weeks the firm completed the $8.4 billion take-private of Clearwater Analytics with Permira, backed data-scraping firm Oxylabs at a $3.6 billion valuation, and moved on targets across Japan, Spain, and the UK. PANTHERx would be one more big-ticket entry in an unusually aggressive year.
The context: private equity has to sell, and buy
To understand why this deal is happening now, look at the pressure gauge on the whole asset class. Private equity is sitting on a record logjam of unsold companies. Bain & Company’s 2026 report pegs the backlog at roughly 32,000 buyout-backed businesses worth about $3.8 trillion, with average holding periods stretched to around seven years. A PricewaterhouseCoopers analysis of PitchBook data suggests it could take close to nine years to clear the pile at the current pace.
That backlog cuts both ways. Sponsors like PANTHERx’s owners are desperate to exit and return capital to their investors, whose distributions have run below 15% of net asset value for four straight years, an industry record for stinginess. At the same time, buyers like Warburg are sitting on roughly $1.3 trillion in dry powder that is aging fast and needs to be deployed. The result is a market where sellers and buyers are both motivated, and where quality healthcare assets with durable demand get bid up.
The sovereign-wealth angle is not incidental. Bain noted that funds like ADIA supplied the largest slice of capital for many of 2025’s megadeals, which is why buyout firms’ own dry powder has barely dented the backlog. Warburg bringing ADIA to the table is how big deals get financed in this environment.
By the numbers: why rare disease is the prize
PANTHERx is not just any specialty pharmacy. It sits at the front of a market with a steep growth curve.
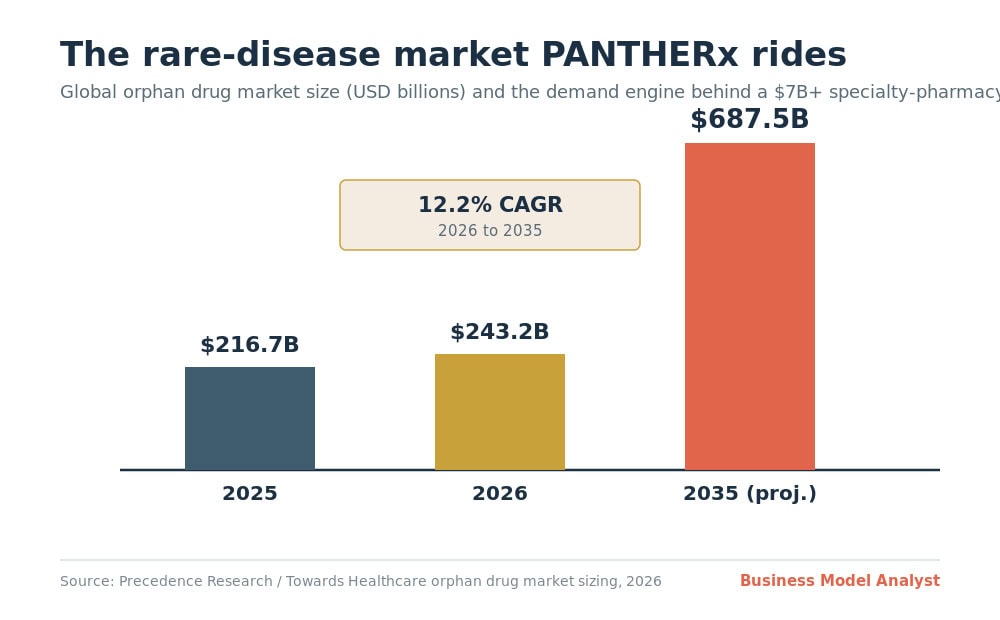
The global orphan drug market was worth roughly $216.7 billion in 2025 and is on track to reach about $243.2 billion in 2026, according to Precedence Research and Towards Healthcare data. By 2035 it is projected to hit $687.5 billion, a compound annual growth rate above 12%. That growth is powered by regulatory incentives baked into the Orphan Drug Act, a wave of biologics and gene therapies, and rare-disease drugs that increasingly carry six-figure annual price tags.
Here is the strategic wrinkle that makes PANTHERx distinctive. The specialty-pharmacy business is dominated by three players, CVS, Cigna, and Optum, which together handle about two-thirds of specialty prescription revenue and are all vertically integrated with pharmacy-benefit managers. PANTHERx is an independent operator focused specifically on ultra-rare and orphan conditions, the complex, low-volume, high-touch cases the giants are less optimized to serve. That focus is exactly what a financial buyer pays a premium for: a defensible niche inside a booming category.
Why it matters
For Warburg, this is a bet that rare-disease demand is structurally recession-proof. Patients with orphan conditions need their medications regardless of the macro cycle, and the therapies keep getting more expensive, which lifts the value of the dispensing and patient-support layer PANTHERx provides.
For the broader market, the deal is a signal. When a top-tier sponsor is willing to write a $7 billion-plus check for a specialty pharmacy, alongside a sovereign-wealth fund, it says the healthcare deal engine is very much running even while other corners of private equity stay frozen. It also underlines a pattern worth watching: capital is flowing toward assets with pricing power and inelastic demand, and away from the software-heavy portfolios now weighed down by AI-disruption fears.
What is next
Watch three things. First, whether the deal actually signs, given the explicit warning that timing could slip. Second, the final structure of the ADIA partnership, which will reveal how much of the equity check the sovereign fund is absorbing. Third, whether this kicks off a run on independent specialty pharmacies, which would be catnip for sponsors hunting healthcare assets that are not already owned by the PBM giants.
There is also a reporting breadcrumb worth noting. The WSJ story was co-written by Mark Maurer, who days earlier published the paper’s deep dive on private equity’s nine-year exit backlog. This deal reads like a live case study in that exact dynamic: a motivated seller, a cash-rich buyer, and a sovereign partner making the math work.
The Business Model Analyst Take
The instinct is to read this as a pharmacy deal. It is really a demand-durability deal. Warburg is not paying up for dispensing logistics; it is paying up for a toll booth positioned in front of the orphan-drug market’s growth curve, in a niche the vertically integrated giants have left comparatively open.
The sharper lesson for operators sits one level down. In a market drowning in private equity capital chasing brands with loyal, inelastic demand, the assets that command premium valuations are the ones with pricing power the buyer does not have to manufacture. PANTHERx has it because rare-disease patients have nowhere else to go and their therapies only get pricier. That is the same thing sovereign funds and buyout firms are learning to prize across sectors, from financial-data platforms to consumer staples: buy the choke point, not the commodity. If you are building a company and want to be the one getting the $7 billion call, the question is not how fast you grow. It is how little choice your customers have.