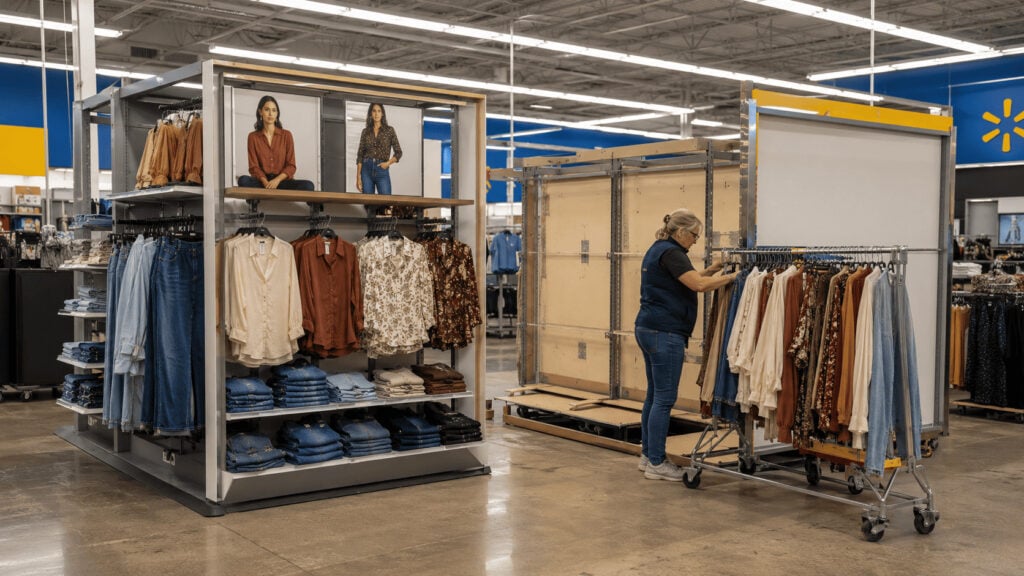

Walmart’s new women’s fashion line launches into floor space it is taking away from Time and Tru, a store brand with over $2 billion in annual sales. That makes Scenario a productivity decision before it is a fashion decision, and it points at the constraint Walmart never talks about in apparel.
Walmart introduced a new women’s clothing and accessories store brand this week called Scenario. Most of it sells for under $25. The line targets women around 35 with a modern bohemian look, natural fabrics, embroidery and pleating details, and it arrived with hundreds of items already on the floor.
None of that is the interesting part.
The interesting part sits one sentence deeper in the announcement. Scenario is going onto shelves that Walmart is taking away from Time and Tru, the women’s brand it launched in 2018, which sells over $2 billion a year and skews toward shoppers 55 and older. Time and Tru survives in a slimmed-down form built around its strongest sellers. Everything else on that fixture makes way.
Walmart did not add a brand. It swapped one.
What Happened
Walmart began rolling out Scenario in stores in the week of 23 August 2026. The assortment covers blouses with embroidered sleeves, pintuck denim shirts, faux leather bags and everyday tops and bottoms. Marcus Brown, a lead designer on the line, described the aesthetic as modern boho, built on cotton and other natural fabrics. Walmart treats the sub-$25 tag as its opening price point for the category.
The launch lands four days after Walmart reported its weakest quarterly comparable sales growth in more than six years. Walmart U.S. comps came in at +2.6% against consensus near 3.7%, and the stock fell 9.15% to $103.84 on 20 August, its worst session since May 2022. We covered the measurement problem underneath that number in Walmart’s comp sales and the store-fulfilled metric.
Denise Incandela, executive vice president of fashion for Walmart U.S. since 2021, framed the launch as additive rather than a retreat from basics. She told the Journal this is an “and” strategy, with socks, underwear, denim and T-shirts still carrying the volume.
The floor plan says something narrower. Time and Tru gets less space. Scenario gets what it loses.
The Backstory
Walmart has been trying to sell more clothing for a decade, and it has tried it two different ways.
The first way was to buy it. Between 2016 and 2018, under then e-commerce chief Marc Lore, Walmart acquired Shoebuy for roughly $70 million, Moosejaw for about $51 million, ModCloth, Bonobos for $310 million, Bare Necessities and Eloquii for a reported $100 million. Those five apparel and footwear businesses represent at least $531 million of disclosed purchase price, and that excludes ModCloth and Bare Necessities, whose prices Walmart never published.
Walmart has since sold all of them. It published the exit price for exactly one. Bonobos went to WHP Global and Express in April 2023 for $75 million, a 76% markdown on what Walmart paid six years earlier. ModCloth left in 2019, Bare Necessities in 2020, Moosejaw and Eloquii in 2023, all at undisclosed terms, which is its own kind of disclosure.
The second way was to build it. Time and Tru launched in 2018 alongside Terra & Sky for plus sizes and Wonder Nation for kids. Scoop followed in 2019 as a trend brand, Free Assembly in 2020 for younger adults. Walmart opened a fashion design office in New York that now runs around 165 designers, brand managers and digital merchants. It starts selling its first store-brand cashmere sweaters this fall. Internally the team stopped saying apparel and started saying fashion, and the word is going onto the signage in renovated stores.
The organizing number behind all of it came from a slide Incandela put up in a Bentonville conference room nearly ten years ago, in front of Doug McMillon and the U.S. store leadership. Eighty percent of what Walmart’s own shoppers spent on apparel, they spent somewhere else. The customer was already in the building and buying clothes at a higher price point down the road.
Walmart could not buy its way into that wallet. It is now trying to design its way in.
The Plan
Scenario reads as a targeted demographic replacement rather than a move upmarket.
Time and Tru sells slightly elevated basics to a customer who is now, on average, over 55. That customer is not leaving, and Walmart is not chasing her out. It is holding her with a tighter assortment of proven sellers, classic tees and dresses, while handing the surrendered linear feet to a brand aimed twenty years younger at the same price.
Nothing in the pricing moved. Time and Tru sits at opening price points. Scenario sits at opening price points. Walmart’s genuine reach for a higher-priced shopper runs through Free Assembly, Scoop, the celebrity partnerships and the cashmere program, and none of that is what launched this week.
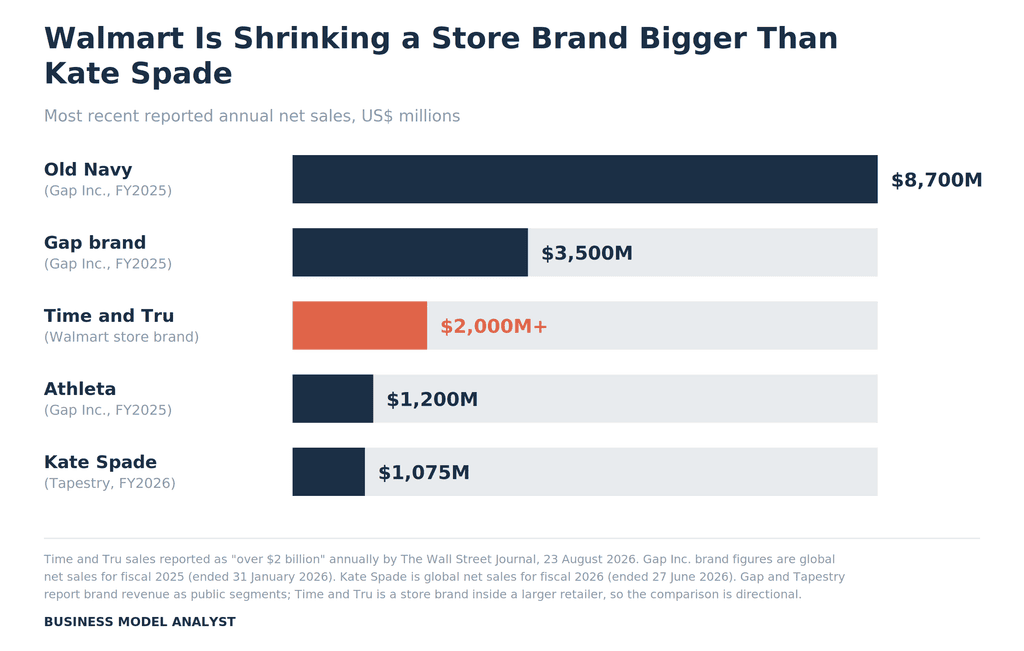
Put Time and Tru next to the brands its customer might otherwise shop and the size of the decision becomes visible. Over $2 billion in annual sales puts a Walmart store brand ahead of Athleta at $1.2 billion and Kate Spade at $1.07 billion, and at roughly a quarter of Old Navy. If Time and Tru traded on its own, it would be a mid-cap apparel company. Walmart is voluntarily making it smaller.
Set against Walmart’s total U.S. apparel and footwear business, which Wells Fargo has estimated at roughly $32 billion, Time and Tru accounts for something in the neighborhood of 6%. Large enough to matter, small enough to experiment on.
The Business Model Angle
Walmart U.S. did $482.98 billion of net sales in fiscal 2026. Capital is not the binding constraint on this launch. Neither is brand development, since Walmart has proven it can stand up a store brand and get it to $2 billion in seven years.
The binding constraint is linear feet.
Every Walmart supercenter runs a fixed planogram. A women’s apparel fixture holds what it holds. Walmart’s own merchant organization allocates that space on productivity, gross margin return on inventory investment, sales per foot, turns, and a line review either wins space or gives it up. Adding a brand to that fixture is a decision to take space from something already earning on it. There is no version of a Scenario launch that does not begin with a Time and Tru markdown.
That reframes what Walmart is actually betting. This is not a bet that Scenario will sell. It is a bet that a dollar of Scenario turns faster than the dollar of Time and Tru it replaced. Illustratively, if Time and Tru gives up half its fixture and a third of its sales, roughly $670 million walks off the floor before Scenario books its first incremental dollar. Everything Scenario does below that line is substitution.
The second half of the bet is harder. Fashion risk and basics pricing do not normally travel together.
A white T-shirt never goes out of style, so a retailer can buy it deep, carry it across seasons and sell it at a thin markup with almost no obsolescence. Embroidered blouses and pintuck denim shirts have a shelf life measured in months. Retailers who sell that kind of product pay for the miss rate with initial markup: they price high enough that the markdowns on the losers come out of the winners. That is the trade the entire specialty apparel industry makes.
Walmart is declining the markup half. Most of Scenario stays under $25, which Walmart calls its opening price point and which Incandela’s team has no intention of raising. Compare that with what we found running the price arithmetic in Ralph Lauren, Coach and the price ladder, where the American brands funded their fashion risk by taking selling prices up roughly 12% a year.
So Walmart is importing fashion risk without importing fashion margin. The only thing that squares that is a lower miss rate, and a lower miss rate is what 165 people in a New York design office are supposed to buy. The design organization is the asset here. Everything else is merchandising.
Walmart already learned that lesson expensively. Buying Bonobos bought a brand, a customer list and a P&L. It did not buy the ability to originate product that Walmart’s own shopper wanted. Hiring the designers does.
The Risk
Walmart’s clothing and accessories sales have grown for seven consecutive quarters, and executives say the company is taking share from department stores and specialty apparel chains. Both statements can be true while Walmart loses the war.
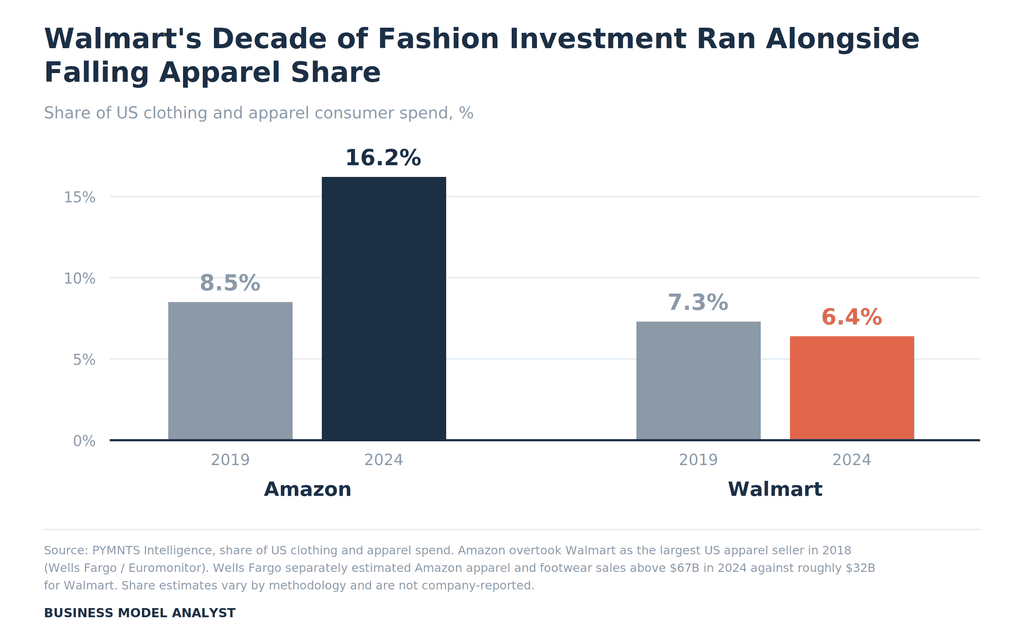
PYMNTS Intelligence put Amazon at 16.2% of U.S. clothing and apparel spend in 2024, up from 8.5% in 2019. Walmart went the other direction over the same window, from 7.3% to 6.4%. Wells Fargo sized Amazon’s apparel and footwear business above $67 billion in 2024 against roughly $32 billion for Walmart, and expected Amazon to clear $72 billion in 2025. Amazon passed Walmart as the largest U.S. apparel seller back in 2018, the same year Time and Tru launched.
Walmart has grown apparel dollars through the entire fashion push and lost apparel share through the entire fashion push. The market grew faster than Walmart did, and Amazon collected the difference. Read the seven-quarter streak against that and it describes a company running to stay in place. We walked through the underlying competitive position in the Walmart SWOT analysis and the head-to-head in Walmart vs Amazon.
Three other things could break this.
The 80% number is old. Incandela presented it before she had the fashion job, which puts it somewhere around 2016 or 2017. Walmart’s share of apparel spend has fallen since. The wallet gap may still be real, but it has had a decade to move, and nobody has published a refreshed version of it.
Trend brands age. Time and Tru launched in 2018 as the modern, trendier alternative to Faded Glory and White Stag. Eight years later it is the brand that skews 55-plus and gets its space taken. Scenario inherits that clock the day it ships. If Walmart has to rebuild a women’s brand every seven or eight years, the design office is a permanent operating cost rather than a one-time investment, and it has to earn its keep every season.
Walmart is refusing the pricing lever twice. Nonfood carries better margin than grocery, which is the stated reason to push here. Holding the assortment under $25 caps how much of that margin Walmart can collect. Tapestry got Coach’s gross margin from 70.2% to 78.8% over seven years by raising selling prices and cleaning up distribution, and its sister brand Kate Spade, which kept discounting, went nowhere. We ran that comparison in Coach vs Kate Spade. Walmart has picked the harder version of the problem on purpose.
Quick Questions
Is Walmart discontinuing Time and Tru? No. Walmart is reducing its assortment to its best-selling items, including classic T-shirts and dresses, and giving the freed space to Scenario. The brand stays on the floor at a smaller footprint.
How big is Time and Tru? Over $2 billion in annual sales, per The Wall Street Journal. That is larger than Athleta ($1.2 billion in Gap Inc.’s fiscal 2025) and larger than Kate Spade ($1.07 billion in Tapestry’s fiscal 2026).
Is Scenario a move upmarket for Walmart? No. Most items sell under $25, which Walmart describes as its opening price point. Walmart’s higher-priced fashion sits in Free Assembly, Scoop and its celebrity collaborations, plus a store-brand cashmere program launching this fall.
Why is Walmart pushing apparel now? Nonfood categories carry higher gross margins than grocery, and Walmart does not already dominate them. After the weakest comp growth in over six years, executives have pointed at fashion as one of the few places left with meaningful room to grow.
How does Walmart’s apparel business compare with Amazon’s? Amazon overtook Walmart as the largest U.S. apparel seller in 2018. Wells Fargo estimated Amazon’s apparel and footwear sales above $67 billion in 2024 against roughly $32 billion for Walmart, and Walmart’s share of U.S. apparel spend has been falling since 2019.
Did Walmart’s earlier fashion acquisitions work? Walmart bought at least five apparel and footwear businesses between 2016 and 2018 for a disclosed $531 million or more and has sold all of them. It published the exit price for one: Bonobos went for $75 million in 2023 against $310 million paid in 2017.
The Business Model Analyst Take
Scenario is a good test of a question most founders never ask themselves, because they assume the answer is unlimited.
What is your fixed resource?
Walmart has $11.5 billion of cash, $19.7 billion of first-half operating cash flow and a $30 billion buyback authorization. Money is not scarce. Store count is not scarce. What is scarce is the number of garments that will physically fit on a women’s apparel fixture inside 4,600 supercenters, and that number has not changed since 2018. Any new brand Walmart wants to sell has to be paid for in floor space taken from a brand already selling.
That constraint produces a hurdle rate most people never calculate. Scenario does not have to succeed. It has to beat the sales per foot of a $2 billion incumbent, and only the amount by which it beats that incumbent counts as growth. A launch that does $800 million in a fixture that gave up $670 million produced $130 million.
Founders make this mistake at every scale. Your fixed resource might be shelf space, but it is more often the homepage above the fold, the three slots in the onboarding flow, the ten hours a week your best salesperson spends selling, or the attention your existing customers will give you before they tune out. Adding the fifth product line to a sales deck does not add a fifth line of revenue. It reallocates the pitch time that was selling the other four.
Before you launch anything, name the resource it consumes and find out what that resource currently earns. If the new thing cannot beat the old thing per unit of the constraint, you have not launched a product. You have redecorated.
Walmart, for what it is worth, appears to know exactly which number it is looking at. It stopped trying to buy taste after losing roughly three quarters of its money on Bonobos, hired 165 people to make it instead, and is now running the swap on its own shelf where it controls the outcome. The bet is disciplined. Whether the modern boho blouse turns faster than the cardigan it replaced, Walmart will find out by Christmas.