Walmart sells goods at thin margins to assemble the largest recurring audience in American retail, then sells access to that audience back to brands through Walmart Connect, VIZIO connected TV, and Walmart+ memberships. Everyday Low Price is the acquisition cost. Advertising and membership fees are the profit. In fiscal 2026 those two lines produced roughly a third of Walmart’s operating income on $6.4 billion of global ad revenue, growing 46% against 4.7% total revenue growth.
Most analyses of Walmart’s marketing still describe a discount retailer that runs TV spots about rollbacks. That version of the company stopped being accurate around the time Walmart bought VIZIO.
Walmart closed fiscal 2026 on January 31, 2026 with $713.2 billion in revenue, $150.4 billion in global e-commerce sales, and a market capitalization above $1 trillion, the first brick-and-mortar retailer to cross that line. The stock moved to Nasdaq in December 2025. John Furner replaced Doug McMillon as CEO in February 2026. Seth Dallaire, who ran advertising at Amazon before becoming chief revenue officer at Instacart, was elevated from Walmart U.S. to enterprise Chief Growth Officer in the same reshuffle.
That last appointment tells you more about Walmart’s marketing strategy than any campaign it ran last year.
What Walmart’s Marketing Strategy Actually Is Now
The old framing treats Walmart as a buyer of advertising. The company still buys plenty. The interesting half of the P&L is the other direction.
Walmart serves approximately 280 million customers and members a week across more than 10,900 stores in 19 countries. Those shoppers generate purchase data that no publisher, streaming service, or social platform can match, because Walmart sees the transaction rather than inferring it. Brands pay for that. In fiscal 2026 they paid $6.4 billion globally, up 46% year over year.
Compare growth rates and the shape of the strategy becomes obvious.
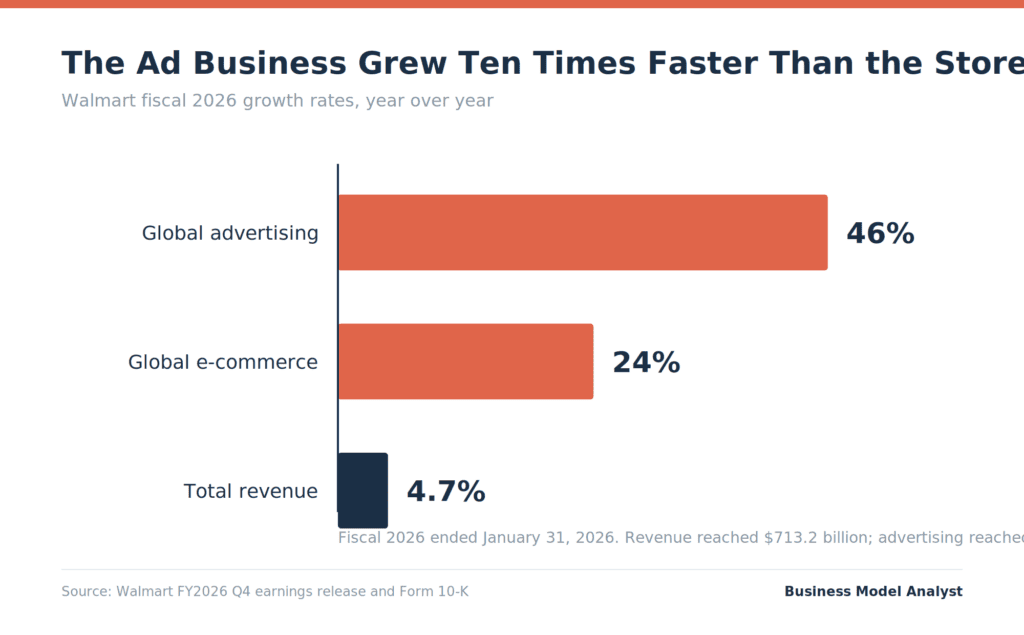
Retail sales grew 4.7%. The media business attached to those sales grew 46%. CFO John David Rainey put the consequence plainly on the Q1 fiscal 2027 call: membership and advertising together make up roughly a third of Walmart’s earnings.
That is the strategy. Everything else is implementation.
The Flywheel, Stated Without Euphemism
Walmart’s marketing engine runs on four moves that reinforce each other:
- Price low enough to keep traffic non-negotiable. EDLP is not a positioning claim, it is a traffic guarantee. Walmart prices items low every day so customers stop comparison shopping, which stabilizes visit frequency.
- Convert traffic into logged-in, identified shoppers. Pickup, delivery, the app, and Walmart+ turn anonymous store visits into accounts with purchase history attached.
- Sell that identified audience to brands. Walmart Connect, the Walmart DSP, and VIZIO’s SmartCast operating system monetize the audience at software margins.
- Recycle the ad profit into lower prices and faster delivery, which protects step one.
Rainey has said the growth of higher-margin businesses gives Walmart room to absorb tariff and cost pressure without raising shelf prices. Ad dollars subsidize price leadership. Price leadership generates the audience that produces ad dollars.
Walmart Connect Is Accelerating, Which Is the Unusual Part
Retail media businesses normally decelerate as they mature. The easy inventory sells out, the CPCs compress, growth reverts toward category growth. Walmart Connect has done the opposite for five straight quarters.
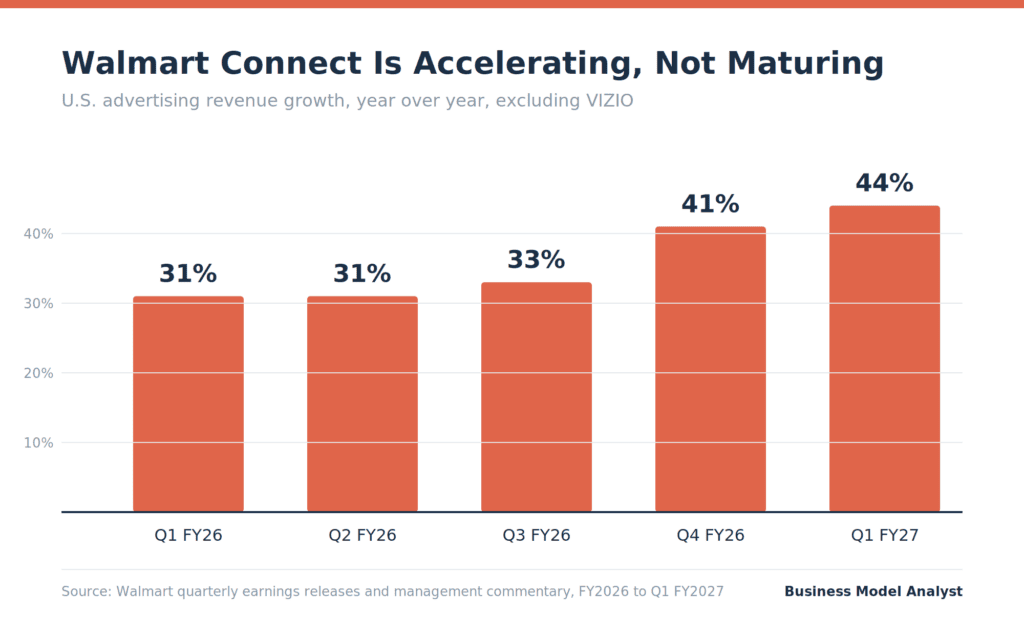
Three things drive the acceleration.
Marketplace sellers. Walmart’s third-party marketplace grew net sales close to 50% in Q1 fiscal 2027, and marketplace sellers increased advertising spend by more than 50%. Sellers who do not own shelf space have to buy attention, which makes marketplace expansion an advertising demand engine.
VIZIO. Walmart paid roughly $2.3 billion for VIZIO in December 2024 and folded its SmartCast connected TV platform into Walmart Connect. Dallaire has described the TV hardware business as sitting adjacent to the ad business, which is a polite way of saying Walmart sells televisions near cost to own the operating system inside them. Walmart already moves about a third of U.S. television units. At NewFronts in March 2026 the company announced a unified account login for new VIZIO OS and onn. TVs, so a Walmart account will follow customers into the living room.
Non-endemic advertisers. CTV inventory brought in automotive, financial services, and quick-service restaurant brands, some of which became the largest spenders on the Walmart DSP. Those categories sell nothing at Walmart. They buy the audience anyway.
Where the Profit Comes From
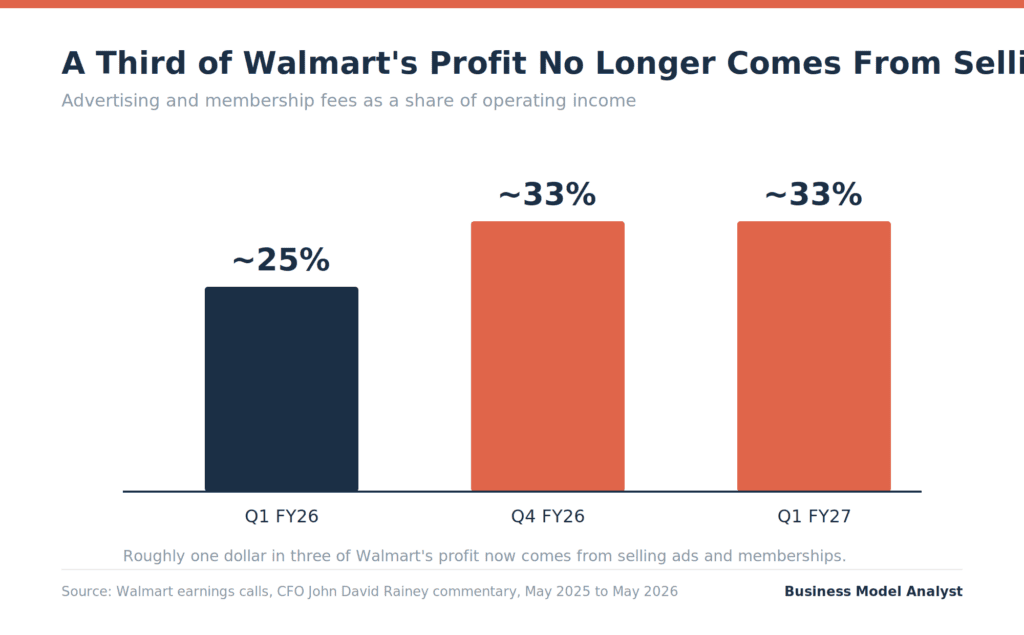
Walmart U.S. posted $483.0 billion in net sales and $25.2 billion in operating income for fiscal 2026, an operating margin of 5.2%. Selling groceries is a 5% business. Selling sponsored placements is a software business with near-zero marginal cost, which is why $6.4 billion of ad revenue can move a third of the profit line at a company with $713 billion of revenue.
U.S. e-commerce turned profitable in every quarter of fiscal 2026, with double-digit incremental margins. Advertising is the mechanism that made the turn possible. Walmart did not fix online unit economics by shipping cheaper. It fixed them by attaching a media business to the order.
Target Audience: The $100,000 Household
The most consequential shift in Walmart’s marketing is who walks in.
Furner told investors in February 2026 that the majority of Walmart’s share gains came from households earning more than $100,000. Executives have repeated the point across several quarters. Moody’s Analytics chief economist Mark Zandi estimates that the top 20% of earners now account for nearly 60% of consumer spending, up from roughly half in the early 1990s.
For a retailer built on serving the bottom two-thirds of the income distribution, that concentration is an existential marketing problem. Walmart’s answer has been assortment rather than repositioning.
| Move | Date | Signal |
|---|---|---|
| Devil Wears Prada Scoop collection | January 2026 | Fashion credibility through licensed cultural IP |
| Great Value brand redesign | April 2026 | Modernizing the largest food and consumables CPG brand in the U.S. |
| Caraway kitchenware partnership | July 2026 | Premium DTC home brands on Walmart shelves |
| Premium musical instruments on Marketplace | January 2026 | Marketplace as the upmarket assortment vehicle |
| bettergoods private label | Ongoing | Elevated food at private-label prices |
Walmart has not changed its price message to attract affluent shoppers. It changed what an affluent shopper can find at those prices. The Walmart+ program does the same job on the convenience axis, bundling free delivery, fuel discounts, Scan & Go, and early access to events like the June 2026 Walmart Deals week.
The commercial logic is circular in Walmart’s favor. Higher-income households buy more general merchandise, general merchandise carries better margins than grocery, and better margins fund the price investments that hold the original customer base. Affluent shoppers also make the advertising audience more valuable, because brands pay premium CPMs for households with discretionary income.
The Marketing Mix, Rebuilt
The 4Ps still work as a scaffold. The content inside them has changed.
| Element | The 2019 version | The 2026 version |
|---|---|---|
| Product | Broad assortment, national brands, private label | Assortment plus a marketplace, plus advertising and fulfillment services sold to suppliers, plus data products |
| Price | EDLP, rollbacks, price matching | EDLP funded partly by ad profit rather than by supplier squeeze alone |
| Place | Supercenters, Neighborhood Markets, Sam’s Club | Stores as fulfillment nodes, plus walmart.com, plus the app, plus VIZIO TVs, plus ChatGPT and Gemini |
| Promotion | TV, circulars, seasonal events | Retail media sold to brands, owned CTV inventory, AI-assisted shopping, membership perks |
Two of those changes matter more than the rest. Place now includes screens Walmart does not own, and Promotion is a revenue line rather than a cost line.
The Agentic Commerce Problem
Walmart’s fiscal 2026 Form 10-K names the risk directly. The company writes that customers increasingly shop through emerging agentic platforms, and that the growing role of AI-enabled platforms in product search, discovery, advertising, and purchasing could reduce store traffic and cut into the cross-selling opportunities that traffic creates.
Read that as a marketing department describing the possible end of its own funnel. If an AI agent selects the paper towels, the endcap does not matter, the sponsored placement does not matter, and the impulse buy on the walk to the register never happens.
Walmart’s response has been to become the agent rather than be indexed by one.
The company partnered with OpenAI in October 2025 so shoppers could buy through ChatGPT’s Instant Checkout. It did not work. Instant Checkout converted at roughly a third of the rate Walmart sees on its own site, with wrong items landing in carts and no sales tax handling. Walmart killed the integration.
In March 2026 it replaced the arrangement with something better for Walmart. Sparky, Walmart’s own shopping agent, now runs inside ChatGPT as an app experience, with a Gemini integration following. Customers link their Walmart account, and Walmart keeps the transaction, the data, and the post-purchase relationship. Daniel Danker, Walmart’s EVP of AI acceleration, framed it as shopping starting anywhere while the Walmart experience stays constant.
Sparky’s weekly active users more than doubled during Q1 fiscal 2027. Walmart also built Marty, an AI assistant on the advertiser side of Walmart Connect, which creates new sponsored surfaces inside conversational interfaces.
The strategic read: Walmart is treating AI assistants as distribution channels it must appear inside, not as a search box it can optimize for. Any brand that sells through Walmart should assume the same rules apply one layer down.
Competitive Position in Retail Media
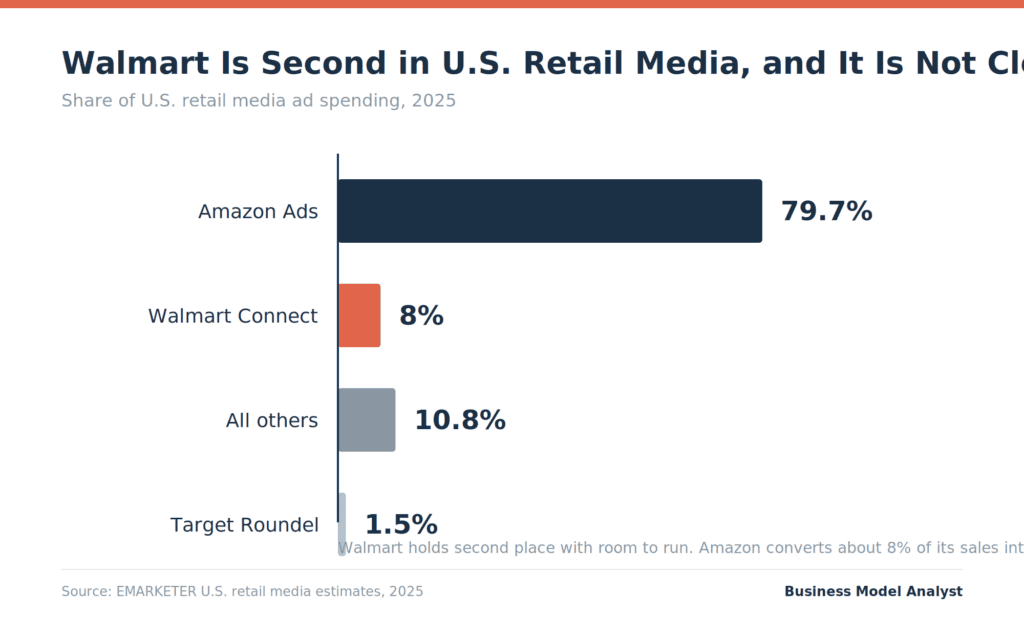
EMARKETER put Amazon at 79.7% of U.S. retail media spending in 2025 and Walmart Connect at 8.0%, more than five times Target Roundel’s 1.5%. EMARKETER also forecasts Amazon and Walmart to capture 89% of incremental retail media spending in 2026, so the category is consolidating around two players.
Second place with an enormous gap is a comfortable position here, because the relevant number is not share but conversion of sales into ad revenue. Amazon monetizes roughly 8% of its sales as advertising. Walmart monetizes about 0.9%. Rainey has told analysts the company has a long way to go to reach best-in-class competitors, which is the polite version of saying Walmart could plausibly quadruple this line without inventing anything new.
The constraint is inventory quality, not demand. Walmart search results and product pages have finite ad slots before the shopping experience degrades, which is why VIZIO, in-store screens, and off-site DSP inventory matter so much.
The Case Against This Strategy
A page that only lists what is working is a brochure. Four real objections:
Ad load is a tax on the shopper. Every sponsored placement pushes an organic result down. Walmart built its brand on trust that the price is the best available price. Sponsored search results are, by construction, not the best result but the best-paying one. Push far enough and Walmart erodes the trust that makes the audience valuable.
The high-income customer is rented, not owned. Affluent households arrived during a period of tariff-driven price sensitivity and concentrated spending power. Analysts including Forbes contributors have framed Walmart’s gains as an adaptation to a K-shaped economy. If discretionary income broadens again, some of those shoppers go back to Target, Costco, and specialty retail.
Agentic commerce could commoditize the storefront. Walmart’s own risk disclosure makes the point. Winning a slot inside ChatGPT and Gemini today does not guarantee favorable placement tomorrow, and the platform owner sets the rules.
Advertising profit masks retail performance. When a third of operating income comes from two high-margin lines, the merchandising business can weaken without showing up in headline earnings. Walmart’s Q1 fiscal 2027 operating income grew 5.0% while revenue grew 7.3%, with fuel costs taking 250 basis points. Fiscal 2027 guidance calls for 3.5% to 4.5% constant-currency net sales growth against 6.0% to 8.0% adjusted operating income growth. The margin expansion is real, and it is coming from mix rather than from selling goods better.
How to Apply Walmart’s Playbook to Your Business
Skip the generic advice about knowing your customer. Four transferable mechanics:
Find the second product hiding inside your first one. Walmart sold goods for sixty years before noticing it also owned an audience. Ask what asset your core business generates as a byproduct: traffic, data, distribution, credibility, or a customer relationship someone else would pay to reach.
Price the acquisition product to win, price the monetization product for margin. Walmart’s shelf price does not need to make money if the media attached to it does. Software companies do this with free tiers. Retailers do it with loss leaders. The requirement is knowing which product is which and never confusing them.
Move upmarket through assortment, not through message. Walmart added Caraway and a Scoop fashion collection without changing “Save Money. Live Better.” Repositioning a brand upward with advertising is expensive and slow. Giving a new customer a reason to try you is cheaper.
Own the interface, or rent it on your terms. Walmart pulled out of OpenAI’s checkout when the conversion math failed, then re-entered with its own agent. If you distribute through a platform you do not control, keep the account relationship, the payment, and the data on your side of the line.
FAQ
What is Walmart’s marketing strategy in one sentence? Sell goods at low margins to build the largest identified shopper audience in U.S. retail, then monetize that audience through advertising, memberships, and marketplace services.
How much money does Walmart make from advertising? Walmart’s global advertising business generated approximately $6.4 billion in fiscal 2026, growing 46% year over year. Global advertising grew 37% in Q1 fiscal 2027, with Walmart Connect in the U.S. up 44% excluding VIZIO.
Is Walmart still an Everyday Low Price company? Yes, and the 10-K still names price leadership as the cornerstone of the business. What changed is the funding source. Advertising and membership profit now help pay for price investment, which reduces the pressure to extract margin from suppliers.
Who is Walmart’s target market in 2026? Value-driven shoppers at every income level, with a historic core of budget-conscious suburban and rural families. The fastest-growing segment is households earning more than $100,000, which have driven the majority of Walmart’s share gains for several quarters.
What is Walmart Connect? Walmart Connect is the company’s U.S. retail media network, selling sponsored search, display, video, in-store, and connected TV inventory to brands and marketplace sellers. It ranked second in U.S. retail media in 2025 at roughly 8% share.
Why did Walmart buy VIZIO? To own a connected TV operating system rather than rent CTV inventory. VIZIO’s SmartCast platform gives Walmart Connect ad inventory in the living room and lets the company tie TV ad exposure to in-store and online purchases through closed-loop attribution.
How is Walmart handling AI shopping assistants? By becoming one. After OpenAI’s Instant Checkout converted at about a third of Walmart.com’s rate, Walmart ended that integration and embedded its own agent, Sparky, inside ChatGPT and Gemini, keeping the account link, the checkout, and the customer data.
Who runs marketing at Walmart? Seth Dallaire serves as EVP and Chief Growth Officer for the enterprise, effective February 2026, after leading growth for Walmart U.S. He previously ran advertising at Amazon and was chief revenue officer at Instacart.
The Business Model Analyst Take
Walmart has performed the trick that eluded every other legacy retailer: it stopped competing with Amazon on retail and started competing with it on media.
The comparison people reach for is Amazon’s ad business, and the gap looks enormous at $6.4 billion against roughly $68 billion. The more useful comparison is the conversion ratio. Amazon turns about 8% of its sales into advertising revenue. Walmart turns 0.9%. Closing even half that gap on a $706 billion sales base would add more operating income than Walmart U.S. currently earns in a year.
The risk sits in the same place as the opportunity. Walmart’s audience is valuable because shoppers trust the store. Retail media monetizes that trust by selling the right to interrupt it. Amazon has already pushed its search results to the edge of usability, and Walmart is watching that experiment run in real time before deciding how far to go. Meanwhile agentic shopping threatens to route around the storefront entirely, which is why the Sparky pivot away from OpenAI’s checkout was the single most revealing decision Walmart made in 2026.
For anyone studying this, the lesson is not “start a retail media network.” It is that a business with enormous scale and thin margins should audit what it produces for free that someone else would pay for. Walmart produced shopper attention for sixty years and gave it away. It now charges $6.4 billion a year for it, and that line is growing ten times faster than the stores.
Related reading: the Walmart business model, Walmart target market analysis, Walmart SWOT analysis, Walmart value chain analysis, Walmart mission and vision statement, and Walmart competitors.