
Vuori’s target market is affluent, urban and suburban adults aged roughly 25 to 45, split close to evenly between men and women, with household incomes well above $100,000. But the transaction data tells a sharper story than the brand’s marketing does. Vuori’s revenue is concentrated among ultra wealthy families, high income urban professionals, and wealthy retirees. The average income suburban shopper, the one Vuori needs in order to hit its store targets, is almost absent from the receipts.
That gap between the story and the spending is the whole strategic question facing the brand right now.
Vuori at a glance
| Item | Detail |
|---|---|
| Founded | 2015, Encinitas, California, by Joe Kudla |
| Headquarters | Carlsbad, California |
| Category | Premium athleisure and performance lifestyle apparel |
| Valuation | $5.5 billion (November 2024, General Atlantic and Stripes) |
| Revenue | Analyst estimates put the business near $1 billion annually. Vuori is private and does not disclose figures |
| Profitability | Profitable since 2017, per the company |
| Store count | Roughly 85 stores in early 2025, with a target of 100+ by end of 2026 |
| Channel mix | Majority direct to consumer, plus wholesale through Nordstrom, REI, Equinox and others |
| Founding niche | Men’s performance apparel, a segment Lululemon and Alo had largely ignored |
| Women’s line | Launched 2018, now roughly half of revenue |
Vuori means mountain in Finnish. The brand started as men’s shorts sold to boutique fitness studios, which is a much less glamorous origin than the coastal California branding suggests, and considerably more instructive.
The standard Vuori customer profile is lazy, and mostly wrong
Search for Vuori’s target market and you will find the same paragraph everywhere. Health conscious professionals, 25 to 45, household income above $100,000, values wellness and sustainability, wants clothes that go from the gym to brunch.
None of that is false. It is just useless. It describes roughly every premium athleisure brand on earth, including the three Vuori is trying to beat. If a segmentation statement applies equally to Lululemon, Alo Yoga, Athleta and Vuori, it is not a segmentation statement. It is a category description.
The transaction data says something much more specific and much less flattering to the brand’s egalitarian, surf town self image.
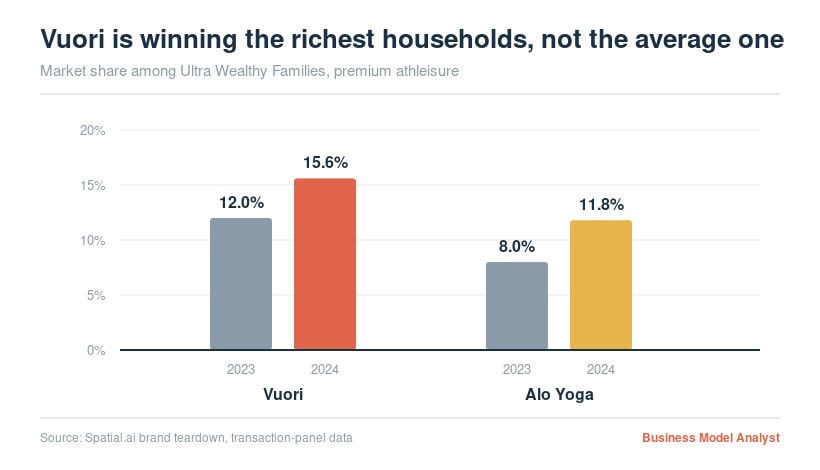
Spatial.ai’s brand teardown, built on card transaction panels rather than brand messaging, found that Vuori’s share among Ultra Wealthy Families climbed from about 12% to 15.6% in a single year, while Alo Yoga moved from roughly 8% to 11.8%. Both brands are taking that ground directly from Lululemon.
More revealing is what the same analysis found missing. Vuori’s top segments cluster into four lifestyles: ultra wealthy families, educated high income urbanites, wealthy retirees, and single young professionals. Average income suburban households, the demographic backbone of American retail, barely register. Vuori also shows around 6.13% penetration in households earning $500,000 or more, which is an extraordinary number for a clothing brand and a slightly terrifying one for anyone modelling its growth runway.
Vuori is not an athleisure brand for active people. It is a status good for people who are already comfortable, sold in the visual language of active people.
Demographic segmentation
| Variable | Vuori’s actual customer |
|---|---|
| Age | Core 25 to 45, with meaningful and growing penetration among 45 to 60 active agers and wealthy retirees. Largest single web audience cohort is 25 to 34 |
| Gender | Roughly 50/50 by revenue. Website audience skews female at about 55.7% versus 44.3% male |
| Income | Household income above $100,000 as the floor. Revenue concentration sits in the $250,000 to $500,000 band, with unusually strong penetration above $500,000 |
| Education | Predominantly college educated, professional occupations |
| Geography | Dense affluent urban markets. Los Angeles, San Francisco and New York lead, with Phoenix and Dallas in the top ten |
| Life stage | Established professionals and affluent families, not students or early career buyers |
The age band matters less than the income band. A 34 year old marketing manager earning $85,000 and a 34 year old partner track lawyer earning $310,000 are demographically similar and commercially unrelated. Vuori sells to the second one.
The basket tells you the positioning
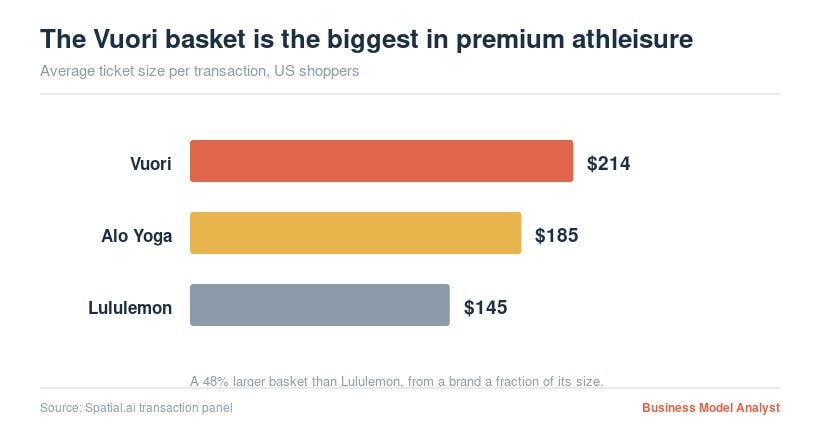
Vuori’s average ticket size sits around $214, ahead of Alo Yoga at roughly $185 and well clear of Lululemon at about $145. That is not a small gap. It means the Vuori shopper is walking out with a jogger and a hoodie, not one item on sale.
Two things drive that. First, the men’s business generates higher average baskets because men shop less often and buy in bundles when they do. Second, Vuori has kept markdown discipline while Lululemon has been forced into visible discounting. Jefferies analysts flagged Lululemon marking down items at rates unusual for a brand that historically sold the overwhelming majority of its inventory at full price. Every one of those markdowns is a small transfer of pricing power to Vuori and Alo.
Earnest Analytics also found Vuori shoppers deepening their commitment, raising the share of their total athleisure spending that goes to Vuori from about 21.6% to 27.4% year over year. Vuori is not just acquiring customers. It is consuming their wardrobe budget.
Psychographic segmentation: quiet money
Vuori’s audience is defined less by what it does than by what it refuses to signal.
- Logo aversion. The founding insight was that a large group of fit, wealthy men did not want to be a walking billboard for Nike or a walking yoga mat for Lululemon. Vuori’s branding is deliberately quiet.
- Versatility as an economic argument. The buyer treats a $98 jogger as an investment purchase, worn to the gym, the airport, and increasingly to a hybrid workplace where nobody is checking.
- Wellness as identity, not activity. A meaningful share of Vuori customers do not train seriously. They buy the aesthetic of a person who does.
- Comfort over performance. Vuori consistently rates at or near the top of its category on fit and softness. That is a fashion attribute dressed as a technical one.
- Sustainability as permission, not driver. Climate Neutral certification and recycled fabrics make the purchase easier to justify. They rarely cause it.
The quiet luxury logic is the tell. Vuori occupies the same psychological space as a $600 pair of unbranded sneakers. The absence of a logo is the logo.
The gender paradox at the center of the business
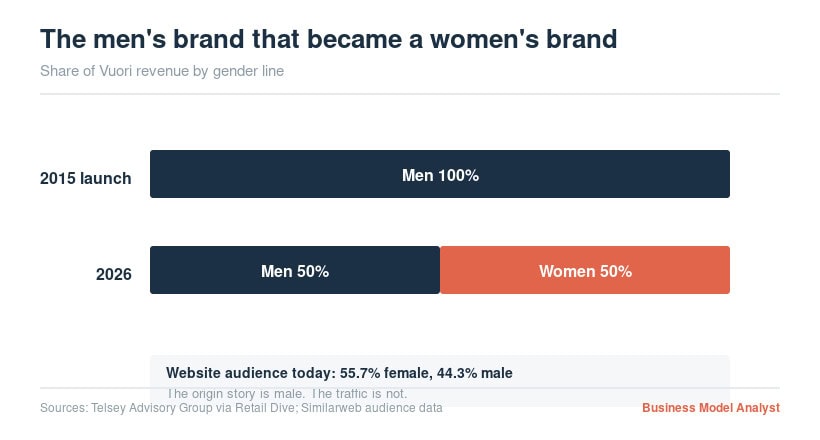
Vuori launched as a men’s brand in 2015 because men were the underserved half of the market. That story is repeated in every profile of the company, including this one, and it is now a decade out of date as a description of the customer base.
Women’s apparel launched in 2018. By 2024 the split was roughly even, and the website audience today skews female. The brand’s identity is male. Its traffic is not.
This creates a real strategic problem that most coverage skips entirely:
- The men’s business is the moat. It is the one place where Vuori has a structural advantage. Lululemon’s men’s business is still a minority of its revenue and the brand keeps hiring male ambassadors to fix it. Alo is even weaker with men.
- The women’s business is the growth. It is where the volume, the frequency, and the wallet share live.
- The women’s business is also where Vuori has no edge at all. In women’s premium athleisure, Vuori is a third brand competing on softness against two incumbents with better cultural momentum, Alo in particular, which has captured roughly 14% of the premium DTC athleisure market by early 2026.
Put plainly: the thing that makes Vuori different is not the thing that makes Vuori grow. That is a comfortable position at $1 billion in revenue and a dangerous one at $3 billion.
Geographic segmentation, and the number nobody mentions
Vuori’s growth narrative is international. The brand has stores in London, Shanghai, Seoul and beyond, sells into 18 or more countries, and is opening in Asia partly because sales made outside the United States sidestep tariffs on imported apparel.
The revenue narrative is not international.
E-commerce data from ECDB puts about 99% of vuoriclothing.com revenue in the United States. The international expansion is real, but as of now it is a strategic bet, not a revenue engine. Anyone modelling Vuori as a global brand is modelling a press release.
Domestically, the footprint is coastal and wealthy, with two interesting exceptions. Phoenix and Dallas both land in Vuori’s top ten markets, which suggests the affluent sunbelt migration is doing quiet work for the brand and that the next hundred stores probably should not all be in Manhattan.
The 100 store problem
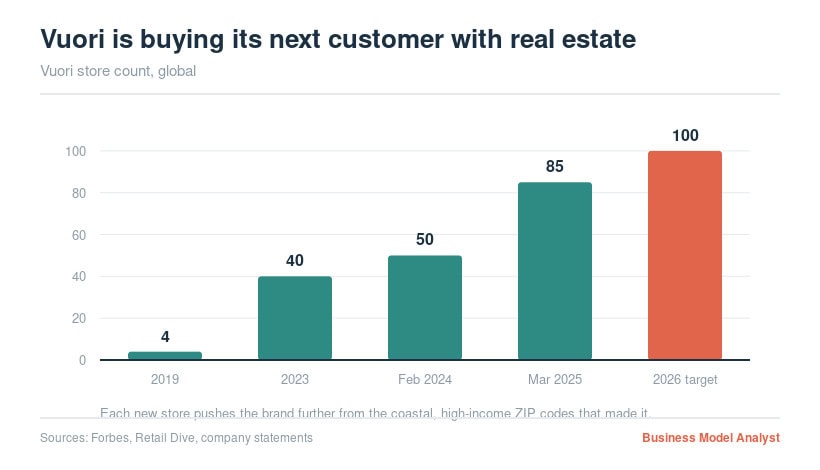
Vuori went from four stores in 2019 to roughly 85 in early 2025, with a stated goal of clearing 100 globally by the end of 2026. Physical retail is the acquisition channel: customers touch the fabric, and the fabric is the product.
Here is the tension nobody in the coverage names. Vuori’s current customer base is concentrated in the richest households in America. There are only so many of those, and they are already clustered in a handful of ZIP codes that Vuori has largely covered. Every incremental store past the coastal flagships has to be justified by selling to somebody less wealthy than the current average customer.
That leaves three options, and they are not equally good:
| Path | What it requires | The risk |
|---|---|---|
| Go deeper with the affluent | More categories per customer: outerwear, swim, footwear, travel | Wallet share is already at 27.4% and climbing. Diminishing returns arrive fast |
| Go broader into the suburbs | Lower price points or wider store footprint into average income markets | Dilutes the premium positioning that produced the $214 basket in the first place |
| Go international | Localized assortments, European and Asian store openings | Currently 1% of e-commerce revenue. Expensive, slow, and Lululemon is already there |
The private equity money that valued Vuori at $5.5 billion is priced for all three working. Note that both the SoftBank round in 2021 and the General Atlantic round in 2024 were largely secondary, giving early shareholders liquidity rather than putting cash on the balance sheet. That is a sign of financial health. It is also a sign that the smart early money has been quietly taking chips off the table for years.
Vuori versus its two real rivals
| Vuori | Lululemon | Alo Yoga | |
|---|---|---|---|
| Entry point | Men’s performance | Women’s yoga | Women’s yoga, fashion-led |
| Average ticket | ~$214 | ~$145 | ~$185 |
| Core psychographic | Quiet, affluent, logo averse | Community, technical performance | Celebrity, Gen Z, streetwear |
| Marketing engine | Stores, community, word of mouth | Ambassadors, run clubs, stores | Influencers and celebrities |
| Gender mix | Roughly even | Women majority, men above 25% | Heavily female |
| Position in 2026 | Taking share, unproven at scale | Defending, discounting, leadership churn | Fastest cultural momentum |
The single most useful fact in that table is that all three chase the same affluent buyer, and that buyer has enough disposable income for all three to grow at once. Athleisure is not yet a zero sum fight. It becomes one the moment consumer spending on discretionary apparel contracts, and at that point the brand with the highest average ticket and the narrowest income base is the most exposed, not the least.
Information gain: the data most Vuori articles do not have
| Data point | Figure | Source |
|---|---|---|
| Penetration in $500k+ households | 6.13% | Spatial.ai |
| Share among Ultra Wealthy Families | 12% to 15.6% in one year | Spatial.ai |
| Average ticket size | ~$214 | Spatial.ai |
| Share of athleisure wallet at Vuori | 21.6% to 27.4% | Earnest Analytics |
| Website audience gender split | 55.7% female, 44.3% male | Similarweb |
| US share of e-commerce revenue | ~99% | ECDB |
| Valuation | $5.5 billion, November 2024 | General Atlantic |
| Alo’s premium DTC share, early 2026 | ~14% | Industry analysis |
| Store count trajectory | 4 (2019) to ~85 (2025) to 100+ target | Forbes, Retail Dive |
FAQ
Who is Vuori’s target market? Affluent adults aged roughly 25 to 45, split evenly between men and women, with household incomes above $100,000 and revenue concentrated in the $250,000 to $500,000 band. Core segments include ultra wealthy families, high income urbanites, wealthy retirees, and single young professionals.
Is Vuori a men’s brand or a women’s brand? Both, and that is the point. Vuori launched in 2015 as a men’s brand, added women’s in 2018, and now sees roughly a 50/50 revenue split. The website audience actually skews female. The men’s business remains its competitive differentiator, while the women’s business drives its growth.
How is Vuori different from Lululemon? Vuori entered through men’s performance apparel rather than women’s yoga, carries a higher average ticket at around $214 versus roughly $145, and markets through quiet community building rather than technical performance claims. It is also private, profitable, and considerably smaller.
How much does Vuori make? Vuori does not disclose financials. Analysts have estimated annual revenue in the region of $1 billion, and the company says it has been profitable since 2017. Treat any precise figure with suspicion.
Is Vuori going public? An IPO has been reported as under consideration for several years, with bank consultations reported. Nothing has been confirmed by the company. The 2021 and 2024 funding rounds were largely secondary sales, which reduces the pressure to list quickly.
Who are Vuori’s main competitors? Lululemon and Alo Yoga are the direct rivals. Nike, Athleta, Gymshark, Under Armour and Beyond Yoga compete around the edges, and NikeSKIMS is the newest entrant aimed at the same premium female buyer.
The Business Model Analyst Take
Vuori is one of the best executed consumer brands of the last decade, and its target market is narrower and richer than almost anyone writing about it admits.
The founding story is genuinely brilliant. Kudla found a segment that two dominant brands had structurally ignored, served it with a product that people describe using the language of comfort rather than performance, and refused to acquire a customer at a loss. Profitability since year two is not luck. It is an accountant running a fashion brand, which turns out to be an underrated combination.
But the $5.5 billion valuation is not priced on the men’s business. It is priced on Vuori becoming a global, gender balanced, hundred plus store lifestyle brand. That requires selling to people who are meaningfully less wealthy than the current customer, in markets where the brand currently earns almost no revenue, against a rival in Alo that is winning the culture war and an incumbent in Lululemon that is wounded but enormous.
The metric to watch is not store count or revenue. It is average ticket size. If that $214 basket starts drifting toward $145, it means Vuori has bought its growth by becoming Lululemon. The whole thesis, and the whole valuation, rests on refusing to do that.
For founders, the transferable lesson is the entry point rather than the aesthetic. Vuori did not win by making better athleisure. It won by finding the customer nobody was flattering, and by refusing to grow faster than its unit economics allowed. The hard part was never the fabric.