
The layoff frees about half a billion dollars a year. Visa hands its bank partners more than $17 billion, and that is the bill it cannot cut.
Visa is eliminating about 2,600 roles, close to 7% of its workforce, with most cuts landing in technology and product teams. CEO Ryan McInerney told staff that AI is speeding up how work gets done at the company. The savings come to something like half a billion dollars a year. Over the same twelve months, Visa pays its issuing banks more than $17 billion in client incentives, the money that keeps those banks stamping Visa’s logo on their cards. The layoff pays for a push into stablecoins, cross-border and B2B services, which happen to be the parts of payments that do not require renting distribution from a bank.
Visa kept $20.1 billion of net income out of $40 billion in revenue last fiscal year. Its network carried $17 trillion in payments and cash volume across 329 billion transactions. Half of what it collects at the top falls to the bottom.
A business shaped like that does not shed 2,600 people to make the math work. It sheds them to move money from one column to another. Visa’s own filings show which column.
What Happened
McInerney sent the memo Tuesday morning. A Visa spokesperson confirmed the excerpts. About 2,600 people, close to 7% of a workforce that stood near 34,100 at the end of the last fiscal year, with the heaviest losses in technology and product organizations. Affected staff started hearing on Tuesday.
The framing was standard for 2026. Visa must keep evolving how it works to lead the transformation ahead, and AI is helping speed that evolution and shape how work gets done. A person familiar with the reasoning told Bloomberg that AI has cut repetitive tasks and shortened product development cycles, while also saying AI was not the only driver behind the decision. That second half rarely survives the headline.
Where the money goes matters more than where it came from. Bloomberg reported the freed capital heads toward consumer payments, commercial and money-movement solutions, and value-added services, a bucket that covers stablecoin, cross-border and business-to-business products. CNBC’s version added affluent customers, business remittances and geographic expansion.
Visa reports fiscal third-quarter results after the close on the same day. Shares have gained a little over 3% in 2026, trailing the broader market while beating Mastercard.
The Backstory
Mastercard did this first. On January 29, 2026, CFO Sachin Mehra told analysts the company had finished a strategic review that would hit about 4% of full-time staff, near 1,400 people, with a one-time restructuring charge around $200 million. CEO Michael Miebach described it as reductions in some areas paired with more investment and focus in others.
Six months later, Visa used the same sentence structure with a bigger number.
Two networks with near-identical economics reaching the same conclusion within two quarters points at the category rather than at either company. Both sell access to a payment network. Both run margins that would embarrass a software vendor. Both watched the same set of threats arrive at once: stablecoin settlement that skips card rails, AI agents that decide where a transaction routes, and regulators who keep circling interchange.
Neither company is short of cash. Visa bought back $18.2 billion of stock in fiscal 2025 and raised its dividend 14%. Mastercard beat fourth-quarter estimates in the same week it announced its cuts.
The Plan
Read the reinvestment list and the strategy comes into focus. Value-added services brought in $10.9 billion in fiscal 2025, up 24% year over year, and $3.2 billion in the December quarter alone against $2.4 billion a year earlier. That is Visa’s fastest-growing revenue pool and the one least tied to how many cards a bank chooses to issue.
The stablecoin work runs alongside it. Visa’s settlement volume across VisaNet reached an annualized run rate near $7 billion as of March 2026, up about 50% from the December quarter, spread across nine blockchains including Arc, Base, Canton, Polygon and Tempo. More than 160 stablecoin-linked card programs are live or in development.
On June 10 at Visa Payments Forum, Chief Product and Strategy Officer Jack Forestell laid out the pairing: AI reshaping how transactions start, stablecoins reshaping how they settle. Visa announced Agent Score, an Agentic Directory, a Large Transaction Model trained on billions of transactions, and a collaboration with OpenAI to run Visa payments inside agent-driven commerce. Its fiscal 2025 10-K names generative AI, stablecoins and agentic commerce as the next-generation technologies it is funding.
Cutting 2,600 technology and product staff while announcing a technology and product buildout is the tension worth sitting with. One reading: Visa wants a smaller, more senior build team using AI tooling. Employee forums have described internal discussion of folding engineering and management roles into a single “AI Builder” designation, though Visa has not detailed any such change.
The Business Model Angle
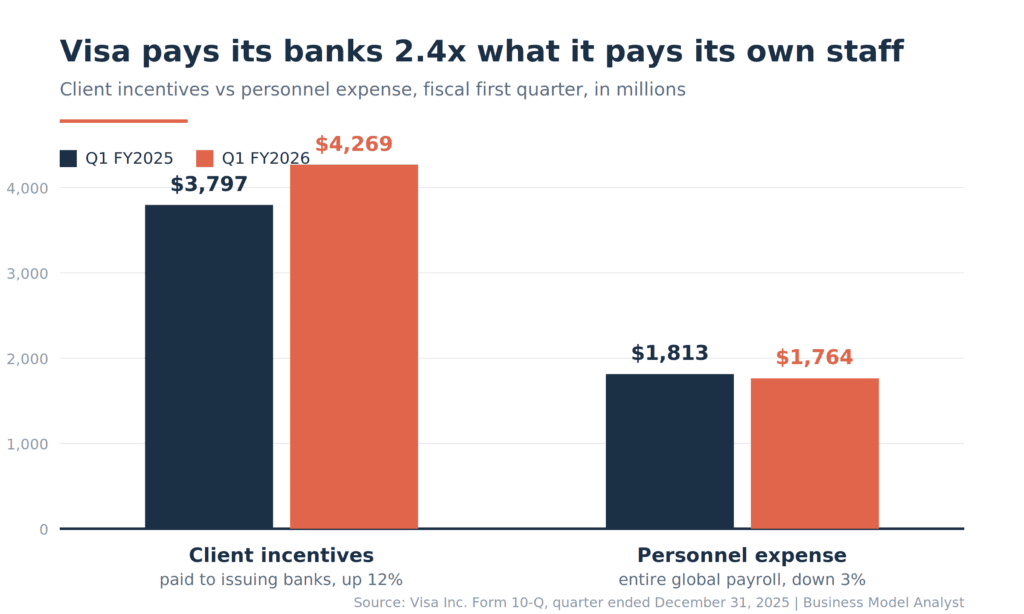
Visa runs two cost bases, and only one of them shows up in layoff coverage.
In the quarter ended December 31, 2025, Visa booked $1.76 billion of personnel expense. That number covers salaries, benefits, incentive compensation and share-based compensation for the entire company across more than 200 countries. In the same quarter, Visa recorded $4.27 billion of client incentives.
Client incentives are the payments Visa makes to financial institutions to win and keep their card portfolios. Accountants treat them as contra-revenue, so they never appear as an expense line. They come straight off the top. Visa collected $15.17 billion of gross revenue that quarter and handed back $4.27 billion of it, about 28 cents on the dollar, before recognizing a single expense.
Annualize both and the gap does the arguing. Personnel runs near $7.1 billion a year. Client incentives run past $17 billion. Visa pays its bank clients about 2.4 times what it pays every employee it has.
Now price the layoff. Divide personnel expense by headcount and the average Visa employee costs about $207,000 all in. Multiply by 2,600 and you get roughly $540 million a year, call it $500 million to $650 million once you account for technology and product roles sitting above the company average. Against the incentive line, that is about 3% of what Visa sends to the banks each year.
The direction of travel makes the point sharper. Client incentives grew 12% year over year in that quarter. Personnel expense fell 3%. Visa’s people costs were already shrinking before anyone drafted a memo.
That is the structural fact underneath the news. Visa does not have an employee cost problem. It has a distribution cost problem, and the distribution cost is the moat. Every dollar of client incentive buys issuer loyalty in a market where the bank, not the cardholder, decides which network gets the volume. Visa cannot cut that line without inviting Mastercard to outbid it for the next portfolio renewal.
So Visa cut the line it controls to fund an exit from the line it does not. Value-added services, stablecoin settlement and B2B money movement share one property: Visa can sell them without first paying a bank for the right to reach the customer. Fee income that does not carry a 28% distribution tax is worth more than fee income that does, even at identical margins.
The Risk
The escape hatch is small. Stablecoin settlement at a $7 billion annualized run rate sits against $17 trillion of total Visa payments and cash volume. That works out to about four hundredths of one percent. Growing 50% a quarter from that base is a rounding error compounding, and it will stay a rounding error for years.
Value-added services carry the more honest version of the argument at $10.9 billion and 24% growth. Even there, much of what Visa sells under that banner reaches customers through the same bank relationships the incentive line pays for. Issuing Solutions and Acceptance Solutions are not independent of the card business. They are sold on top of it.
The second risk sits inside the memo. Visa is thinning the organization that builds agentic commerce infrastructure during the eighteen months when OpenAI, Stripe and Mastercard are shipping competing agent-payment standards. Stripe and Advent International have a joint takeover bid in for PayPal. If Visa’s AI tooling delivers what McInerney implies, a smaller team ships faster. If it does not, Visa has traded capability for a margin point at the exact moment capability decides who owns the agent layer.
Third, watch what investors reward. Both networks announced cuts while posting records. A market that pays for headcount discipline at companies with 50% net margins is not asking about efficiency. It is asking for reassurance that management sees the stablecoin and agentic threat and is doing something visible about it. Layoffs are visible. Whether they are responsive is a separate question.
Quick Questions
How many jobs is Visa cutting? About 2,600, close to 7% of a workforce that stood near 34,100 at the end of the last fiscal year. Most cuts fall in technology and product teams.
Is AI the reason for the Visa layoffs? Partly. McInerney’s memo says AI is accelerating the change in how work gets done at Visa, and a person familiar with the reasoning said AI has reduced repetitive tasks and shortened product cycles. That same person told Bloomberg AI was not the sole factor.
How much money does the layoff save Visa? Visa has not disclosed a figure. Working from $1.76 billion of quarterly personnel expense across about 34,100 employees, 2,600 roles amount to somewhere between $500 million and $650 million a year.
What are client incentives? Payments Visa makes to banks and other financial institutions to win and retain their card portfolios. They are recorded as contra-revenue, subtracted from gross revenue rather than listed as an expense. Visa recorded $4.27 billion of them in the December 2025 quarter.
Is Visa in financial trouble? No. Visa reported $40 billion in net revenue and $20.1 billion in GAAP net income for fiscal 2025, repurchased $18.2 billion of stock and raised its dividend 14%.
Did Mastercard do the same thing? Yes. Mastercard announced cuts of about 4% of full-time staff on January 29, 2026, near 1,400 roles, with a restructuring charge around $200 million.
What is Visa reinvesting the money in? Consumer payments, commercial and money-movement solutions, and value-added services, a category that includes stablecoin, cross-border and business-to-business products.
The Business Model Analyst Take
Strip the AI language out of McInerney’s memo and a capital allocation decision remains.
Visa built the most profitable toll booth in commerce by renting distribution from banks. That rent costs more than $17 billion a year and rises with volume, which means growth makes it heavier rather than lighter. The Visa business model works because banks issue the cards, and it stays expensive for the same reason. Compare that with the Mastercard business model and you find the same dependency with the same price tag, which is why both companies reached for the same lever within six months.
The businesses Visa says it is funding, stablecoin settlement and agent-initiated commerce and B2B money movement, share a property worth naming. None of them require paying a bank first. If Visa can build revenue that reaches the customer without the 28-cent toll, its margin structure improves even before the revenue scales.
Every founder reading this runs a version of the same problem. Your acquisition cost lives in a channel you do not own, whether that is a bank, an app store, a marketplace or a search engine. When that toll grows with your revenue, cutting overhead buys time and changes nothing about the trajectory. Visa is spending half a billion dollars of payroll to buy optionality on a $17 billion dependency. Stripe built its business by going around that dependency rather than through it, and its bid for PayPal says it intends to keep going.
The tell arrives in about six quarters. If value-added services and money movement keep growing faster than the incentive line, McInerney bought something real. If the incentive line keeps climbing while the new revenue stays a rounding error, Visa cut 2,600 people to fund a hedge it could have paid for out of one week of buybacks.