
The private hockey rink market in a sentence: privately owned and operated indoor ice facilities that sell ice time, lessons, leagues, and rentals to a participation base that keeps growing while the supply of sheets ages and barely expands. The takeaway for operators: this is a capital-intensive, real-estate-anchored recreation business where the scarce asset is not the building, it is the hour of ice, and whoever controls the most hours sets the price.
For decades, the American ice rink was a sleepy piece of municipal infrastructure. A town built a sheet of ice, a parks department ran it at a loss, and nobody thought of it as an investment. That framing is breaking down. Aging buildings, rising demand, and a new class of well-funded operators have turned the unglamorous community rink into something investors now treat as an asset class.
This is an explainer, not a sales pitch. The goal is to break down how the market actually works, who the players are, where the money comes from, and what could go wrong. If you want the strategic shape first: a fragmented, undersupplied market with a fast-growing customer base is exactly the setup that attracts roll-ups, and that is precisely what is happening.
What “the private rink market” actually means
Start by separating three things that get lumped together. There is the equipment and synthetic-surface market (companies that sell rink products and refrigeration gear), the real ice facility operating market (the businesses that run sheets of ice for the public), and the broader youth hockey economy (leagues, travel, coaching, gear). This piece is about the middle one, the operating business, because that is where the ownership shake-up is happening.
The numbers frame the opportunity. The International Ice Hockey Federation counted roughly 2,600 ice rinks in the United States in 2023-24, around 2,100 of them indoor. The operating side is small in revenue terms and almost comically fragmented: IBISWorld pegs the US ice rinks industry at about $848 million across 477 businesses, with no single company holding even 5% of the market. That fragmentation is not a footnote. It is the entire investment thesis.
| Layer | What it is | Rough scale | Who plays here |
|---|---|---|---|
| Equipment and surfaces | Refrigeration, dasher boards, synthetic ice | ~$1.9B North America rink products | Glice, Xtraice, KwikRink |
| Facility operations | Running real sheets of ice for the public | ~$848M US revenue, 477 firms | Black Bear, Sharks Ice, NHL teams, municipalities |
| Youth hockey economy | Leagues, travel, coaching, gear | $30B to $40B US youth-sports spend | Associations, brands, training academies |
Why demand is climbing while supply sits still
The expansion story rests on a simple imbalance. Participation is rising, and the buildings are getting old.
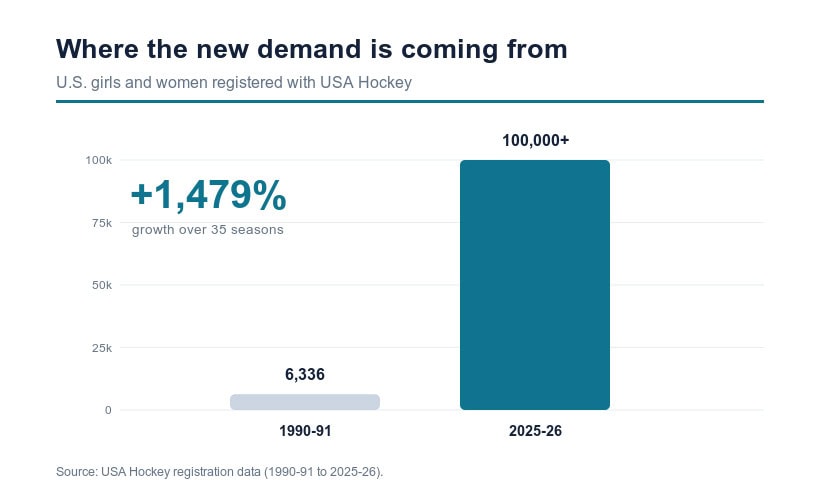
USA Hockey reported 676,433 members in 2024-25, and the fastest-growing slice is female. Girls and women registered with USA Hockey grew from 6,336 in 1990-91 to more than 100,000 in 2025-26. The arrival of the Professional Women’s Hockey League in 2024 added a visible top to that ladder, giving young players something to climb toward.
Now the supply side. The average American community rink is over 30 years old, and building a new one has gotten brutally expensive. That mismatch (more skaters, the same tired buildings) is the pressure that creates pricing power for whoever owns ice in a given market.
| Demand driver | What it adds | Supply constraint | Why it bites |
|---|---|---|---|
| Female participation surge | 100,000+ registered, fastest-growing segment | Aging rinks | Average sheet is 30-plus years old |
| PWHL and NHL expansion markets | New fans in non-traditional regions | Construction cost | A new sheet has roughly doubled in price |
| Year-round programming | Camps, lessons, off-season leagues | Deferred maintenance | Ice plants and chillers hit a “maintenance cliff” |
| Adult recreational leagues | Stable, repeat, less price-sensitive | Land and permitting | Rinks need dense population to pencil out |
How a private ice rink actually makes money
A rink looks like a sports venue but behaves like a high-fixed-cost utility. The refrigeration runs whether one skater shows up or two hundred do, which is why the entire game is utilization. Every empty hour of prime ice is margin that evaporates. The model rewards filling the calendar, much like the membership-and-volume logic behind the Planet Fitness business model, where a low marginal cost per visit only works if the base is large and steady.
The revenue stack is more diversified than outsiders assume. Ice time rental is the anchor, but the margin often lives in the softer lines.
| Revenue stream | How it works | Notes |
|---|---|---|
| Ice time rental | Teams and leagues book the sheet by the hour | Roughly $140 to $165 per hour at peak; the core demand driver |
| Public skating | Open sessions at about $10 per head, plus skate rental | Higher margin, weather and season sensitive |
| Learn-to-skate and lessons | Recurring class enrollment | Feeds the pipeline into leagues |
| Leagues and tournaments | Operator runs the competition, not just the ice | Captures more of the wallet, builds loyalty |
| Food, beverage, and retail | Bar, concessions, pro shop | The “Stanley’s Sports Bar” effect; sticky add-on revenue |
| Naming rights and sponsorship | Corporate branding on the building or sheets | Lumpy but high-margin |
Here is the unglamorous truth that explains the whole ownership shift: many rinks are not profitable unless they carry little or no debt, which is exactly why municipalities historically ran them. The new operators are betting they can change that math through scale, better programming, and capital that small operators simply cannot raise.
And the capital wall is steep. A new single traditional sheet now runs $15 million to $20 million, a figure that has roughly doubled in recent years. A two-sheet complex can reach $46 million. Even renovating an aging rink runs $10 million to $15 million, and replacing a single chiller can cost millions on its own.
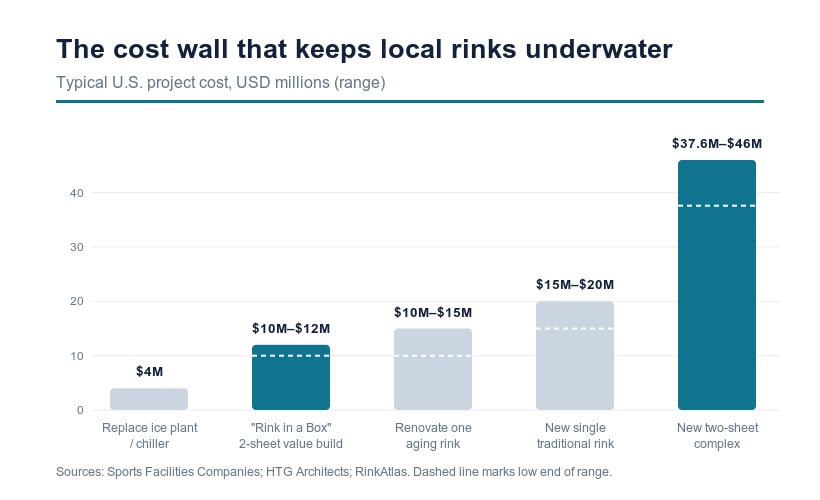
That cost wall is the reason a family-run rink with a dying chiller faces an impossible choice: find millions it does not have, or sell. That choice is creating the deal flow.
Three ways to own the ice
The interesting part of this market is that the major players are pursuing three genuinely different strategies. They are not competing for the same thing. Understanding the difference is the point of this whole piece.
| Model | Example | Core logic | What it optimizes for |
|---|---|---|---|
| Private roll-up | Black Bear Sports Group | Buy aging rinks, cluster them, professionalize operations | Return on invested capital, regional density |
| Team-operated municipal partner | Sharks Ice (Sharks Sports & Entertainment) | Operate city-owned ice at scale, anchor a hockey ecosystem | Throughput, community footprint, pipeline |
| Pro-team community anchor | Kraken Community Iceplex | Build new ice as a brand and development asset | Fan growth, player pipeline, civic goodwill |
1. The roll-up: Black Bear Sports Group
Black Bear, founded in 2015 by Murry Gunty, is the clearest expression of the financial thesis. It owns, manages, or operates 47 ice rinks clustered across the Mid-Atlantic and Midwest, which makes it the largest single operator in the country. It pairs the buildings with its own leagues, tournaments, and even a streaming platform.
The strategy is a classic consolidation play. Acquire undercapitalized rinks, invest in the infrastructure that local owners deferred (ice plants, dehumidification, subfloors), cluster them in target regions for operating leverage, and run them as a system rather than a collection of one-offs. It is the same private-equity roll-up logic now visible across fragmented consumer categories, from veterinary clinics to fitness brands. The recent move by L Catterton to take a stake in Hyrox, detailed in the economics of Hyrox, is the same pattern wearing different shoes: institutional capital finding a fragmented, demand-led category and pressing fast-forward.
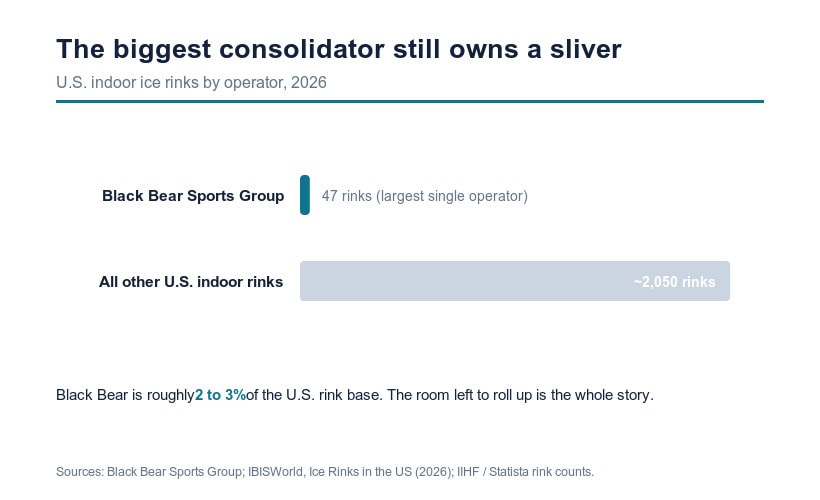
The chart shows why investors are interested and why families are nervous in equal measure. Forty-seven rinks sounds dominant until you realize it is a rounding error against the national base. The runway to keep buying is enormous. The catch is that the model only generates its returns if it can eventually raise prices, and in a sport already known for being expensive, that is where the friction starts. We will come back to it.
2. The team-operated scale play: Sharks Ice
The San Jose Sharks have quietly built one of the most impressive ice operations in the country, and they do not even own the building. Sharks Ice, a subsidiary of Sharks Sports & Entertainment, has managed the city-owned San Jose facility since 1998 under a public-private arrangement. Expansions pushed it toward six sheets, making it the largest ice facility under one roof in North America, drawing more than 1.2 million visitors a year and hosting the largest adult hockey league in the United States.
This is a different bet than Black Bear’s. The Sharks are not chasing rink-level ROIC across a portfolio. They are running a high-throughput anchor that feeds their entire hockey ecosystem: the pro practice facility, the AHL affiliate, a junior program, figure skating clubs, and a vast adult league all under one roof. The municipal partnership keeps the capital structure light, the city owns the asset, and the team captures the operating upside and the community relationship.
3. The community anchor: Kraken Community Iceplex
The Seattle Kraken took the most expensive and most strategic path. When the franchise launched, it built the $80 million, three-sheet Kraken Community Iceplex inside the redeveloped Northgate mall, with a Starbucks partnership and a medical clinic attached. Ownership has said the obvious choice was one sheet, and they deliberately built three.
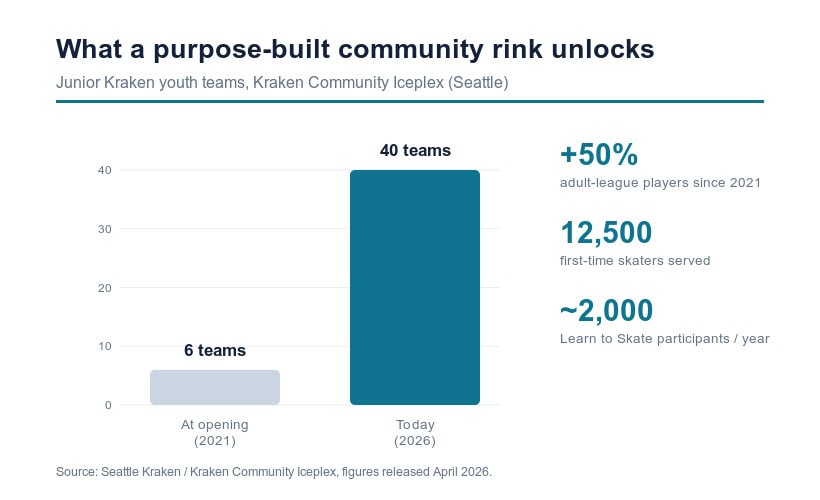
That decision looks smart in hindsight. Since opening in 2021, the building has become a demand engine: youth Junior Kraken teams grew from six to forty, the adult league grew more than 50%, and the facility has served 12,500 first-time skaters in a region that had no ice in the city limits before.
The Kraken are now extending the model. In 2026 they announced a second, $60 million, two-rink iceplex in Kirkland, structured as a 34-year ground lease at one dollar a year, with the facility reverting to the city at the end. The team projects roughly $7 million in annual local economic activity. Read the structure carefully and you can see the genius: the Kraken get a development and fan-pipeline asset with minimal land cost and civic goodwill, the city gets ice and a community center with no new taxes, and the team keeps the training and rink revenue of its women’s affiliate inside its own ecosystem rather than paying a third party. It is a community story on the surface and a vertical-integration story underneath.
The risk nobody at the rink wants to say out loud
Every expansion story has a counterweight, and this one is affordability. Youth hockey is already one of the most expensive sports in America. Recreational play runs around $1,500 a year, travel hockey lands between $7,000 and $15,000, and elite programs can top $20,000. The median household income of hockey families already sits 40% to 50% above the national average. This is a pay-to-play sport before any consolidation enters the picture.
So when a private operator buys a community rink, fixes the chiller, and then restructures the rates, the capital logic and the community’s interests can collide. That tension is not hypothetical. Black Bear’s Michigan expansion drew a civil inquiry from the state Attorney General examining potential anticompetitive effects from consolidating youth hockey facilities, alongside reports of higher fees at facilities it had acquired. Black Bear has said its prices are competitive and that it owns just 47 of around 1,700 rinks nationally. Both things can be true: a single operator can be tiny nationally and still hold real pricing power inside one metro area where it controls most of the sheets.
| Risk | Who it hits | Why it matters |
|---|---|---|
| Pricing power in local clusters | Families | Regional consolidation can lift fees faster than national share suggests |
| Antitrust and regulatory scrutiny | Operators | Roll-ups of community assets attract attorneys general |
| The maintenance cliff | Everyone | Deferred ice-plant repairs eventually force a sale or a closure |
| Affordability ceiling | The sport | If costs climb, the participation growth that fuels the thesis can stall |
| Energy and climate exposure | Operators | Refrigeration is energy-intensive; warm winters raise costs |
The deepest risk is the one that closes the loop. The entire bull case depends on rising participation. If consolidation pushes prices past what families will pay, the operators risk shrinking the very demand they paid to capture. A roll-up that prices out its own customers is not a growth story, it is a harvest.
Quick questions
Are private companies really buying up community hockey rinks?
Yes. Black Bear Sports Group is the clearest example, having assembled 47 rinks since 2015 by acquiring and clustering aging community facilities, often ones that needed capital their previous owners could not raise.
Why are NHL teams building their own practice rinks now?
Because the practice facility doubles as a fan-development and revenue asset. The Seattle Kraken and San Jose Sharks both run public-facing iceplexes that train the pro team, grow youth and adult participation, and capture rink revenue, all while deepening the brand in their market.
Is owning an ice rink actually profitable?
It can be, but it is hard. Many rinks only make money debt-free, which is why cities historically subsidized them. The new operators are betting that scale, diversified programming, and professional management can turn marginal facilities into profitable ones.
Will buying local rinks make youth hockey more expensive?
It might in specific markets. Hockey is already costly, and where one operator controls most of the sheets in a region, it gains real pricing power, which is exactly what regulators and parents are watching.
The Business Model Analyst Take
Strip away the Zamboni nostalgia and the private rink market is a textbook fragmented roll-up sitting on top of a genuine demand tailwind. Aging supply, rising participation, and a customer base with above-average income are the three ingredients capital looks for, and they are all present at once. That is why this market is expanding, and it will keep expanding.
But the three live strategies are not interchangeable, and that is the part operators should internalize. Black Bear is running a financial play where returns depend on pricing power, which means its ceiling is set by affordability and its risk is regulatory. The Sharks are running a throughput-and-pipeline play on someone else’s balance sheet, which is capital-light and durable but caps the upside. The Kraken are running a brand-and-vertical-integration play, spending the most up front to own the whole funnel from first-time skater to professional affiliate. Same asset class, three completely different business models.
If you are an operator or investor looking at this space, the discipline is to be honest about which game you are playing. The mistake is buying rinks on a financial roll-up thesis while telling the community a brand-and-pipeline story, because the two have opposite relationships with price. The math that makes a roll-up work is the same math that can quietly shrink the sport. The winners over the next decade will be the ones who grow the number of skaters faster than they grow the cost of skating. Everyone else is just buying real estate with a refrigeration problem.