
Everyone has been arguing about whether AI takes jobs. New demographic research says the harder problem is that there may not be enough people to fill them.
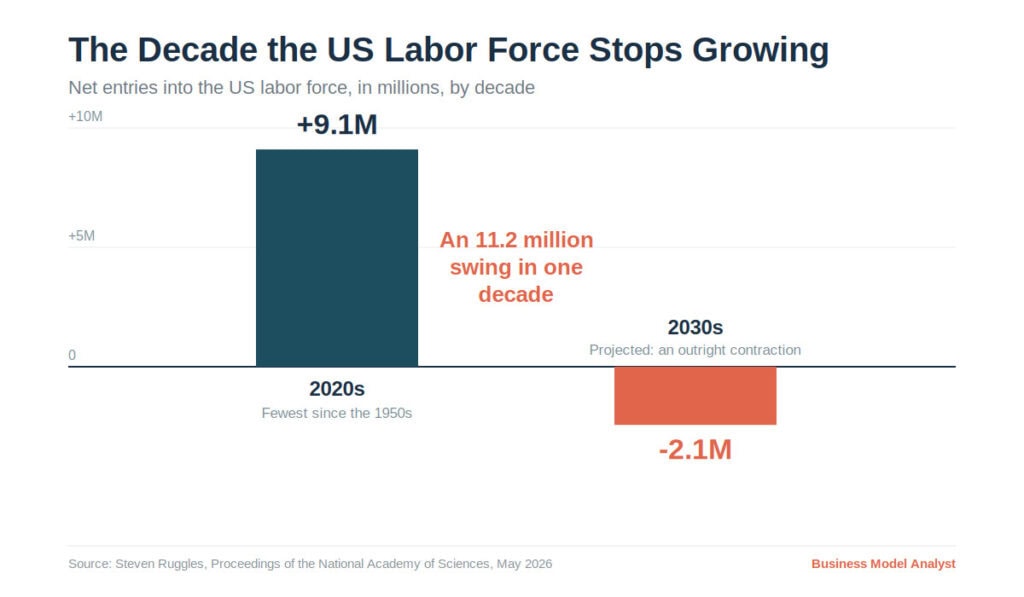
The US labor force will add just 9.1 million workers in the decade ending 2030, then shrink by 2.1 million in the decade after that, according to demographer Steven Ruggles. The bottleneck of the 2030s may not be too few jobs. It may be too few humans. That quietly rewrites what AI is actually for.
Picture a hiring manager in 2034. She has budget, she has open roles, she has a product with demand. What she does not have is applicants. Not because the economy is bad, but because the babies who would have grown into those applicants were never born. Her options narrow to two: pay dramatically more, or automate. Most companies will try to do both, and discover they can only afford one.
What Happened
Ruggles, a University of Minnesota professor who won a MacArthur grant in 2022 for his work on population statistics, published an analysis in the Proceedings of the National Academy of Sciences in May. Its title, “The pig in the python,” refers to the baby boom bulge working its way through the American economy for seventy years. The pig is now exiting.
Using Census Bureau data plus Congressional Budget Office immigration and mortality estimates, Ruggles forecasts net entries into the labor force of 9.1 million for the ten years ending in 2030. That would be the weakest ten-year stretch since the decade that ended in 1960. The following decade he projects an outright contraction of 2.1 million, or 1.3 percent.
An 11.2 million swing in a single decade is not a rounding error. It is a different economy.
The Backstory
This was supposed to have happened forty years ago.
In 1978, the economist Richard Easterlin told the Population Association of America that wages for young men, beaten down by the sheer size of the boomer cohort flooding the job market, would recover by 1984 as the much smaller Generation X came of age. It was a reasonable call. It was also wrong, and for two reasons Easterlin did not see coming: a historic surge in women entering the workforce, and a large rise in immigration. Both added workers he had not counted on. The wage recovery never arrived.
Ruggles’ argument is that both of those offsets have now run out of road. Female labor force participation has plateaued. Immigration has slowed sharply. And the US fertility rate began falling in the mid-2000s, with births down 17 percent between 2007 and 2024. Those children are not coming back. The 2040 working-age population is already, in a demographic sense, locked in.
The Federal Reserve made a similar point in an April staff note, estimating that the pool of available US workers could grow by fewer than 10,000 people per month in 2026. For a $30 trillion economy, that is a rounding error with a pulse.
What the Economists Found
Here is where it gets interesting, and where the AI conversation gets turned inside out.
A new National Bureau of Economic Research working paper published this month by Daron Acemoglu, David Autor, Keelan Beirne and Andrew Scott looked at what actually happens when economies run short of young workers. They compared countries and US commuting zones with different birth rates, and used variation in World War II military and civilian deaths to isolate the effect.
Their finding is the opposite of the doom consensus. Lower birth rates were associated with higher growth in GDP per working-age adult across countries and higher wage growth across US regions, with no negative hit to aggregate GDP or earnings. The paper is called “Baby Busts and Growth Booms,” which tells you where the authors landed.
The mechanism they propose is not magic. It is scarcity doing what scarcity does. When young workers get expensive and hard to find, firms invest in ways to need fewer of them. The authors found the fingerprints: countries and regions with falling birth rates produce more labor-saving patents, more high-tech activity, and higher total factor productivity growth.
“Labor markets in which workers are scarce work really well for workers and generate productivity gains as well,” said Acemoglu, the MIT professor who won the 2024 Nobel in economics.
Ruggles put the demand side plainly. An unprecedented labor shortage, he said, is a huge incentive to adopt labor-saving devices like AI.
The Business Model Angle
Almost every AI business case written in the last three years has been a cost story. Deploy the model, cut the headcount, book the savings, show the board a margin line that goes up.
The demographic math suggests that story is about to become obsolete, and not because it was wrong. Because it will stop being the point.
If the 2030s labor market looks the way Ruggles thinks it will, the company buying AI is not the one trying to shed workers. It is the one that physically cannot hire the workers it needs and is watching revenue walk out the door because a shift went unstaffed, a route went undriven, a claim went unprocessed. The ROI calculation shifts from “payroll we avoided” to “revenue we would otherwise have forfeited.” Those two numbers are not close. The second one is much larger, and it is far easier to defend in a budget meeting.
That has real consequences for how AI gets priced and sold. Cost-saving software competes against the salary it displaces, which caps what you can charge. Capacity-creating software competes against the revenue you cannot otherwise earn, which does not. It is the difference between selling a cheaper input and selling the only available one. Vendors who figure out how to underwrite the second pitch will find the pricing ceiling has moved. This is the deeper pattern in how business models are evolving in the world of artificial intelligence: the technology stays the same, the value story flips, and the margins follow the story.
There is also a timing lesson buried in the Acemoglu paper. Labor-saving technology showed up in response to scarcity, not in anticipation of it. Companies did not automate because they read a demographic forecast. They automated because they could not fill a role. Which means the adoption curve for AI in labor-tight sectors is probably steeper and later than the current hype cycle implies, and it will be driven by operations people with an unfillable req, not by innovation teams with a slide deck.
The Risk
The comfortable version of this story is that demography and AI cancel each other out into a happy equilibrium: shrinking workforce, rising productivity, higher wages, everybody wins. Do not buy it yet.
Acemoglu himself flagged the ugly branch. If AI’s productivity gains turn out to be enormous, firms may end up “laying off workers rather than running after them,” shrinking labor pool or not. In that world you get labor scarcity and displacement at the same time, which is the worst of both.
The opposite failure is just as plausible. The productivity gains could arrive too small, or too late, to offset the demographic hit, leaving an economy with fewer workers, no efficiency dividend, and a much larger retired population to support. Economists still do not agree on whether AI takes jobs or amplifies workers. They agree it raises productivity. They do not agree by how much, or when.
And Ruggles’ forecast has a live caveat: a sharp rebound in immigration would refill the labor pool and defuse the whole scenario. That is a policy variable, not a demographic constant, which makes it the single least predictable input in the model.
Quick Questions
Is the US labor force actually going to shrink? That is the forecast, not a fact. Ruggles projects a 2.1 million contraction over the 2030s based on births that have already happened and current immigration assumptions. The births are locked in. The immigration assumption is not.
Does this mean AI will not take my job? It means the aggregate math is friendlier than the headlines. Individual jobs are a different question. A shrinking labor force does not protect a specific role that a model can do more cheaply.
Why do lower birth rates lead to higher growth per worker? Because scarce, expensive labor pushes firms to invest in technology that gets more output from fewer people. Acemoglu and colleagues found more labor-saving patents and higher productivity growth exactly where birth rates fell.
Should I be hiring differently now? If your business depends on entry-level or frontline labor, the cost curve is bending against you. The useful question is which of those roles you would rather redesign now than bid for later.
The Business Model Analyst Take
For three years the AI debate has been stuck on the wrong axis: will the machines take the work? The demography says the more urgent question is who is left to do it.
The most interesting thing here is not that AI might rescue a shrinking workforce. It is that the economics profession just produced evidence that labor scarcity creates the technology, rather than the technology creating the scarcity. Causation runs the direction almost nobody’s slide deck assumes. If Acemoglu, Autor, Beirne and Scott are right, the 2030s AI boom will not be something Silicon Valley did to the economy. It will be something the economy demanded from Silicon Valley.
Founders should sit with the implication. The AI market you are pricing for today is a market of buyers trying to spend less. The AI market arriving in the 2030s is a market of buyers trying to exist at all. Those buyers behave very differently, and they pay very differently. Build for the second one.
Reporting by Justin Lahart for The Wall Street Journal. Research: Steven Ruggles, Proceedings of the National Academy of Sciences (May 2026); Acemoglu, Autor, Beirne and Scott, NBER Working Paper 35401 (July 2026).