
Tokyo and Washington intervened together on Friday. The reason these operations keep failing sits inside Japan’s own balance of payments, where a record ¥41.59 trillion of foreign earnings never turns back into yen.
The short answer: Japan stopped being an export economy and became a holding company. Its record 2025 current account surplus of ¥31.87 trillion came almost entirely from returns on foreign assets rather than from selling goods, and a large share of that income sits in overseas subsidiaries that never convert it into yen. The automatic stabilizer that used to lift the currency whenever Japan ran a surplus is gone. Intervention now has to manufacture by hand the yen demand that Japan’s own corporate structure stopped producing.
Japan’s Ministry of Finance spent more than ¥11.7 trillion of reserves across April and May trying to lift the yen. The currency finished that campaign around 160 to the dollar, roughly where it started. By late June it had slipped past 161.50, the weakest level against the dollar in about four decades. Tokyo raised rates, spent reserves, and talked tough, and the market kept selling.
On Friday the U.S. Treasury joined in. That changes the size of the buyer. It does not change who is selling.
What Happened
Japan’s Finance Ministry confirmed on Monday that it had conducted a coordinated yen-buying operation with the U.S. Treasury on Friday, the first joint intervention between the two countries in 15 years. Treasury Secretary Scott Bessent confirmed the action in a statement saying the coordinated operations countered disorderly yen movements, and added that Treasury would not hesitate to take part in further joint intervention.
Bessent went further than the usual G7 script. He said the United States strongly supports Tokyo’s steps to correct what he called the “substantial undervaluation of the yen.” That is a claim about the level of the currency, not about the speed of its moves, and it commits Washington to a target rather than to orderly trading.
Finance Minister Satsuki Katayama matched the language, telling reporters Japan remains in close communication with Treasury and will not hesitate to conduct further joint intervention. The yen reached 157 to the dollar on Monday, its strongest level since early May.
The Finance Ministry attached one technical note that drew almost no coverage. It said it plans to use the Federal Reserve’s repo facility for foreign and international monetary authorities, which lets approved central banks raise short-term dollars by temporarily pledging U.S. Treasury securities rather than selling them.
The Backstory
Washington’s interest here is not charity. Japan holds close to $3 trillion of American assets, including more than $1.1 trillion of Treasuries, nearly $1.2 trillion of equities and over $300 billion of corporate debt. Japan is the largest foreign holder of U.S. government debt, and Tokyo funding its interventions by liquidating Treasuries would push prices down and U.S. borrowing costs up at a moment when the 30-year yield already sits at its highest since 2007.
That fear has been building for months. In January, Treasury weighed intervening in the yen after Bessent blamed rising Japanese bond yields for driving up American borrowing costs. Japan and the United States signed a foreign exchange agreement in September 2025 that kept intervention available as a tool against excessive volatility. Katayama and Bessent discussed currencies in Washington in April and again by phone in June, each time using the word “bold.”
The rate gap explains part of the pressure. The Bank of Japan lifted its policy rate to 1% in June, the highest in 31 years, and held steady at its meeting last week. The Federal Reserve has kept rates between 3.5% and 3.75% all year, with dissent among policymakers pointing toward a hike. A wider gap means a weaker yen.
The fiscal picture explains more of it. Japan’s gross debt runs at more than twice the size of its economy, the heaviest load in the advanced world. Prime Minister Sanae Takaichi is pushing cost-of-living relief for households and businesses, including help with energy prices driven up by the war in Iran, which feeds expectations of more borrowing.
The Plan
Tokyo’s strategy has three legs and each one is expensive.
The first leg is reserves. Japan holds roughly $1.37 trillion in foreign exchange reserves, of which about $1.16 trillion sits in foreign currency assets. The April and May operations consumed over ¥11.7 trillion, close to $73 billion, without moving the currency out of its range.
The second leg is rates. Traders expect another BOJ hike later this year. Each increase narrows the carry gap and imposes a real cost on a government whose debt service rises with every basis point.
The third leg, added on Friday, is Washington’s balance sheet. Joining the operation gives Tokyo a second buyer and a stronger signal, and the FIMA repo arrangement gives Japan a way to raise intervention dollars without dumping the Treasuries that make Washington nervous in the first place.
The Business Model Angle
Japan ran a record current account surplus in 2025. The Ministry of Finance put it at ¥31.87 trillion, or about $203.5 billion, up 11.1% on the year. Textbook logic says a country running a surplus that large should see its currency appreciate, because foreign buyers must acquire yen to settle their bills.
The composition breaks that logic.
Japan’s goods trade ran a deficit of ¥848.7 billion in 2025. Exports rose 2.5% to ¥107.76 trillion while imports came in at ¥108.6 trillion, and shipments to the United States fell for the first time in five years under tariffs. The surplus came from somewhere else. Net primary income, meaning returns on Japan’s foreign assets, hit an all-time high of ¥41.59 trillion. Japan now earns more from owning foreign businesses and securities than it does from selling anything.
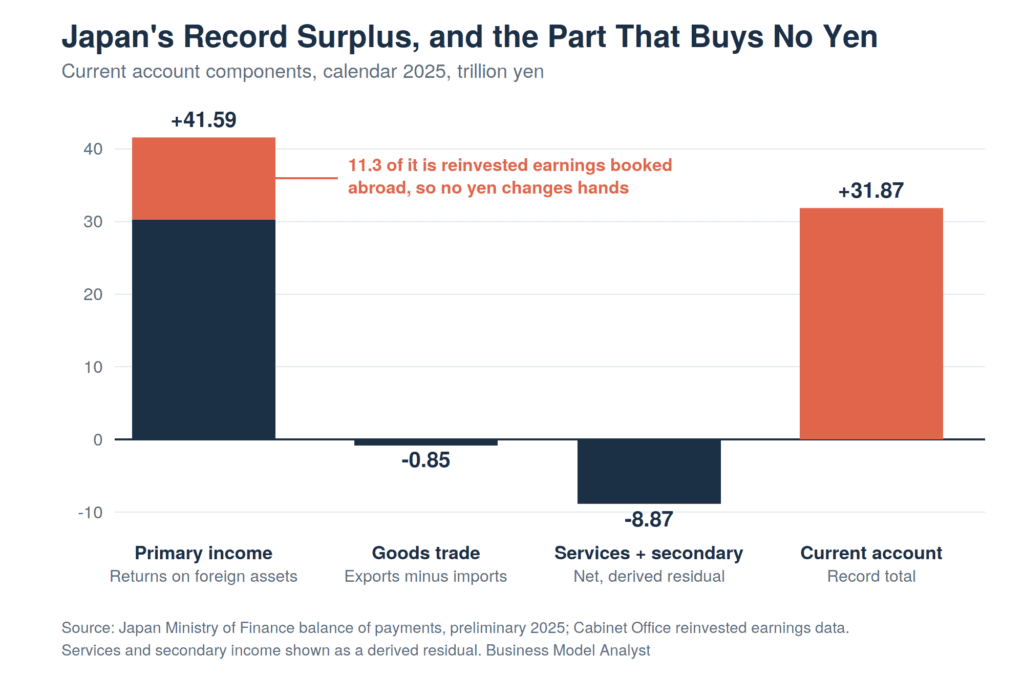
Here is where the currency mechanics break. Of the ¥26.1 trillion Japan booked in direct investment income, ¥11.3 trillion consists of reinvested earnings, roughly 27% of the total investment income surplus. Reinvested earnings are profits an overseas subsidiary made and kept. Balance of payments accounting treats them as though the parent received them and instantly sent them back, so the same figure appears in the current account as income and in the financial account as an outbound investment. No money crosses a border. No yen changes hands. Japan’s Cabinet Office says plainly that these earnings fund expansion of overseas operations rather than returning home, and academic work on Japan’s balance of payments puts the reinvested share of direct investment income at close to half.
Look at how the companies are built and the number stops being surprising. Toyota manufactures across roughly 30 countries and books financial services income wherever it lends. Sony runs gaming, music, pictures and financial services as separate global businesses with their own local revenue. Japan’s manufacturers spent three decades moving production to the markets they sell into, a shift domestic commentators call the hollowing out of the industrial base. A value chain built around overseas plants generates foreign currency profits in the country where the plant sits. The parent books the earnings, the cash stays put, and Tokyo’s currency gets nothing.
Then there are the households. Japanese savers hold around ¥2.1 quadrillion in financial assets, and the reformed Nippon Individual Savings Account program is pulling that money out of deposits and into foreign funds. Cumulative NISA purchases reached ¥71 trillion by the end of 2025 across 28.26 million accounts. Net inflows into Japanese public investment trusts topped ¥6 trillion in the first quarter of 2026 alone, a record. Two low-cost global index funds, eMAXIS Slim Global Equity and eMAXIS Slim S&P 500, took in roughly ¥1.8 trillion between them in that quarter. Japanese retail investors buy these unhedged, which means the fund manager sells yen and buys dollars every time a salary payment lands.
Run the arithmetic against the intervention. NISA is flowing at roughly ¥18 trillion a year. Japan’s April and May operations, the largest currency defense in its history, spent ¥11.7 trillion. Tokyo’s biggest intervention campaign was worth about eight months of its own households buying foreign funds. One is a finite stock of reserves. The other repeats every payday.
Corporate Japan added another $385 billion of outbound M&A in 2025, a record, which is another way of saying Japanese firms sold yen to buy more foreign assets and more future foreign earnings.
The Risk
The strongest case against this reading is that intervention was never supposed to fix the level. Central banks intervene to punish momentum traders, widen the risk premium on short yen positions, and buy time until rate differentials narrow on their own. Judged that way, Friday worked. The yen moved from near four-decade lows to 157, and the threat of a repeat now sits in every trader’s model.
Bessent’s own language undercuts that defense. Endorsing a correction of substantial undervaluation stakes out a position on where the yen should trade, which is a harder promise to keep than deterring disorderly moves.
There is also a real chance the structural story reverses. Reinvested earnings are not legally trapped abroad. Japan introduced a foreign dividend exemption in 2009 to encourage repatriation, and research by Hasegawa and Kiyota found that affiliates with large retained earnings did increase dividends to their parents in response. A tax incentive aimed at the ¥11.3 trillion currently parked overseas would do more for the yen than another ¥11.7 trillion of reserves. Nobody in Tokyo has proposed one.
Meanwhile the government is working against itself. The Financial Services Agency plans to remove the minimum age requirement for installment-type NISA accounts from January 2027, letting parents open tax-free investment accounts for children under 18 with an annual quota of ¥600,000. The program is on track to pass ¥100 trillion by the end of 2027, nearly double the ¥56 trillion the government originally targeted. One arm of the Japanese state is expanding the largest structural source of yen selling in the country while another spends reserves buying yen back.
And a stronger yen carries its own bill. Japanese exporters translate overseas profits back at better rates when the yen is weak, so a successful defense compresses the reported earnings of the same global champions Tokyo needs for a firm equity market. Higher Japanese rates create a further complication for Washington, because they make Japanese assets more attractive and give domestic institutions a reason to bring capital home rather than roll it into Treasuries.
Quick Questions
Did the United States really buy yen? Yes. Japan’s Finance Ministry confirmed a coordinated yen-buying operation with the U.S. Treasury on Friday, and Bessent confirmed it in a statement. It was the first joint intervention by the two countries in 15 years.
Why doesn’t Japan’s record surplus support the yen? Because the surplus comes from foreign investment income rather than goods exports, and a large share of that income never leaves the overseas subsidiary that earned it. Japan’s goods trade ran a small deficit in 2025.
How much has Japan already spent? More than ¥11.7 trillion, around $73 billion, across April and May, out of roughly $1.37 trillion in total reserves. The yen ended that campaign near where it began.
Will Japan sell U.S. Treasuries to pay for this? Tokyo signaled it plans to use the Federal Reserve’s FIMA repo facility instead, which lets it borrow dollars against Treasuries rather than selling them.
What would actually strengthen the yen? A narrower gap between Japanese and U.S. rates, credible fiscal restraint, or a policy that gives Japanese companies a reason to bring overseas earnings home.
The Business Model Analyst Take
Every intervention story gets written as a contest between governments and speculators. This one is a contest between Japan’s monetary authorities and Japan’s own corporate structure, and the corporate structure is winning because it was built over thirty years and the intervention lasts an afternoon.
Japanese firms did what the textbooks told them to do. They moved production close to demand, hedged political risk by owning assets in their end markets, and reinvested foreign profits into foreign growth. Every one of those decisions was correct at the company level. Together they severed the link between national success and currency strength. Japan now earns a record income from the rest of the world and receives almost none of it in yen.
That should interest anyone running a company with meaningful foreign operations, not only people watching Tokyo. Where you book profit, whether you repatriate it, and whether you hedge the translation are treated as treasury housekeeping. At national scale they determine whether your country’s currency has a bid. Nintendo earns the majority of its money outside Japan and reports in yen, which makes its headline results partly a currency story. Multiply that structure across the Nikkei and you get the balance of payments Japan has now.
Watch the tax code, not the reserves. Reserves are finite and the market knows the number. A change to how Japan taxes repatriated foreign earnings would redirect a flow that is currently permanent, and it would cost nothing to announce. Until Tokyo does something in that direction, joint intervention buys days of stability at a price measured in tens of billions of dollars, and the sellers show up again on Monday.