
The Shanghai listing gives the industry its first audited customer list. The buyer is a research budget, not a payroll.
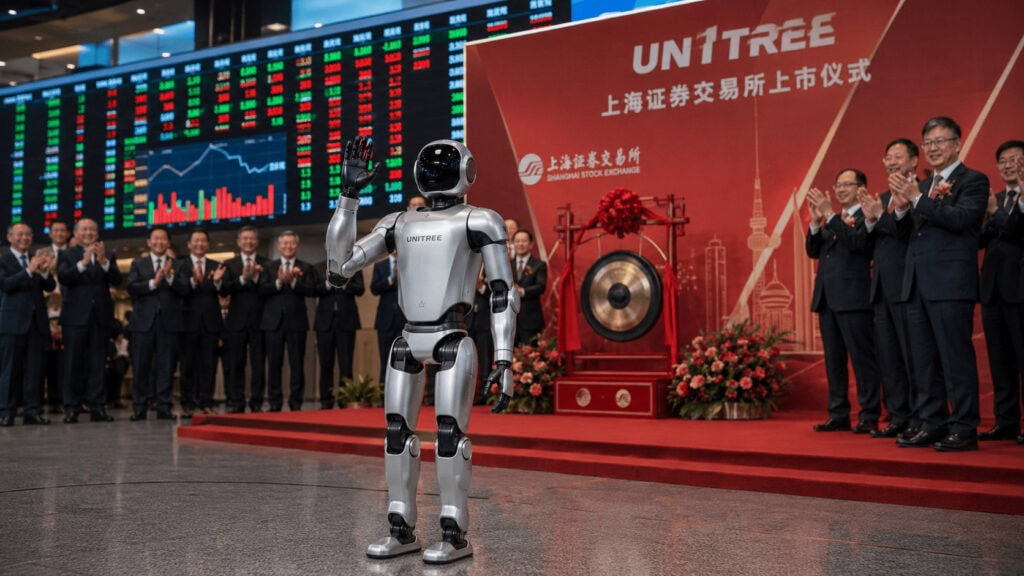
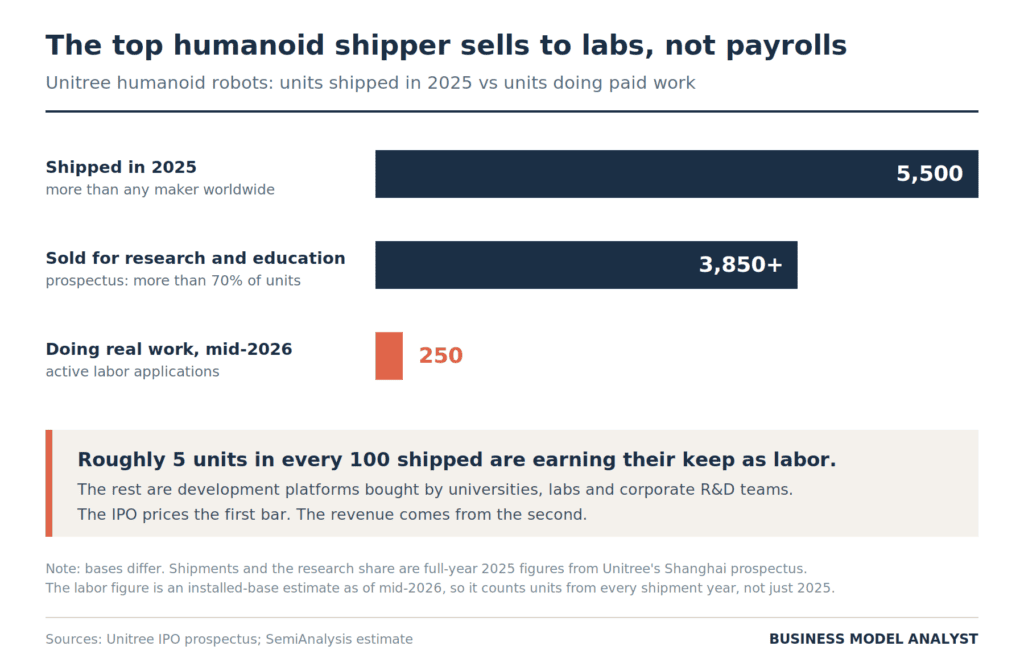
Unitree Robotics priced its Shanghai IPO on Thursday at roughly $22 a share, raising about $900 million at a valuation near $9 billion. That is close to 36 times last year’s revenue, and the multiple rests on a forecast that humanoid robots will replace human labor at scale. Unitree’s own prospectus says more than 70% of the humanoids it sold last year went to research and education. An independent estimate from SemiAnalysis puts about 250 Unitree humanoids in active labor applications as of mid-2026, against 5,500 units shipped in 2025 alone. Investors are buying a labor company. The audited filings describe a laboratory equipment company with excellent margins.
A troupe of Unitree machines performed kung fu on China’s Lunar New Year broadcast, scaling walls and swinging swords in front of hundreds of millions of viewers. That footage did more for the humanoid category than any earnings call. It also set the frame the IPO now has to survive: robots that move like people will do the work of people, and soon.
The prospectus tells a narrower and more interesting story about who actually writes the checks.
What Happened
Unitree listed on the Shanghai Stock Exchange’s STAR Market, the first pure-play humanoid maker to trade on the mainland. The company sold about 40.45 million new shares, roughly 10% of its enlarged share count. Founder Wang Xingxing, 36, keeps control with a stake near a third of the business.
The financials are unusual for the sector. Revenue reached about RMB 1.7 billion in 2025, roughly $250 million, up from RMB 392 million the year before. Adjusted net profit came in near RMB 600 million on main-business gross margins of 60.27%. Unitree makes money, which almost none of its competitors do.
The segment mix flipped fast. Humanoids generated RMB 867.8 million and passed quadrupeds to become the largest line, having accounted for 1.9% of revenue as recently as 2023. Unitree shipped more than 5,500 humanoids last year, more than any manufacturer on earth, on top of a cumulative quadruped base above 30,000 units.
Then the first quarter of 2026 landed. Revenue rose 68.5% to RMB 422.8 million. Adjusted profit fell 52.6% to RMB 40.3 million, which the company attributes to higher research and marketing spend. Run the margin: 33.9% a year ago, 9.5% now. Unitree also told investors first-half growth would slow to something like 35% to 45%, down from 335%.
The Backstory
Wang built quadrupeds during his postgraduate work, sold the first ones out of a 50-square-meter office in Hangzhou, and undercut Boston Dynamics by an order of magnitude. That price discipline carried into humanoids and became the company’s defining move.
Unitree’s average humanoid selling price fell from RMB 593,400 in 2023 to RMB 167,600 in 2025, a drop of nearly 72%. Gross margin went the other way, climbing from 44.22% to above 60%. The company credits vertical integration: it designs and builds its own motors, reducers, controllers and lidar rather than buying them. Costs fell faster than prices did.
Cheap hardware bought Unitree something that money alone does not buy. Its R1 sells from under $5,000 and its G1 from around $13,500, which put a walking humanoid inside a graduate student’s grant budget. Robotics labs at MIT, Princeton, Carnegie Mellon and Waterloo run Unitree machines. The company publishes open SDKs, reinforcement-learning environments and simulation packages on GitHub. Nvidia picked a Unitree chassis for its own humanoid research platform in June, with Unitree supplying the body and Nvidia the compute.
Every one of those wins is a research win.
The Plan
Unitree earmarked its raise for four projects: robot model research, robot hardware research, new product development, and a manufacturing base. All four point at the same destination, which is a machine that can hold a job.
That is the crossing the company is asking public shareholders to fund. Unitree wants to move from selling development platforms to selling labor, and the first quarter shows what the crossing costs. Spending on research and marketing turned a 34% net margin into a 9.5% one while revenue still grew 68%. Nobody has to guess at the price of the transition. It is in the filing.
The Business Model Angle
Two businesses sit inside this listing, and they have different customers, different budget lines and different growth ceilings.
The business Unitree runs today sells research instruments. Its buyers are universities, national labs and corporate R&D teams who need a walking platform to train models on. They pay from grant money and innovation budgets. They tolerate a machine that cannot pick up a cup, because manipulation is the thing they are trying to solve. They accept a 60% gross margin because they are comparing Unitree against a custom build that would cost ten times more. Around 480 people generate that RMB 1.7 billion, which works out near half a million dollars of revenue per employee. As a lab-equipment company, Unitree is very good.
The business the $9 billion prices sells labor. Morgan Stanley sketches a market above $5 trillion by 2050 with a billion units deployed. CLSA sees $69 billion by 2030, up from roughly $2 billion this year. Those buyers are operations executives, and they do not compare a robot against a research platform. They compare it against a wage, a shift schedule and a payback period. That customer barely exists yet, which is what the 250-unit figure measures.
Compare Unitree with UBTech, the Hong Kong-listed rival the NYT cites at a $5.6 billion market cap. UBTech chased factory deployment directly, put Walker S units into automaker plants, booked RMB 2.0 billion of revenue in 2025 and lost RMB 790 million doing it, on gross margins of 37.7%. Unitree sold picks and shovels instead, earned RMB 600 million adjusted, and now trades at a higher valuation than the company doing the thing everyone claims to be buying.
Which raises the question the prospectus does not answer. Unitree reports no software revenue, no fleet subscription, no service contract. The ASP collapse looks like a platform land grab, the standard playbook of subsidizing the device to own the ecosystem. But the toll booth is missing. If the recurring revenue in embodied AI accrues to the model layer, the company supplying the body has run a very expensive customer acquisition campaign for somebody else. Nvidia’s Jensen Huang calls physical AI the next frontier, and Nvidia is building the brain that goes inside Unitree’s chassis. We traced the same dynamic across the software stack in our margin migration breakdown, where the layer that gets commoditized is rarely the layer that captures the profit. See also our Nvidia business model teardown for how that flywheel works.
The Risk
Research demand saturates. A lab buys one G1, maybe three. It does not buy a hundred, and it does not reorder annually the way a warehouse operator replaces forklifts. Unitree has been selling into a fixed population of robotics departments at falling prices, and the first-half deceleration to 35% to 45% growth is the first sign that the population is filling up. Labor demand compounds. Research demand does not.
Washington’s move is smaller than the headlines suggest, and worse than they suggest. The FCC added foreign-produced humanoid and quadruped robots to its Covered List on July 28, blocking new models from receiving equipment authorization. Existing authorizations stand. Unitree cleared its entire current lineup weeks earlier: the R1 on June 22, the H2 and A2 quadruped on June 30. The G1, Go2 and B2 were already certified. Near-term US revenue, 13.3% of the 2025 total, is largely intact. The bite lands on the next generation, which is precisely what the IPO proceeds are meant to build. Unitree can sell the robots that exist and not the robots it is raising money to make.
Security findings complicate the picture further. Researchers documented a backdoor in Unitree hardware and later a wormable Bluetooth exploit affecting the Go2, B2, G1 and H1, and the FCC cited both. For a company whose installed base sits inside university networks, that is a product problem before it is a policy problem.
Beijing’s embrace cuts both ways too. Wang sat across from Xi Jinping at a technology symposium, and DeepSeek took a strategic stake in the IPO. National champion status brings procurement and patience. It also guarantees that every Western regulator reads Unitree as an instrument of the state, and China’s retaliation this week over the FCC action makes the company a bargaining chip in a negotiation it does not control.
Quick Questions
Is Unitree profitable? Yes. Adjusted net profit of about RMB 600 million on RMB 1.7 billion of 2025 revenue, with main-business gross margins above 60%. Reported net profit under the filing’s accounting presentation is materially lower, near RMB 288 million, so the two numbers are not interchangeable.
Why did profit fall while revenue grew? Unitree raised research and marketing spend. First-quarter revenue rose 68.5% and adjusted profit fell 52.6%, taking net margin from about 34% to about 9.5%.
Does the FCC ban stop Unitree selling in America? Not for current products. The Covered List addition blocks new equipment authorizations, and Unitree’s entire current lineup was authorized before the July 28 cutoff. New models are the problem.
How does Unitree compare with Figure AI? Figure raised more than $1 billion at a $39 billion post-money valuation in September 2025 and has never disclosed revenue. Unitree lists at about $9 billion on $250 million of audited revenue and a profit.
The Business Model Analyst Take
Unitree is not overpriced because the robots do not work. The robots work well enough that Nvidia builds on them and every serious robotics lab owns one. It is priced against a customer transition that has not started, using a multiple borrowed from a market whose entire current global size, around $2 billion by CLSA’s count, is smaller than Unitree’s valuation.
The honest bull case is that selling instruments to a gold rush is a fine business and often the best one in the field. Vertical integration that delivers 60% margins on falling prices is a real manufacturing advantage, and it transfers to labor units the moment labor demand shows up. Unitree’s sequencing may simply be correct, and UBTech’s losses are the evidence for what happens when you skip the instrument phase.
The bear case does not require the technology to fail. It only requires the two businesses to stay separate for longer than the multiple allows. Somebody will eventually sell humanoid labor at scale and make a great deal of money. Whether the company that sold everyone their development platform is the same company is a different question, and the prospectus does not answer it. What the prospectus does establish is a price. For the first time, anyone arguing about humanoid robots has a daily quote to argue against, which is worth more to this industry than another kung fu video.
For where the profits in this category have landed so far, see our breakdown of why the robots actually making money don’t look human, and our guide to humanoid robot stocks for how the exposure splits across brain, body and enablers. Elsewhere in the category, Rivian’s CEO is building robots outside Rivian, and Unitree’s new shareholder DeepSeek runs the open-weight playbook that reshaped AI pricing.