
Scott Kirby called Ed Bastian about combining the two most valuable US airlines. Delta looked, then walked. The reason sits in one line of Delta’s income statement.
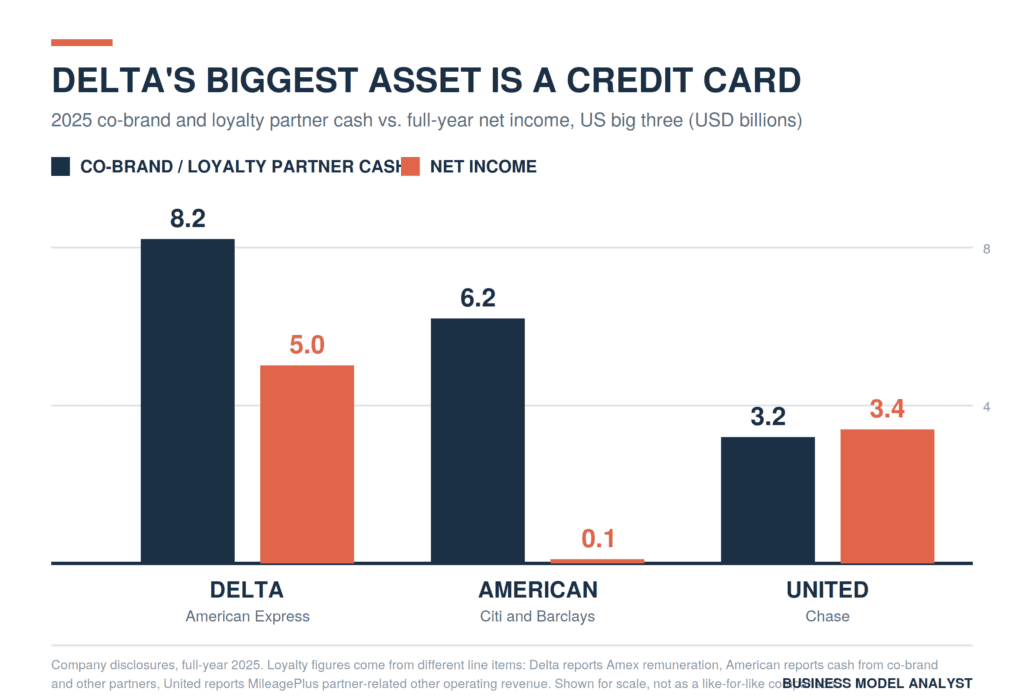
United Airlines approached Delta Air Lines last year about a merger, according to the Wall Street Journal. CEO Scott Kirby called Delta CEO Ed Bastian directly, Delta ran preliminary due diligence, and the talks died. Antitrust was the obvious obstacle. The deeper one is that Delta had nothing to gain. Delta collected $8.2 billion from American Express in 2025 against United’s roughly $3.2 billion from Chase, and that gap explains most of the $18 billion difference in what investors will pay for the two companies.
Two US airlines made money last year. The entire US scheduled passenger airline industry netted $6.0 billion after tax in 2025, according to the Bureau of Transportation Statistics. Delta booked $5.0 billion of that on its own. United booked $3.4 billion. Add those two together and you get $8.4 billion, which is more than the industry earned, because everyone else lost money.
Kirby has spent two years trying to buy his way into the winning half of that split. Now we know he tried Delta first.
What Happened
The Wall Street Journal reported on July 26 that United approached Delta last year about a merger that would have combined the two most valuable US carriers. Kirby made the pitch call to Bastian himself. Delta leadership discussed the approach and ran preliminary due diligence before both sides moved on.
The outreach had not been reported before. It predates the United and American episode that Bloomberg broke earlier this year, when Kirby floated that combination in a meeting with President Trump. Lawmakers objected, Trump said he disliked the idea, and American CEO Robert Isom called it anticompetitive. American refused to engage.
So Kirby has now been turned down by both of his peers. As of Friday, Delta carried a market value of about $56 billion against United’s $38 billion. Delta earns less revenue than United on some measures and flies a smaller fleet, yet the market prices it $18 billion higher.
The Backstory
Four carriers dominate US aviation after twenty years of consolidation. Delta absorbed Northwest in 2008. United took Continental in 2010. American merged with US Airways in 2013. Southwest bought AirTran. Airline executives and antitrust lawyers have treated a combination among the survivors as unbuildable, since removing one of four national networks concentrates the market past anything the Justice Department has approved.
Corporate America read the second Trump administration as an opening. Deal teams across banking, healthcare and telecom dusted off combinations that would have died on arrival under previous enforcers. Kirby appears to have run the same play, twice, and found no partner willing to test it.
Fuel gave him a reason to move. Jet fuel costs spiked through 2026, and United told investors this month that higher oil prices could add close to $6 billion to its full-year fuel bill compared with its January outlook. Second-quarter fuel expense jumped 84% year over year to $5.11 billion at an average $4.19 per gallon. American responded by cutting its 2026 guidance again, to a range spanning a loss of 65 cents per share to earnings of 65 cents. Spirit’s collapse cleared the low-cost end of the market. Fuel shocks have triggered every previous round of airline consolidation, and Kirby knows the pattern.
The Plan
Kirby has been explicit that he wants no part of the traditional airline merger. He wrote in April that past deals combined two struggling airlines to cut costs, flights and headcount, and that his aspirations differ. In May he told analysts that only a large transaction makes sense, denied any interest in buying JetBlue, and said that without a willing partner he sees no United participation in consolidation for the foreseeable future.
Read that alongside the Delta approach and the strategy resolves. Kirby is not shopping for capacity or cost synergies. He wants the assets that produce durable, high-margin, non-cyclical revenue, and he wants them faster than United can build them. Delta owned the best collection of those assets in the industry.
Bastian’s position has been consistent in the other direction. He has said smaller struggling carriers may combine and that Delta is not pursuing any of it.
The Business Model Angle
Delta and United no longer compete as airlines in the way the industry describes itself. They compete as consumer finance distribution channels that happen to operate aircraft.
Delta’s American Express remuneration reached $8.2 billion in 2025, up 11% year over year, and management has told investors it expects that figure to reach $10 billion within a few years. That $8.2 billion equals roughly 14% of Delta’s operating revenue and arrives without fuel burn, crew pay, maintenance or landing fees attached to it. Bastian told investors in June that around 1% of all US economy-wide spending runs across Delta’s American Express cards. Close to one in three SkyMiles members carries one.
United’s comparable disclosure runs to about $3.2 billion of MileagePlus partner-related other operating revenue, most of it tied to Chase. The gap between $8.2 billion and $3.2 billion is worth more than the $1.6 billion difference in the two carriers’ 2025 net income. It is close to the whole reason Delta commands a premium valuation while United trades like a well-run airline.
Kirby has already copied everything about Delta that money and time can buy. United’s premium cabin revenue rose 16% in the second quarter of 2026, contracted corporate revenue rose 27%, and the carrier is fitting nearly a thousand aircraft with Starlink by year end. Loyalty revenue grew 11%, the slowest of the group. Premium seats you can install. Card penetration takes a decade of brand preference among affluent frequent flyers, and Amex already holds the exclusive on the deepest pool of them.
That leaves acquisition. Buying Delta would have handed United the Amex contract, the SkyMiles base and the premium brand in one transaction. It would also have created a carrier with a co-brand cash stream north of $11 billion a year and the negotiating leverage to squeeze both Amex and Chase at renewal.
Delta had no matching reason to say yes. Its profit engine scales with cardholder spending rather than seat miles, so United’s network adds cost, integration risk, labor seniority arbitration and years of antitrust litigation while diluting the premium positioning that makes the Amex relationship worth what it is worth. Delta is the one US carrier that gains almost nothing from scale.
Kirby got his answer and moved to plan B. In February 2026, United rebuilt MileagePlus around the Chase card. Members without a co-branded card dropped from five miles per dollar on United flights to three. Basic economy passengers now earn nothing unless they hold elite status or the card. Polaris Saver award space, long the best reason to hold Chase Ultimate Rewards points, became card-holder territory. Cardholders got 10% off award redemptions, 15% with status.
Airlines usually describe changes like that as enhancements. This one is United manufacturing the card penetration it could not acquire.
The Risk
The clean version of this thesis breaks on American Airlines. American collected $6.2 billion from Citi and Barclays in 2025 and reported $111 million of net income. Co-brand cash does not create profit on its own. It multiplies whatever margin the underlying operation produces, and American’s network, cost base and premium mix keep that multiplier near zero. Delta is the only US carrier running both halves well at once.
The second risk is that United’s fix works against itself. Chase pays for cardholders who spend, and people spend on cards they want rather than cards they need to avoid a penalty. Delta built card demand by making SkyMiles status feel valuable. United is building it by making non-membership expensive. Those two approaches can produce identical sign-up numbers in year one and different renewal rates in year three.
Third, concentration. Delta’s largest profit contributor depends on a single counterparty renewing on favorable terms. Analysts have flagged issuer concentration across all three legacy programs, and no carrier has diversified.
There is also a plainer reading of the WSJ story worth holding onto. Kirby has global network ambitions, wants Pacific scale, and may have wanted Delta’s route map more than its balance sheet. The counter is that Kirby himself ruled out the network and cost logic in writing. Whatever he was buying, he told everyone it was not synergies.
Quick Questions
Did United and Delta come close to merging? No. Kirby called Bastian, Delta ran preliminary due diligence, and both companies moved on. The talks never advanced to a formal proposal.
Would regulators have approved it? Almost certainly not. Combining the top two carriers would have concentrated US aviation past anything the Justice Department has cleared, and state attorneys general would have joined the challenge.
Why is Delta worth more than United? Delta earned $5.0 billion in 2025 against United’s $3.4 billion, and a larger share of Delta’s profit comes from its American Express partnership, which produces high-margin cash that does not move with fuel prices or seat demand.
How much do airlines make from credit cards? Delta reported $8.2 billion of Amex remuneration in 2025, American $6.2 billion from its partners, and United about $3.2 billion tied to Chase. For Delta the figure equals roughly 14% of total operating revenue.
What does United do now? Kirby said in May he sees no consolidation for United in the foreseeable future. United is instead restructuring MileagePlus to push flyers into Chase co-branded cards and expanding premium cabins to close the revenue-quality gap on its own.
The Business Model Analyst Take
Kirby made the right diagnosis. United can match Delta on aircraft, lounges, Wi-Fi, Polaris seats and corporate contracts, and it has. None of that closes a $5 billion annual gap in what a bank pays you for access to your customers. He identified the one asset he could not build, and he tried to buy the company attached to it.
The lesson generalizes past aviation. When one competitor’s advantage sits in a contract rather than an operation, you cannot out-execute it. Southwest spent thirty years proving that operational discipline builds a durable business, then watched two carriers with worse cost structures earn multiples of its profit by renting their customer lists to banks. Grocery chains hit the same wall against retail media networks. Hotel groups hit it against their own co-brand portfolios.
Kirby has two options left, and one of them is slow. He can grind MileagePlus penetration upward for a decade and hope Chase pays more each renewal, or he can wait for a regulatory window that his last two phone calls suggest may never open. He is running the first play while watching for the second. Watch United’s loyalty revenue growth rate over the next four quarters. It grew 11% last quarter against 16% for premium. If the MileagePlus overhaul cannot push that number above premium growth, Kirby will have proved that the thing he tried to buy was the thing he cannot build.
Reporting based on the Wall Street Journal’s July 26, 2026 exclusive by Alison Sider and Andrew Tangel, with company disclosures from Delta, United and American, Bureau of Transportation Statistics 2025 industry data, and United’s second-quarter 2026 results.