
Ulta Beauty just had one of the best sales years in its history. It also earned less money than it did three years ago.
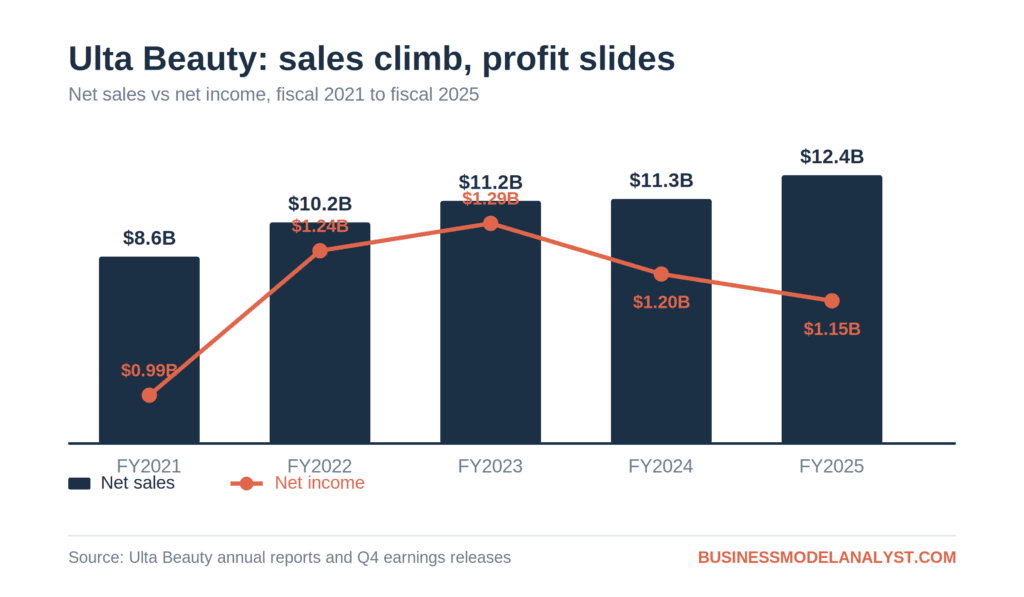
That is the tension this Ulta Beauty SWOT analysis has to explain. In fiscal 2025, the year ended January 31, 2026, net sales rose 9.7% to $12.39 billion and comparable sales climbed 5.4%, the strongest comp in three years. Net income fell to $1.15 billion, down from $1.20 billion the prior year and well below the $1.29 billion peak in fiscal 2023. Growth is back. Profit has not followed it.
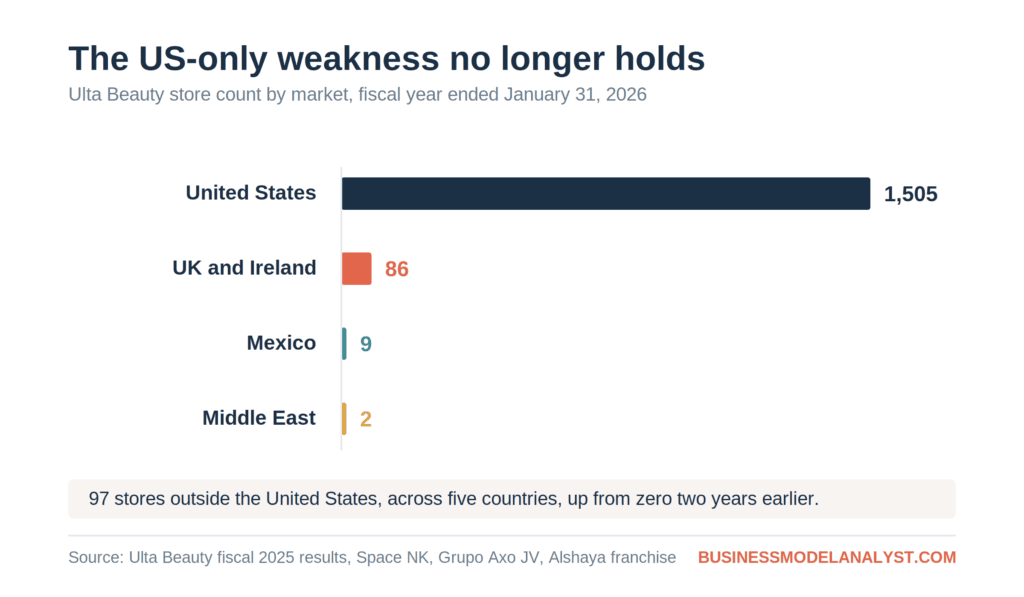
Most write-ups of Ulta still describe a purely American retailer with a domestic concentration problem. That version of the company no longer exists. Ulta closed fiscal 2025 with 97 stores outside the United States across five countries, having bought UK luxury retailer Space NK, opened nine stores in Mexico through a joint venture with Grupo Axo, and launched in the Gulf with franchise partner Alshaya. The weakness everyone lists first has been actively dismantled. A different one has taken its place.
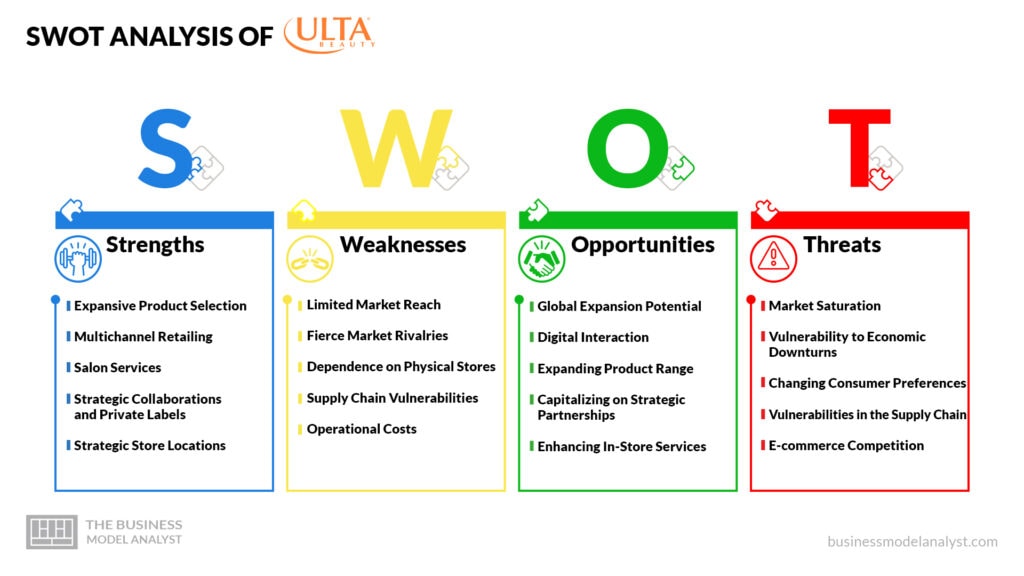
What is a SWOT analysis? A SWOT analysis maps a company across four quadrants: Strengths and Weaknesses, which are internal and largely within management’s control, and Opportunities and Threats, which are external forces the company can respond to but not dictate. Applied to Ulta Beauty, it separates what the retailer has built from what the market is doing to it.
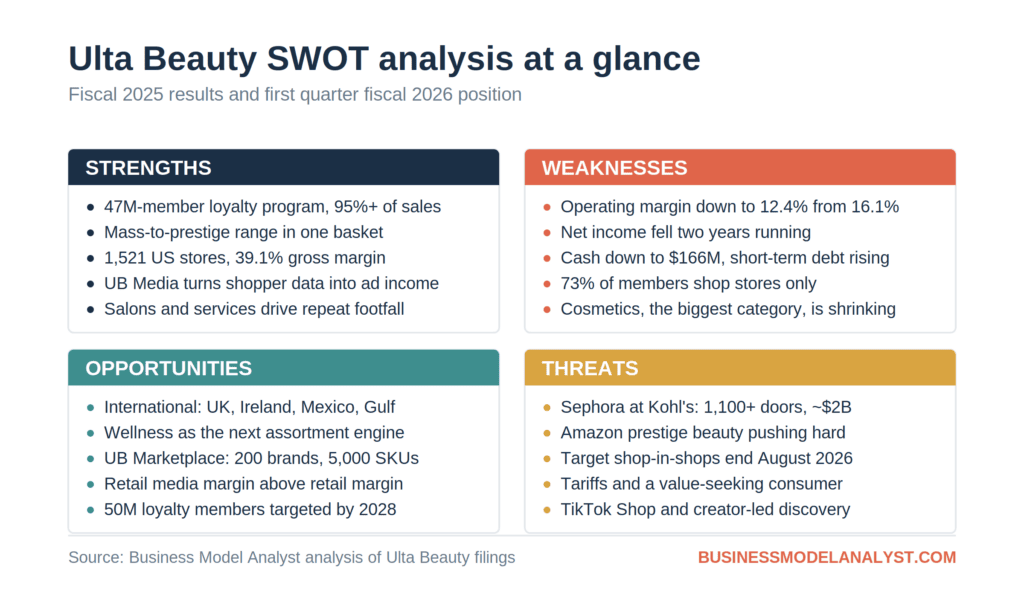
Ulta Beauty at a glance
Ulta Beauty strengths
1. A loyalty program that functions as the actual business
Ulta Beauty Rewards reached nearly 47 million active members in the first quarter of fiscal 2026, up 4% year over year, and those members account for more than 95% of company sales. Active means they shopped in the previous twelve months, which is a far stricter definition than the cumulative sign-up counts most retailers publicize.
The strategic point is not the headline number. It is that Ulta effectively knows who buys what, how often, and at what price point across roughly 25,000 products. That data underwrites replenishment prediction, personalized offers, and site selection. Management has set a target of 50 million members by 2028.
2. Mass and prestige in one basket
Ulta’s structural advantage over Sephora is range. A shopper can put a $9 drugstore mascara and a $75 prestige serum in the same cart, book a haircut, and earn points on all of it. When money gets tight, that shopper trades down within Ulta rather than leaving for a different retailer.
This is why Ulta held up through a value-conscious 2025 while narrower competitors did not. The assortment absorbs a downturn instead of transmitting it. Category mix in fiscal 2025 ran 38% cosmetics, 24% skincare and wellness, 19% haircare, 13% fragrance, 4% services, and 2% other, a spread wide enough that no single trend cycle can sink the year.
3. A store fleet that still does the selling
In fiscal 2025, 73% of Ulta loyalty members transacted solely in physical stores. Only 19% shopped both channels. For a retailer facing constant commentary about e-commerce disruption, that is a striking figure, and it is a strength rather than a liability: Ulta’s stores are where discovery, testing, and salon services happen, none of which Amazon replicates.
The fleet reached 1,521 US locations by May 2, 2026, against a stated long-term ceiling of more than 1,800. The typical store runs about 10,000 square feet with roughly 950 square feet given to a full-service salon, and a new one costs about $2.4 million all in. A smaller 5,000 to 7,500 square foot prototype lets Ulta enter markets that cannot support the full box.
4. Brands now want Ulta more than Ulta needs them
On February 1, 2026, Rare Beauty ended five years of Sephora exclusivity and entered more than 1,500 Ulta doors, delivering the largest launch day in Ulta’s history and taking the number one brand position in blush, highlighter, contour, bronzer, lip, and brow within 48 hours. Our Rare Beauty marketing strategy analysis covers what that move cost the brand in scarcity.
For Ulta, the significance is negotiating position. Access to a 47 million member enthusiast base has become a growth lever brands actively pursue, which strengthens Ulta’s terms on exclusives, launch windows, and vendor support.
5. UB Media turns shopper data into high-margin income
Ulta launched its retail media network in 2022. UB Media sells brands addressable advertising built on first-party loyalty data, spanning on-site display, app placements, and offsite streaming inventory. Retail media carries margins closer to software than to retail, and it lands in the same operating income line as the merchandise business.
The company does not break out UB Media revenue separately, describing it instead as a driver of incremental vendor income. That opacity is worth noting, but the strategic logic is sound: Ulta is monetizing an asset it already owned.
Ulta Beauty weaknesses
1. Profitability is going the wrong way
This is the weakness that matters, and it is the one most Ulta write-ups miss entirely because they stop at the revenue line.
| Fiscal year | Net sales | Net income | Operating margin |
|---|---|---|---|
| 2021 | $8.63B | $0.99B | 15.0% |
| 2022 | $10.21B | $1.24B | 16.1% |
| 2023 | $11.21B | $1.29B | 14.9% |
| 2024 | $11.30B | $1.20B | 13.9% |
| 2025 | $12.39B | $1.15B | 12.4% |
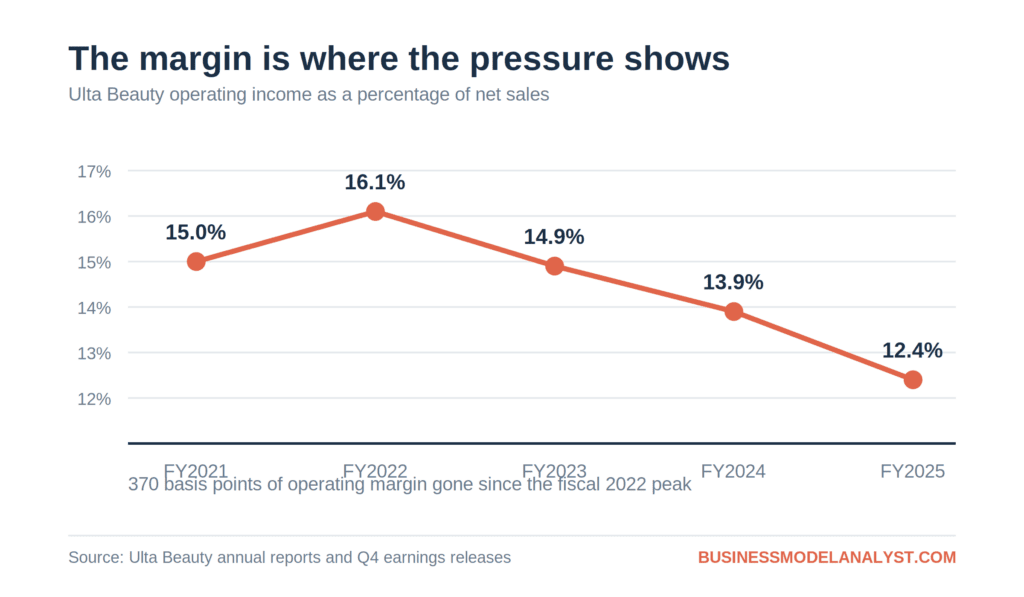
Sales grew 44% between fiscal 2021 and fiscal 2025. Net income peaked in fiscal 2023 and has fallen in each of the two years since. Operating margin has shed 370 basis points from its fiscal 2022 high. The driver is SG&A, which rose to 26.6% of net sales in fiscal 2025 from 24.9%, absorbing higher incentive compensation, store payroll, and what management calls strategic enterprise investments.
2. Earnings per share is flattered by buybacks
Diluted EPS rose 1.2% in fiscal 2025 to $25.64. Net income fell 4.0%. The gap is share count: the diluted average dropped from 47.4 million shares to 45.0 million after $890.5 million of repurchases.
Without the buyback, reported EPS would have declined. Investors reading the headline number are seeing financial engineering as much as operating performance, and the effect compounds. Ulta repurchased another $555.0 million of stock in the first quarter of fiscal 2026 alone.
3. The balance sheet is thinner than the story suggests
Cash fell from $703.2 million at the end of fiscal 2024 to $424.2 million a year later, then to $166.3 million by May 2, 2026. Short-term debt went from zero to $62.3 million to $144.9 million across the same span. Total stockholders’ equity declined from $2.80 billion to $2.58 billion in a single quarter.
Ulta generated $261.9 million in operating cash in the first quarter of fiscal 2026 and returned $555.0 million to shareholders in the same period. That gap is funded by borrowing. The business is not in distress, but a retailer buying back stock faster than it generates cash has less room to absorb a bad quarter than its income statement implies.
4. The core category is shrinking as a share of sales
Cosmetics fell from 39% of net sales in fiscal 2024 to 38% in fiscal 2025. Skincare and wellness rose from 23% to 24%. Fragrance held at 13%.
This is a slow trade, and skincare growth is genuinely healthy, but cosmetics is the category Ulta is culturally built around, and it is the category where the mass-to-prestige range is most defensible. Skincare pulls Ulta toward a fight with dermatology brands, drugstores, and Amazon rather than with Sephora.
5. Services never scaled
Salon services accounted for 4% of net sales in fiscal 2025 and have hovered there for years, despite occupying roughly 950 square feet of every store and requiring five to ten licensed professionals per location. Services justify their footprint through traffic rather than revenue, which is a defensible argument but a difficult one to prove. It also means a meaningful share of Ulta’s real estate and payroll is tied to the lowest-yield part of the model.
Ulta Beauty opportunities
1. International is now a real business, not a plan
The old critique of Ulta was geographic concentration. Fiscal 2025 answered it: Space NK brought 86 stores in the UK and Ireland, the Grupo Axo joint venture opened nine in Mexico, and the Alshaya franchise opened two in the Middle East, including a Mall of the Emirates debut in Dubai in January 2026.
Ninety-seven stores against 1,505 domestic ones is not diversification yet. It is optionality. The acquisition cost $386.8 million net of cash and added $226.4 million of goodwill to a balance sheet that previously carried almost none, so the integration risk is real and newly on the books.
2. Wellness as the next assortment engine
Management has been explicit that wellness represents meaningful incremental growth, and it is the rare adjacency where Ulta’s existing assets transfer cleanly. The category sits inside the same skincare and wellness line that grew to 24% of sales, the loyalty data already identifies who buys it, and the store associate model supports the kind of guided selling that wellness products need.
The risk is that wellness is a crowded, credibility-sensitive category where Ulta has no particular authority yet.
3. UB Marketplace extends the shelf without the inventory
Ulta launched a third-party marketplace in fiscal 2025 offering roughly 200 additional brands and 5,000 SKUs on Ulta.com and the app. It is a direct answer to Amazon and TikTok Shop: give the enthusiast a reason not to leave the ecosystem for the long tail, without Ulta having to buy and hold the inventory.
Marketplace economics are structurally better than retail economics. If the model works, it lifts the margin line that fiscal 2025 damaged.
4. Retail media has more room than the disclosure suggests
UB Media currently serves brand partners across display, app, and offsite channels, and Ulta has already opened it to non-beauty advertisers. A network built on 47 million identified beauty buyers is genuinely differentiated inventory, and the company’s reluctance to break out the revenue suggests either that it is still small or that it is strategically sensitive. Either way, the ceiling has not been tested.
5. Store growth still has runway
Ulta believes it can reach more than 1,800 US stores against 1,521 today, with fiscal 2026 plans for 50 to 60 net new locations. At roughly $2.4 million per store, that is a known-return use of capital in a business where the newer growth bets carry considerably more uncertainty.
Ulta Beauty threats
1. Sephora at Kohl’s is a fully built distribution network
Kohl’s has completed its rollout at more than 1,100 doors and describes the result as a beauty business approaching $2 billion. That is the single most consequential competitive development of the last five years for Ulta, because it puts prestige beauty in the same suburban shopping-center trade areas Ulta built its fleet around. Our Sephora SWOT analysis covers the other side of that trade.
2. Amazon is taking the replenishment purchase
Amazon’s US beauty sales reached an estimated $32.7 billion in 2024, up 12.3%, according to Momentum Commerce, and the company has spent the period since convincing premium brands that were previously unwilling to sell there. Amazon does not need to win discovery. It only needs to win the repeat purchase of a product the shopper already knows, which is the most profitable and least defensible slice of Ulta’s basket.
3. The Target shop-in-shops end in August 2026
Ulta and Target mutually agreed not to renew the shop-in-shop partnership when it expires in August 2026. At its peak the format reached 610 Target stores at roughly 1,000 square feet each. Analysts have called the financial impact minimal, and reclaiming brand exclusivity has strategic logic, but Ulta is voluntarily giving up 610 points of presence at the exact moment Sephora finished building 1,100 of its own.
4. A value-seeking consumer meets a tariff-exposed cost base
Management has repeatedly flagged an uncertain macroeconomic landscape, tariffs, and a consumer who is increasingly value focused. Beauty is discretionary. Ulta’s mass-to-prestige range cushions a downturn better than a pure prestige model, but cushioning a trade-down still means a lower average ticket, and average ticket has been carrying most of Ulta’s comparable sales growth: 3.3 of the 5.4 points in fiscal 2025.
5. Discovery is migrating to platforms Ulta does not own
TikTok Shop, creator-led launches, and direct-to-consumer brands have moved the first moment of beauty discovery away from the store aisle. Ulta has responded by joining rather than resisting, launching on TikTok Shop Live and running its Ulta Beauty World event. That is the correct response, but it means paying rent on someone else’s audience.
Frequently asked questions
What are Ulta Beauty’s biggest strengths? Its 47 million member loyalty program, which drives more than 95% of sales, and its mass-to-prestige assortment, which lets a single shopper buy at every price point in one basket. Together they produce unusually durable traffic.
What is Ulta Beauty’s biggest weakness in 2026? Margin. Operating margin fell to 12.4% of net sales in fiscal 2025 from 16.1% in fiscal 2022, and net income has declined two years in a row even as sales grew.
Is Ulta Beauty still a US-only retailer? No. As of January 31, 2026, Ulta operated 97 stores outside the United States across five countries through the Space NK subsidiary in the UK and Ireland, a Mexico joint venture with Grupo Axo, and a Middle East franchise with Alshaya.
Who is Ulta Beauty’s biggest competitor? Sephora remains the primary rival, and its buildout inside Kohl’s has taken the fight into Ulta’s suburban trade areas. Amazon is the more serious long-term threat to replenishment purchases.
Why is Ulta ending its Target partnership? Ulta and Target mutually agreed not to renew the shop-in-shop agreement when it expires in August 2026. Ulta gains brand exclusivity and control; it loses presence in 610 Target locations.
Who runs Ulta Beauty? Kecia Steelman has served as president and chief executive officer since January 2025, and is executing a growth plan the company calls Ulta Beauty Unleashed.
The Business Model Analyst Take
Ulta is buying growth, and the price is showing up in the margin line.
That is not automatically a mistake. Space NK, the Mexico joint venture, the Gulf franchise, UB Marketplace, and the wellness push are all defensible responses to a competitive environment that got materially harder once Sephora finished 1,100 doors inside Kohl’s and Amazon convinced prestige brands to list. Standing still was not an option, and the alternative to spending was watching the enthusiast base erode.
The question is the sequencing. Ulta is funding an expansion program, a $3 billion buyback, and an integration all at once, with cash down to $166.3 million and short-term borrowings rising. First quarter fiscal 2026 offered a real counterargument: gross margin recovered to 40.1%, operating margin hit 14.2%, and EPS grew 15.5%. One quarter is not a trend, but it is the first evidence that the investment phase has a floor.
Watch two numbers over the next year. If operating margin holds above 14% while international scales, Ulta has successfully converted a domestic retailer into a multi-market platform. If margin drifts back toward 12% while the buyback continues on borrowed money, the growth was bought rather than earned. For the demand side of that equation, our Ulta Beauty target market analysis breaks down who is actually filling those baskets.