
Uber’s equity in Serve was worth $17.5 million. The orders Uber stopped routing were worth $16.5 million of Serve’s 2026 revenue. Only one of those assets sat on a balance sheet.
Uber disclosed in a regulatory filing that it sold every share it held in Serve Robotics during the second quarter of 2026. Serve found out when the filing went public. The sale ends a five-year investment in a company Uber created, but the equity was the least valuable thing Uber controlled in the relationship. The bigger asset was the routing decision inside Uber Eats, and Serve never owned a piece of that. When Uber sent fewer orders, Serve cut its full-year revenue guidance from $26 million to a range of $9 million to $10 million.
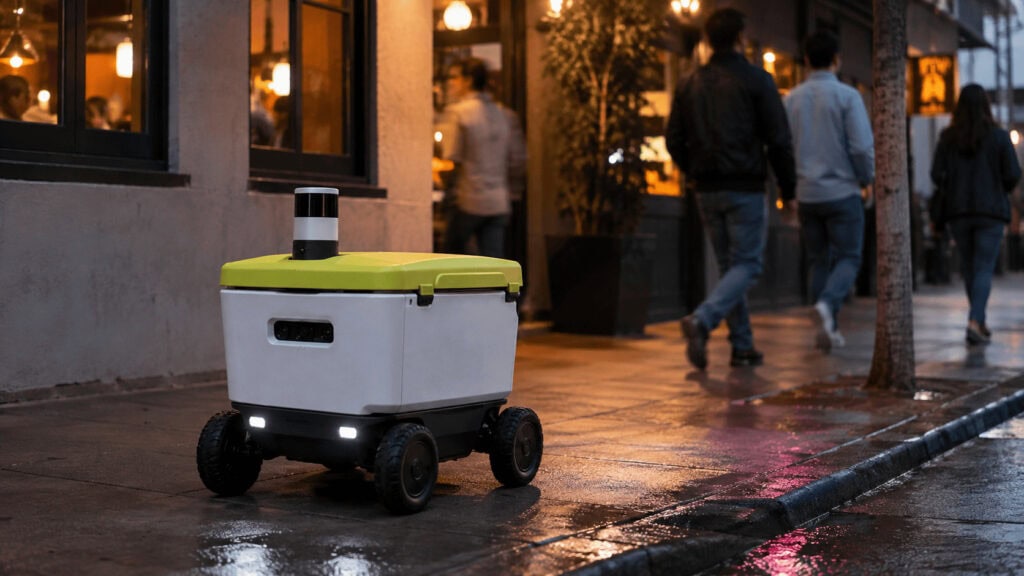
A Serve robot is a white box on four wheels with a lidar mast and a lid that pops open when you tap your phone. It costs money whether it moves or not. In Los Angeles, Miami and Chicago, roughly 1,200 of them sat idle on an average day in the second quarter while Serve reported having more than 2,000 deployed. Nothing broke. The orders stopped arriving.
What Happened
Bloomberg reported Uber’s exit first, working from the filing. Uber had held over two million Serve shares at the end of March, worth $17.5 million at the time. The position is gone from the latest disclosure, which places the sale between April 1 and June 30. Uber had been trimming since early 2025 and redirecting money toward robotaxi bets, and its latest filing shows it adding Rivian and Lucid shares in the same period.
Serve’s CEO Ali Kashani had already told investors on the August 6 earnings call that something changed. Delivery volume through Uber grew for 17 straight quarters starting in early 2022. In the second quarter of 2026 it fell for the first time, which Kashani attributed to robot utilization coming in below expectations. He said the two companies hold <a href=”https://techcrunch.com/2026/08/11/uber-surprised-robotics-company-serve-by-selling-its-entire-stake/”>”differing views”</a> about how to run a shared autonomous fleet, naming fleet coordination and merchant integration. Serve does not expect to renew the agreement when it expires in early 2027.
The quarter itself: revenue of $3.2 million, up 404% from a year earlier and 9% from the first quarter. GAAP net loss of $64.1 million. Cost of revenue of $12.02 million, which is $3.71 of direct cost for every dollar of revenue recognized. Daily active robots averaged 792, down from 812. Daily supply hours fell 4.7%. Cash and marketable securities stood at $240.4 million. The stock closed at $5.68 and dropped to around $5.06 after hours. Guggenheim cut its price target to $7 from $13 while keeping a buy rating.
The Backstory
Serve started as Postmates X, the robotics group inside Postmates. Uber bought Postmates in 2020 for $2.65 billion and spun the robotics division out a year later as an independent company. Uber kept equity and signed a commercial partnership in 2022, then expanded it in May 2023 to authorize up to 2,000 Serve robots across multiple US markets. Nvidia invested too. Serve went public through a reverse merger in April 2024.
The scaling worked. Serve went from about 100 robots to more than 2,000 during 2025, hitting the target its management set. It bought Phantom Auto for teleoperation and Vayu for robotics, then paid roughly $29 million in stock plus a potential $5.3 million earnout for Diligent Robotics, whose Moxi robots run errands inside more than 25 US hospitals. It added DoorDash as a second delivery platform, which on paper gave Serve access to most of the American food delivery market. Read our breakdowns of the Uber business model and the DoorDash business model for how those two platforms allocate demand.
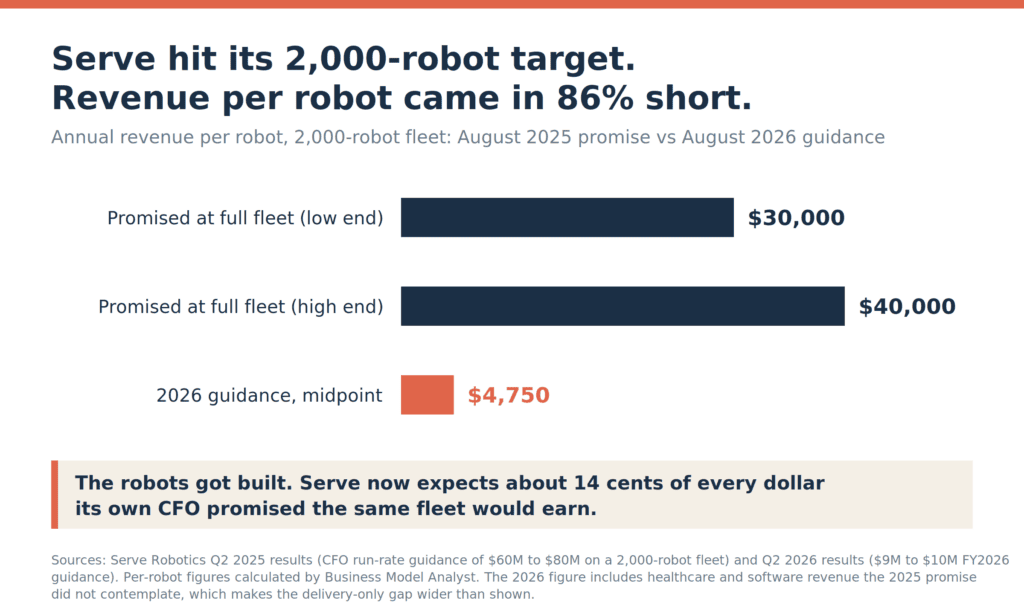
In August 2025, Serve CFO Brian Read told investors the company projected an annualized revenue run rate of $60 million to $80 million once the 2,000-robot fleet reached full utilization. Twelve months later, with the fleet built, Serve guided to $9 million to $10 million for the year.
The Plan
Serve’s answer is to point the fleet at buyers who sign contracts directly with Serve. DoorDash revenue grew close to 50% in a single quarter and beat management’s own forecast. Healthcare came in on plan, with seven multiyear contract extensions and two new hospitals in the first half. Serve added a laundry delivery partner, NoScrubs, to widen the use cases. Recurring revenue crossed half of total revenue for the first time, and gross margin improved from negative 301.6% to negative 271.1%.
Read cut planned non-GAAP operating expense for the year to $140 million to $150 million from $160 million to $170 million and described the new outlook as concentrating fleet and capital behind higher-return work. Serve is not building more robots this year. It is trying to find better tenants for the ones it already owns.
The Business Model Angle
Serve owns the capital. Uber owned the demand allocation. That asymmetry is the whole story, and it explains why the equity sale and the volume collapse are the same event told twice.
Consider what Serve controls. It buys the robot, pays for the lidar, staffs the depot, runs the remote assistance desk, absorbs the sidewalk incidents and carries the depreciation. What it cannot do is decide that a customer in Santa Monica sees a robot delivery option at checkout. Uber makes that call inside its own software, order by order, and Uber has no obligation to explain the logic. Serve reported 792 daily active robots against a fleet above 2,000, which means about 40% of its capital worked on an average day. Serve did not choose that number.
Run the per-robot math. The August 2025 promise implied $30,000 to $40,000 of annual revenue per robot across a 2,000-robot fleet. This year’s guidance implies $4,750, and that figure counts hospital and software revenue the 2025 promise never contemplated. Strip those out and the sidewalk number falls further.
Now compare buyers. Diligent’s roughly 100 Moxi robots operate in more than 25 hospitals, and press coverage of the deal put each hospital deployment at $200,000 to $400,000 a year. That works out to somewhere between $50,000 and $100,000 per robot, against under $5,000 for a sidewalk robot. The hospital robot is slower, more expensive and harder to build. It earns 10 to 20 times more because Serve signs the contract with the hospital and the hospital decides how much work the robot gets. Nobody sits between them adjusting a dial. This is a different argument from the one we made about why the robots making real money don’t look human, where form factor was the variable. Here the form factor is beside the point. The contract is the variable.
The second tell sits in Serve’s own disclosure: advertising made up close to half of food delivery revenue in the quarter. The sidewalk robot earns more as a moving billboard than it does hauling burritos. That is a media business hiding inside a logistics business, and it is the part of the P&L that does not depend on Uber’s dispatcher.
Uber’s side of this is disciplined portfolio management. It runs delivery robot partnerships with Coco, Cartken, Avride and Starship alongside Serve, part of a network of more than 30 autonomous vehicle companies it has partnered with or invested in. No single robot supplier gets pricing power over Uber Eats, and Uber pays nothing to keep the option open. It ended its Phoenix robotaxi partnership with Waymo on June 29, as we covered in the NHTSA robotaxi ultimatum piece. It exited Serve in the same quarter. Both partners had spent a year adding hardware faster than they added work for it, a pattern we measured on the robotaxi side when Waymo went from 10 cities to 15 without moving its weekly ride count. Uber kept its stakes in the companies that supply vehicles and added to Rivian and Lucid. Equity follows scarcity, and sidewalk robots are not scarce.
For any founder building an asset-heavy business on top of an aggregator, the lesson is unpleasant and cheap to learn: your utilization rate lives in someone else’s codebase. Our robotaxi cost stack breakdown argued that fleet operations, not autonomy software, decide these businesses. Serve adds the correction. Fleet operations decide your costs. Your distribution partner decides your revenue.
The Risk
Serve has $240.4 million against non-GAAP operating expense guidance of $140 million to $150 million for this year. That is comfortable for now and thin by 2028 if revenue stays under $20 million.
The bigger risk is repetition. Serve swapped concentration in Uber for concentration in DoorDash, which is larger, better capitalized and runs its own autonomous delivery programs. A partner that can grow your volume 50% in a quarter can shrink it by the same mechanism. Healthcare looks structurally safer, and it is also small, slow to sell and capped by how many hospitals sign in a year.
Then there is credibility. Serve told investors to expect $26 million and delivered a $9 million to $10 million range in the same calendar year, after telling them in 2025 to expect $60 million to $80 million at full fleet. The Uber contract runs into early 2027, so more decline is scheduled, not hypothetical.
Quick Questions
Did Uber’s stake sale cause the revenue collapse? No. The order decline showed up in second-quarter operations, and Uber sold during the same quarter. Both reflect the same decision to pull back. Neither caused the other.
How reliable is the 40% fleet utilization figure? It compares two numbers Serve reports on different bases. “Daily active robots” is an average of robots performing deliveries, and the 2,000-plus figure counts deployed robots, which now include indoor units from Diligent. Treat 40% as directional.
Is the hospital-versus-sidewalk revenue comparison audited? The $200,000 to $400,000 per hospital deployment came from analyst coverage at the time of the Diligent deal, not from Serve’s financial statements. Serve does not break out healthcare revenue. The gap is wide enough that the direction holds even if the estimate is off by half.
Can Serve replace Uber volume with DoorDash? DoorDash revenue grew close to 50% sequentially off a small base. Serve removed projected second-half Uber demand from guidance rather than reallocating it, which suggests management does not expect a clean swap this year.
What should you watch next? Whether daily active robots recover in the third quarter, and whether recurring revenue keeps climbing above half of the total. The first tells you if anyone wants the sidewalk fleet. The second tells you if Serve is becoming a different company.
The Business Model Analyst Take
Serve built exactly what it said it would build. Two thousand robots, on schedule, on budget, the largest sidewalk fleet in the country. The engineering worked. The financing worked. The company still ended up guiding to 14 cents of every dollar its own CFO projected, because the variable that determined the outcome was never on Serve’s org chart.
Uber’s $17.5 million exit is the smallest number in this story and the loudest signal in it. Uber did not need equity to control Serve. It needed an API and a routing preference, both of which it kept for free. When the operating models diverged, Uber changed a parameter and let the market discover the consequence in a guidance revision.
The generalizable lesson is not about robots. Any company that owns depreciating assets and rents demand from a platform is running Serve’s business model, whether that is a fulfillment operator on Amazon, a studio on YouTube or a fleet on Uber. The asset sits on your balance sheet. The utilization sits on theirs. Serve’s move into hospitals is the correct response, and it took a $16.5 million guidance cut to make the case internally. Most companies in that position never get the second act, because they discover the dependency at the moment the platform stops needing them.