
Toyota builds cars in one set of countries and sells them in another. Every external force acting on the company in 2026 is a tax on that gap.
Toyota Motor Corporation finished the fiscal year ended 31 March 2026 with revenue of 50.684 trillion yen, up 5.5%, and operating income of 3.766 trillion yen, down 21.5%. It sold more vehicles than any carmaker on earth for the sixth consecutive year. It also reported a segment loss in North America, its largest market by volume, of 298.6 billion yen.
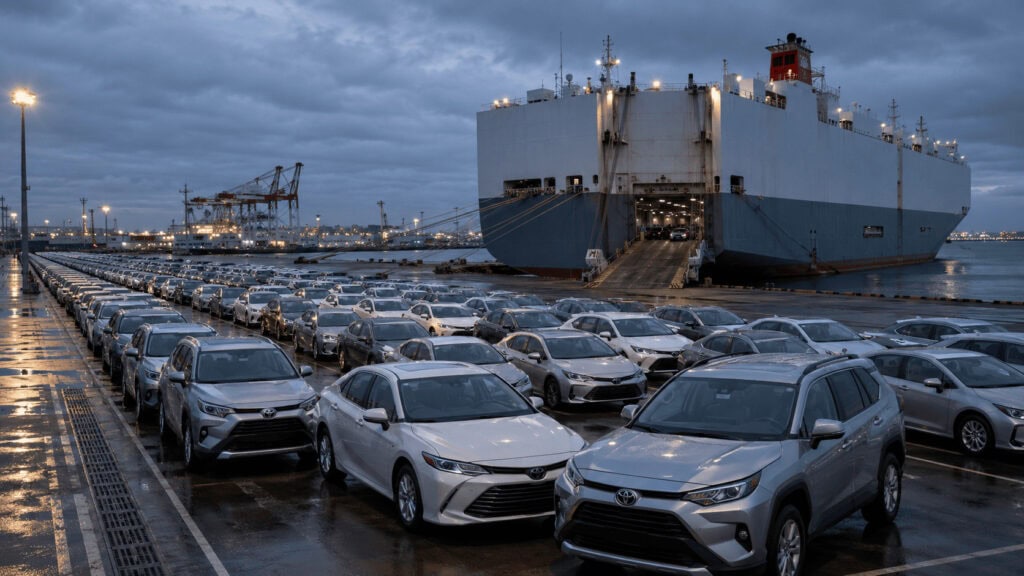
Those three facts belong in the same sentence because they describe one company, and most PESTLE analyses of Toyota never put them together. The standard version lists tariffs under Political, currency under Economic, hybrid demand under Social, and calls it a day. That treatment misses the structure. Toyota’s political, economic, and environmental exposures are the same exposure wearing different clothes: the company manufactures roughly 3.3 million vehicles a year in Japan and books the profit there, while its biggest customer base sits eight thousand kilometers away behind a tariff wall.
This analysis walks the six PESTLE factors with the current numbers, then shows how they converge.
What is a PESTLE analysis? A PESTLE analysis maps the macro-environmental forces a company cannot control: Political, Economic, Social, Technological, Legal, and Environmental. Unlike a SWOT analysis, which mixes internal capabilities with external conditions, PESTLE stays outside the company walls. It answers one question: what is the world doing to this business, and which of those forces will still matter in five years?
Toyota at a glance
| Metric | Latest figure | Period |
|---|---|---|
| Consolidated revenue | 50.684 trillion yen (about $335.7bn) | FY ended 31 March 2026 |
| Operating income | 3.766 trillion yen, down 21.5% | FY ended 31 March 2026 |
| Net income | 3.848 trillion yen | FY ended 31 March 2026 |
| Consolidated vehicle sales | 9,595,000 units | FY ended 31 March 2026 |
| Group global sales | 11,322,575 units, up 4.6% | Calendar 2025 |
| Global production | 11,221,960 units, up 5.7% | Calendar 2025 |
| Largest single market | United States, 2,518,071 units | Calendar 2025 |
| Disclosed US tariff cost | 1,380 billion yen | FY ended 31 March 2026 |
| Current-year operating income forecast | 3.4 trillion yen | FY ending 31 March 2027 |
Currency conversions use Toyota’s stated average rate of 151 yen to the dollar for the year ended March 2026.
Political: the tariff lands on the gap
Washington reset the terms of Toyota’s business in 2025. Section 232 duties of 25% hit imported vehicles from April 2025 and a published list of parts from May 2025. Japan negotiated the rate down: the executive order signed in September 2025 set a 15% ceiling on Japanese automotive products, inclusive of the pre-existing most-favored-nation rate, replacing the 27.5% that had applied. Before January 2025, Japanese passenger cars entered the United States at 2.5%.
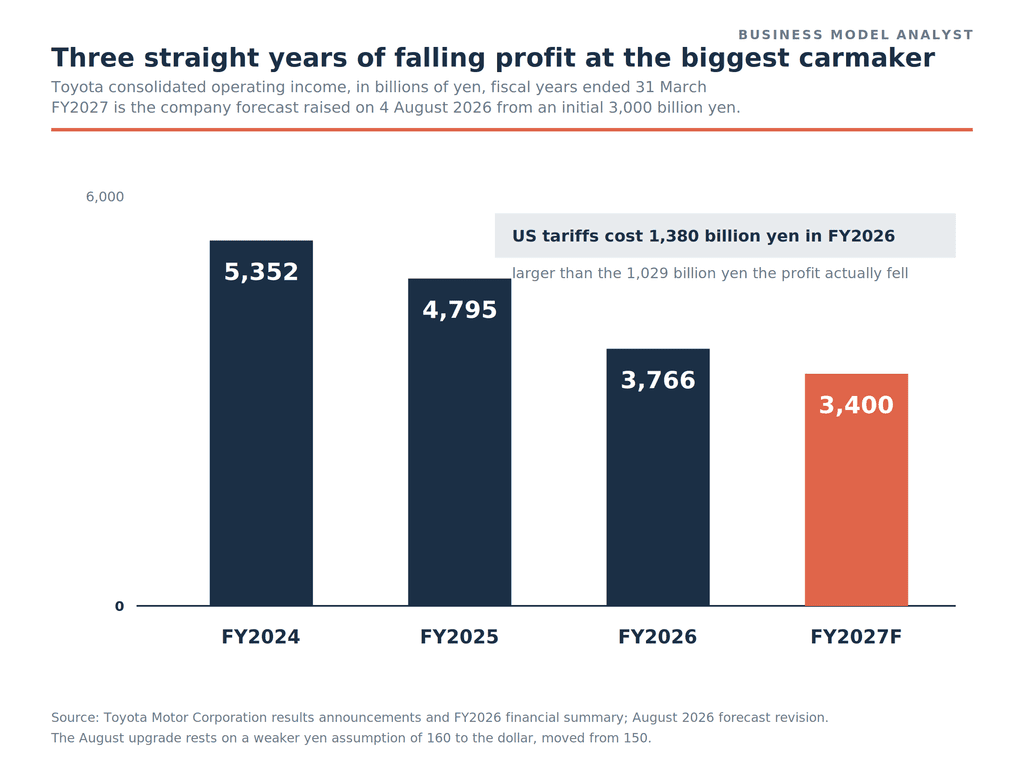
Toyota published the bill. US tariffs reduced operating income by 1,380 billion yen in the year to March 2026, and the company has guided to roughly 2.76 trillion yen of tariff-related cost across the two fiscal years ending March 2027. The Japan Times put the combined figure for six major Japanese automakers above 2.4 trillion yen for the year to March 2026 alone.
Run that against the income statement and the arithmetic gets uncomfortable for anyone arguing Toyota’s operations deteriorated. Operating income fell 1,029 billion yen. The disclosed tariff cost was 1,380 billion yen. On Toyota’s own bridge, the trade regime cost more than the entire decline, which means the rest of the business improved while the reported number went backwards.
Toyota’s political response has been capital, not lobbying. The company runs 11 US plants with roughly 50,000 employees and has invested close to $60 billion in the United States since it started building there. It opened a battery plant in Liberty, North Carolina in November 2025 at a cost near $13.9 billion, its first outside Japan, and committed up to $10 billion more over five years on the same day. Another 912 million dollars went across US plants for hybrid production, followed by a further $1 billion in March 2026 split between Georgetown, Kentucky and Princeton, Indiana.
Two political risks sit under that spending. The Supreme Court struck down the IEEPA tariff authority in February 2026, and the administration has since reached for other statutes, so the rate Toyota plans against is a policy choice rather than a settled rule. And factory decisions take four years while tariff rates change in an afternoon. Toyota is committing fixed capital against a variable it cannot forecast.
Economic: the currency does the work
Toyota raised its operating income forecast for the year ending March 2027 on 4 August 2026, lifting it 400 billion yen to 3.4 trillion. Read the bridge and the raise came from the foreign exchange assumption moving from 150 to 160 yen per dollar. The dollar line alone contributed about 420 billion yen. The operating business went backwards inside a forecast that went up.
The same pattern showed in the quarter. In the three months to June 2026, revenue rose 10.4% to 13,525.4 billion yen while operating income fell 8.8%. Net income jumped 75.6%, driven by the partial disposal of the Toyota Industries stake and the deconsolidation of Hino rather than by selling cars.
A weak yen flatters Toyota because the company exports from a high-cost country into dollar and euro markets. That is the same structural fact that makes tariffs expensive. Both forces act on the distance between the factory and the customer. Toyota cannot hedge its way out of either, because the exposure is the manufacturing footprint itself.
Interest rates form the second economic pressure, and they hit through the showroom rather than the balance sheet. Financial services delivered 709.8 billion yen of operating income in the year to March 2026, up 36.1 billion, while affordability constrained what Toyota could charge for the vehicles that lending supports. Japanese automakers passed through very little of the tariff cost. Toyota ran regular price revisions and nothing more, which tells you what the company thinks its pricing power is worth in a market where a competitor building in Kentucky pays no import duty at all.
Social: buyers picked the hybrid
American buyers spent 2026 walking away from battery electric vehicles. Automakers sold 462,892 all-electric vehicles in the first half of 2026 according to Cox Automotive, down 23.8% year on year, with EV share falling to about 6% of the quarter from a peak near 11%. Hybrids are tracking about 9% growth for the year against roughly 2% for the overall light-vehicle market.
That reversal validated a product mix Toyota had been criticized for since 2021. Look at what the company actually sold worldwide.
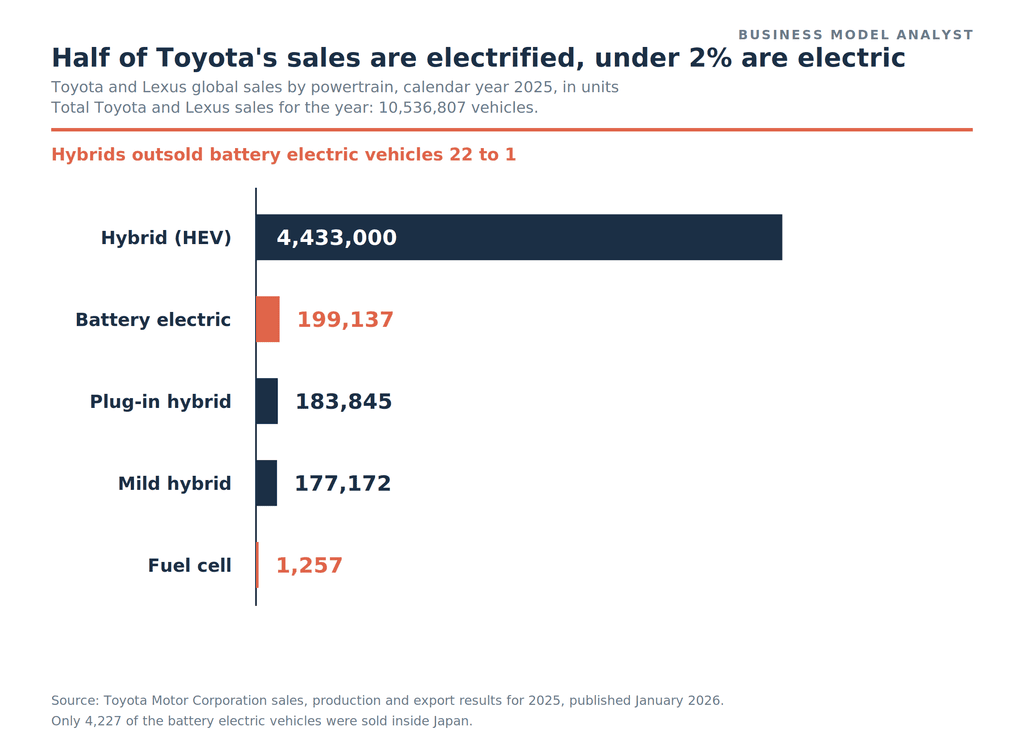
Electrified vehicles reached 4.994 million units in 2025, up 10.2%, which is 47.4% of the 10,536,807 Toyota and Lexus vehicles sold. Battery electric vehicles were 199,137 of them, or 1.9%. Hybrids outsold pure electrics by a factor of 22. In Japan, Toyota and Lexus sold 4,227 battery electric cars for the entire year.
The commercial logic holds up. A RAV4 Hybrid asks the buyer to change nothing: no charger, no route planning, no second vehicle for long trips, and a sticker price close to the gasoline version. Toyota converted a regulatory hedge into the highest-volume product line in the industry.
The social risk runs the other direction, and it sits outside the United States. Emerging markets are expected to make up around 60% of global car demand over the next decade, and Chinese brands already hold roughly 60% of electric vehicle sales in those markets against about 10% of combustion sales. In Southeast Asia, Japanese brands lost more than ten points of share between 2023 and 2025, falling to 57% according to PwC. Toyota is winning the customer who wants a familiar car and losing ground with the customer buying a first car in a market where a Chinese electric model arrives cheaper than the Corolla.
Technological: a portfolio of options, priced as insurance
Toyota calls its approach multi-pathway. In business model terms it is an option portfolio: the company holds live positions in hybrid, plug-in hybrid, battery electric, and hydrogen powertrains, and pays for optionality it may never exercise. Fuel cell sales fell 29.3% in 2025 to 1,257 units, which is the cost side of that portfolio made visible.
Solid-state batteries are the position that matters. Toyota targets a first battery electric vehicle with all-solid-state cells in 2027 or 2028, debuting on Lexus where the price point can absorb early cell costs. Idemitsu Kosan broke ground on a solid-electrolyte plant on 29 January 2026 with completion due by the end of 2027, and Sumitomo Metal Mining signed on for cathode materials. The launch year has moved before, from 2020 to 2023 to 2026 and now to 2027 or 2028, so treat the date as a target rather than a schedule.
The competitive clock is running in China. Chinese manufacturers build an electric vehicle for roughly 35% less than European producers, and BYD reported an overseas automotive gross margin of 28.1% against 17.2% at home. Toyota’s counter is to localize the battery supply chain in the markets that will buy the cars, which is what the North Carolina plant and the Kentucky electric SUV line are for. Production of a US-built electric model began at Kentucky in 2026 with a second model due in 2027, taking Toyota’s American battery electric lineup toward seven models.
Note the shape of that answer. Toyota is not solving a technology problem. It is moving manufacturing closer to demand, which is the same move the tariff forced and the same move the currency rewards.
Legal: the family tightens its grip
The most consequential legal development for Toyota in 2026 had nothing to do with vehicles. Toyota Fudosan, the unlisted group real estate company chaired by Toyota chairman Akio Toyoda, took Toyota Industries private. The bid opened at 16,300 yen per share in June 2025 and closed at 18,800 yen after two increases, a 42.16% premium to the undisturbed price of 25 April 2025.
Elliott Investment Management, the largest independent minority holder, put intrinsic net asset value at 26,134 yen per share, close to 40% above the final offer, and argued the buyer was acquiring the operating business at under one turn of EBITDA once the cross-shareholdings were valued. Elliott sold its 7.7% stake on the revised terms and called the outcome an improvement. The Asian Corporate Governance Association kept its objections on the record, pointing to conflicted parties inside the majority-of-minority safeguards. Toyota Motor recorded 3,656.8 billion yen in its fourth quarter for shares to be repurchased through the process.
Japan spent a decade telling listed companies to unwind cross-shareholdings and protect minority investors. The largest corporate group in the country unwound its cross-shareholdings by moving them inside a private vehicle controlled by the founding family. Both descriptions are accurate, which is why the transaction became the test case it did.
Two other legal threads shape the group. Hino Motors left Toyota’s consolidated accounts on 1 April 2026 through its integration with Mitsubishi Fuso under an agreement struck with Daimler Truck in June 2025, which removes a subsidiary that had already cost the group a $1.6 billion US emissions settlement. And the certification failures at Daihatsu and Toyota Industries that halted shipments in 2024 left the group carrying a compliance overhang that regulators in Japan have not forgotten.
Environmental: the rules moved toward Toyota
The European Commission proposed on 16 December 2025 to replace the 2035 requirement for 100% CO2 reduction on new cars and vans with a 90% target, allowing plug-in hybrids, range extenders, and combustion vehicles to stay on sale past 2035 provided the remaining 10% is offset with low-carbon EU steel, e-fuels, or biofuels. The 2030 target for cars becomes an average across 2030 to 2032, and vans drop from 50% to 40%. The European Parliament and Council are negotiating the file through 2026, so it is a proposal rather than law.
In the United States, Congress ended the consumer electric vehicle credit, and the demand data followed within two quarters. The International Council on Clean Transportation estimates the European change alone adds at least one billion tonnes of CO2.
For Toyota, both moves reduce the probability of the scenario the company was accused of ignoring. Toyota holds a 2050 carbon neutrality commitment and has argued for years that lifecycle emissions across a large hybrid fleet beat a small electric one, an argument that regulators rejected in 2022 and are now partially conceding. The company hedged against a regulatory outcome and the regulators blinked.
The residual environmental risk is timing rather than direction. Rules that loosen can tighten again, and Toyota’s manufacturing base carries a heavier combustion mix than any rival its size. Should Europe or California re-accelerate after 2030, the fleet that looks prudent in 2026 becomes the fleet that needs replacing fastest.
The finding: the profit map and the sales map do not overlap
Toyota reports operating income by region before interest-rate swap valuations. Set the segments side by side for the year to March 2026 and the company’s real exposure appears.
| Region | Vehicle sales | Segment operating income | Change year on year |
|---|---|---|---|
| Japan | 2,082,000 | +2,330.7bn yen | -828.0bn |
| Asia | 1,759,000 | +872.3bn yen | -21.6bn |
| Europe | 1,183,000 | +330.8bn yen | -86.3bn |
| Other regions | 1,637,000 | +307.8bn yen | +67.3bn |
| North America | 2,934,000 | -298.6bn yen | -402.9bn |
| Financial services | n/a | +709.8bn yen | +36.1bn |
North America sold the most vehicles and produced the only loss. Japan sold 29% fewer units and earned 2.3 trillion yen. Segment profit follows the location of the selling and manufacturing entity, so the Japan figure includes the margin on vehicles built in Japan and shipped abroad, and transfer pricing decides where the profit lands. That accounting convention is exactly the point: the convention is a map of where Toyota’s value is created, and it sits in the wrong country relative to its customers.
Trace North America over three years and the tariff arrives with a date stamp.
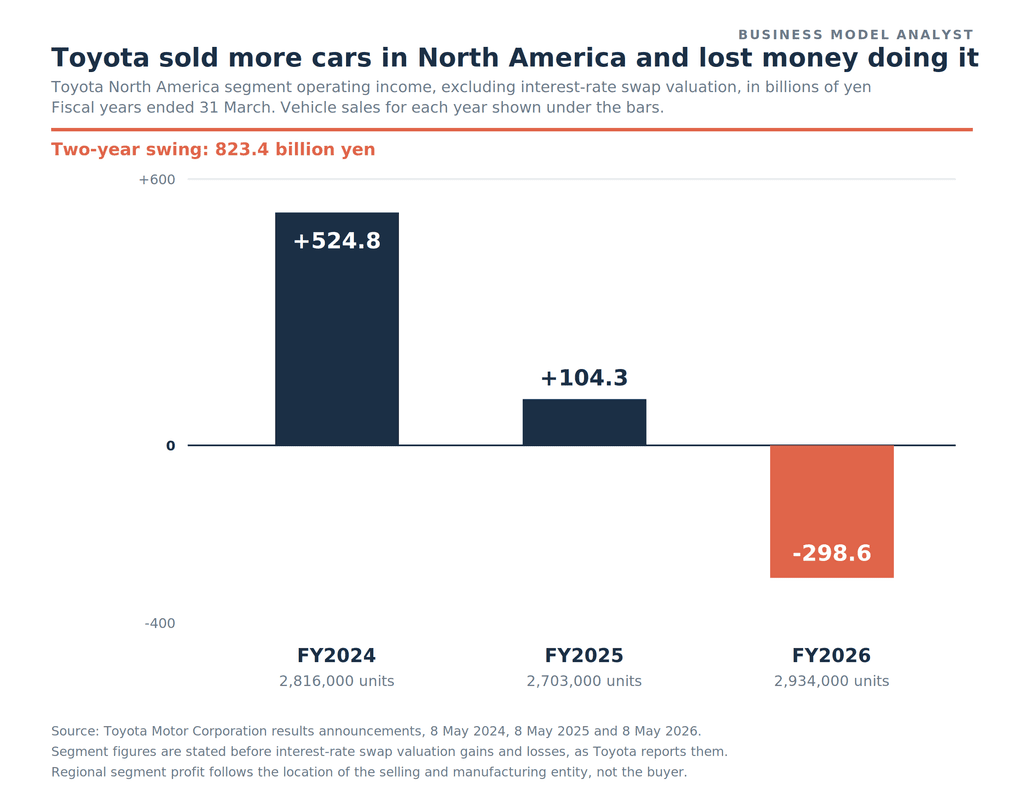
The segment earned 524.8 billion yen in the year to March 2024, 104.3 billion in the year to March 2025, and lost 298.6 billion in the year to March 2026. Volume moved from 2,816,000 units to 2,703,000 and back up to 2,934,000. Toyota sold 118,000 more vehicles in North America than it had two years earlier and its profit there fell by 823.4 billion yen.
Per vehicle, North American segment profit went from about 186,000 yen to about 38,600 yen to negative 102,000 yen. At 151 yen to the dollar, Toyota’s best-selling region moved from earning roughly $1,230 per car to losing roughly $670. The Japan segment earned about 1.12 million yen per regional unit over the same year, which is the export margin showing up on the wrong side of the ocean.
That is the whole PESTLE in one table. Tariffs tax the gap between build location and sale location. Currency revalues it. Emissions rules price the products that cross it. The Toyota Industries buyout restructures who owns the assets sitting on the Japanese side of it. Toyota’s answer to all six factors is the same answer: move more of the value chain to where the customers are, and accept lower peak margins in exchange for a smaller policy surface. Read the Toyota value chain analysis for how those activities currently link together.
The risk to this reading
Three arguments cut against it, and they are strong.
Segment accounting is a booking convention. Toyota decides the transfer prices between its Japanese manufacturing entities and its North American sales entities, and those prices determine which segment shows the loss. A different convention would move profit across the Pacific without a single operational change. The regional split describes where Toyota books value, and a critic can read the North American loss as a reporting artifact rather than an economic one.
Toyota is still winning. The company sold 11.3 million vehicles in 2025 against Volkswagen’s 8.98 million, produced 11.2 million, raised its dividend to 100 yen, and guided to 3.4 trillion yen of operating income after absorbing a two-year tariff bill approaching 2.8 trillion. Very few businesses can lose that much to a policy change and still print those numbers.
The hedge worked. Toyota spent five years being told its refusal to go all-electric was a strategic failure. American EV demand fell 23.8% in the first half of 2026, Europe softened its 2035 rule, and hybrid volume kept compounding. Any analysis that treats Toyota’s position as fragile has to explain why the company holding the largest hybrid fleet on earth is the one exposed.
The counter to all three is timing. Toyota’s advantage in 2026 comes from products designed for a world where charging is inconvenient and gasoline is expensive. Its exposure comes from a manufacturing base built for a world where trade was cheap. The first condition may hold for a decade. The second one already ended.
Frequently asked questions
What are the biggest external threats to Toyota in 2026? US trade policy and the yen. Toyota disclosed 1,380 billion yen of tariff cost for the year to March 2026 and expects roughly 2.76 trillion yen across two fiscal years, while its raised profit forecast depends on a currency assumption of 160 yen to the dollar rather than improved operations.
Is Toyota’s hybrid strategy working? Commercially, yes. Toyota sold 4.433 million hybrids in 2025, 22 times its battery electric volume, and US hybrid demand is growing about 9% in 2026 while pure electric sales fell 23.8% in the first half.
Why did Toyota lose money in North America? Toyota reported a North America segment operating loss of 298.6 billion yen for the year to March 2026, before interest-rate swap valuations. Tariffs on Japanese-built vehicles and parts landed on a region where Toyota imports a large share of what it sells, and the company chose not to pass the cost through in price.
How exposed is Toyota to Chinese electric vehicle competition? More in emerging markets than at home. Chinese brands hold around 60% of electric vehicle sales in emerging markets that are expected to account for roughly 60% of global demand over the next decade, and Japanese brands lost more than ten points of Southeast Asian share between 2023 and 2025.
When will Toyota launch a solid-state battery car? The company targets 2027 or 2028, on Lexus first and in limited volume. Idemitsu Kosan began building the solid-electrolyte plant in January 2026 with completion due by the end of 2027. Earlier target dates of 2020, 2023, and 2026 all slipped.
What did the Toyota Industries take-private change? It moved a major group company holding significant cross-shareholdings out of the public market and into Toyota Fudosan, an unlisted vehicle chaired by Toyota’s chairman, at 18,800 yen per share against Elliott’s 26,134 yen net asset value estimate. Governance bodies treated it as a test of Japan’s minority shareholder protections.
The Business Model Analyst Take
Toyota’s macro-environment is legible once you stop reading it as six separate risks. The company built the most efficient manufacturing system in industrial history inside one country, then sold the output everywhere else, and for forty years cheap trade made that arrangement look like genius. It still is a good arrangement. It has become an expensive one.
Every 2026 headline resolves to the same variable. The tariff is a tax on distance. The yen assumption is a repricing of distance. The battery plant in North Carolina is a payment to shorten distance. Even the Toyota Industries buyout is about consolidating control over the Japanese end of a supply chain whose other end keeps getting more expensive to reach.
What makes Toyota interesting is that its product strategy and its manufacturing strategy are pulling in opposite directions. The hybrid bet won because Toyota refused to follow a consensus that turned out to be wrong about consumers. The manufacturing footprint is losing because Toyota followed a consensus that turned out to be wrong about trade. Same company, same decade, opposite outcomes from the same instinct to stay with what works.
The number worth watching is not global volume, and it is not the operating income headline that moves with the currency. It is North American segment profit. Toyota has committed tens of billions of dollars to fix that line by building more of what it sells where it sells it. If the segment is back above zero by the fiscal year ending March 2028, the localization worked and the tariff cost Toyota two years of profit. If it is still negative with all that capital deployed, then the problem was never the tariff, and the most efficient manufacturer in the world will have discovered that its efficiency was partly a currency and partly a trade regime. Compare the same question from the other side of the market in our analysis of how GM and Toyota use their factories, and see the Toyota business model for how the company earns money across vehicles, parts, and financing.