
Match Group is scaling Tinder’s in-person Events from 10 cities to 75 by year-end, betting that off-app hangouts can fix an on-app problem: three straight years of shrinking users.
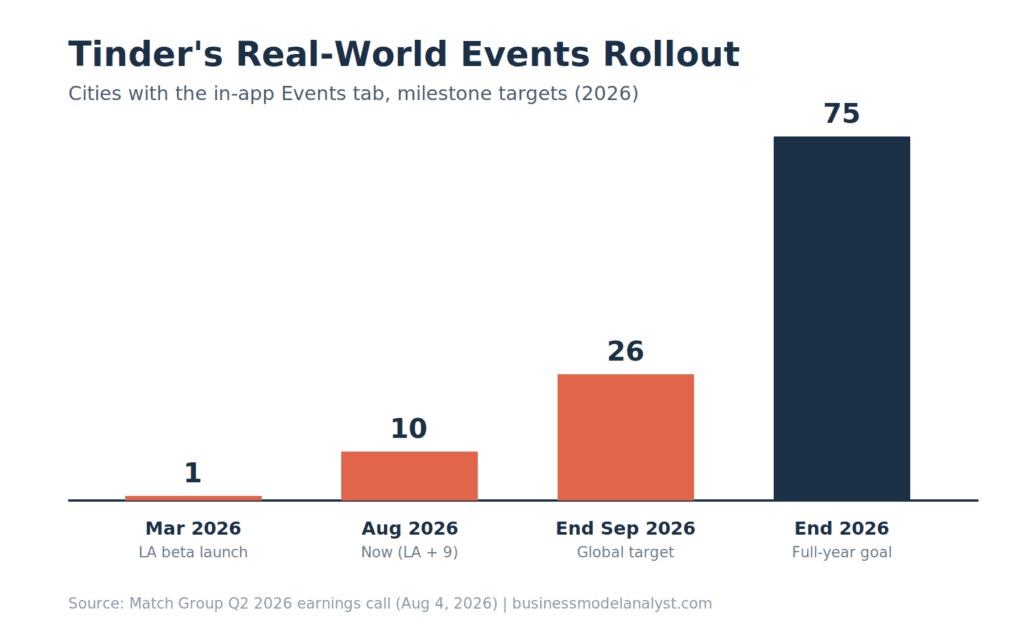
On its Q2 2026 earnings call, Match Group said Tinder’s Events tab will reach 26 cities by the end of September and 75 by the end of 2026, up from 10 today. The feature does not sell tickets or run the events itself. It is a low-cost discovery layer built on partnerships with outside event providers, designed to reposition the brand and pull in the roughly 60% of singles who currently refuse to touch a dating app. Match’s stock still fell more than 10% after hours, because the core numbers have not turned yet.
Tinder has a problem money cannot buy its way out of: young people are logging off. So Match Group’s fix is almost counterintuitive. Instead of pouring more into the app, it is spending to get users out of it, into speakeasies, bowling alleys, raves and pottery classes, and hoping they come back with a better opinion of the brand.
What Happened
On Tuesday, August 4, Match Group (NASDAQ: MTCH) reported second-quarter results and used the call to lay out an aggressive expansion of Tinder’s in-person Events feature. CEO Spencer Rascoff told analysts the Events tab, which launched as a Los Angeles test in March, has since rolled out to nine more cities in the US and Europe, will hit 26 cities globally by the end of September, and is targeted for 75 cities by the end of 2026.
The financial backdrop was mixed. Total revenue came in at $853 million, down 1% year over year, while adjusted EBITDA rose 14% to $331 million and net income jumped 36% to $171 million. Tinder’s own direct revenue was $457 million, also down 1%. The market focused on the soft spots: Tinder monthly active users fell 7% (an improvement from last quarter’s 8% drop), and the stock slid more than 10% in after-hours trading.
The bright spot Rascoff kept pointing to was daily active users. Tinder’s DAU decline narrowed to 4% in Q2, its best result in ten quarters, was down to about 2.5% in July, and was “almost positive” in early August. A return to positive year-over-year usage would be Tinder’s first in more than three years.
The Backstory
Tinder built the modern dating economy on a simple mechanic: swipe, match, pay for the shortcuts. Its freemium business model turned attention into subscriptions (Tinder Plus, Gold, Platinum) and a la carte boosts and super-likes. For a decade, that engine only needed one thing to keep running: a dense, growing pool of active users.
That pool started draining. Culture turned on the endless swipe, “dating app fatigue” became a genre of think-piece, and Gen Z began treating the apps as a chore rather than a night out. Match’s own internal research now confirms it: nearly half of singles aged 18 to 29 say they want to share in-person experiences with people who could become real connections, and about three in five non-users say events would make them more likely to try the app.
Match, which owns Tinder alongside Hinge, OkCupid, Match, Plenty of Fish and others, has watched Hinge become its growth story (revenue up 22% to $204 million in Q2) while Tinder, still the cash cow, kept sliding. Events is one leg of a three-part Tinder rescue plan: faster AI-driven product changes, a brand refresh, and real-world meetups.
The Plan
Here is the clever part, and the part worth studying if you build products. Tinder is not becoming an events company. Rascoff described Events as a “low-cost model built primarily around partnerships with leading event providers.” Tinder does not book the venue, run the raves or teach the pottery class. It curates and surfaces other people’s events inside a dedicated Events tab, then takes the credit for the vibe.
That keeps the whole thing asset-light. No inventory, no venue leases, no event-ops headcount, near-zero marginal cost to add another city. It also throws off exactly the kind of behavioral data Match would want if it ever decided to run events directly. The early read from Los Angeles was strong enough to justify the push: 71% of Tinder’s active users in LA aged 18 to 24 engaged with the new sections, and the company has featured more than 60 events since March. Match is now wiring the same Events platform into other brands, with BLK expected to adopt in-app events by Q4.
The Business Model Angle
Strip the romance out of it and Tinder is a two-sided marketplace whose only real asset is liquidity: enough active, desirable users on both sides that matches feel plentiful. Everything Tinder monetizes (subscriptions, boosts, super-likes) is a tax on that liquidity. When the user base shrinks, liquidity thins, matches feel worse, and the willingness to pay evaporates. That is the doom loop Match is fighting.
Events do not touch the monetization layer at all. There is no ticket revenue, no new subscription tier. So why spend on it? Because Events is a top-of-funnel and brand-repositioning play, not a revenue line. Its job is to reframe Tinder from “hookup app you are slightly embarrassed to have” into “the easiest way to meet people in your city,” and to reach the 60% of singles the app cannot currently convert. If it widens the funnel and lifts DAU, the existing monetization engine does the rest. It is a cheap option on fixing liquidity, paid for by someone else’s event logistics.
There is also a deeper tension baked into dating economics that Events quietly acknowledges. A dating app’s product goal (help you find a partner) is the opposite of its revenue goal (keep you single and swiping). Success for the user is churn for the company. Events lean into engagement and connection rather than resolution, which is a smart way to grow usage without promising the one outcome that would kill the subscription.
The Risk
The obvious risk: Events do not make money, and enthusiasm is not a P&L line. Match is spending real marketing and partnership effort on a feature whose entire thesis rests on indirect brand lift. If DAU stalls out below the zero line, this becomes a nice story with no financial payoff.
Then there is the paradox. If real-world meetups actually work, people meet someone and delete the app. Tinder is funding the exact behavior that ends its subscription relationship. The company is betting the funnel-widening effect (new and returning users) outweighs the graduation effect (satisfied users who leave), but that math is unproven at 75-city scale.
Execution risk compounds it. Partner-run events mean Tinder’s brand is exposed to experiences it does not control, across dozens of cities, in a category where one creepy or unsafe night out becomes a viral headline. And underneath all of it, the core metric still points down. MAU fell 7%. The turnaround is a hypothesis with promising early signals, not a result.
Quick Questions
Does Tinder make money from the events? No. Tinder does not sell tickets or run the events. It surfaces third-party events in an in-app tab, so the model is asset-light and the payoff is brand and engagement lift, not direct revenue.
How many cities will have Events? 10 today, 26 by the end of September 2026, and a target of 75 by the end of 2026.
Is Tinder actually recovering? Partly. Daily active user declines narrowed to 4% (best in ten quarters) and were “almost positive” in early August, but monthly active users still fell 7% and revenue dipped 1%.
Why did the stock drop if EBITDA was up? Adjusted EBITDA rose 14%, but investors fixated on Tinder’s continued user and revenue declines, sending shares down more than 10% after hours.
The Business Model Analyst Take
This is a smart, cheap bet on the right problem. Match correctly diagnosed that Tinder’s issue is not pricing or features, it is that the top of the funnel is collapsing as Gen Z sours on swiping. Throwing an asset-light, partner-powered brand play at that problem is exactly the kind of high-option, low-cost move a mature platform should make when its core is eroding. The 71% engagement figure in LA is genuinely encouraging, and letting other people carry the event risk while Tinder harvests the goodwill and the data is elegant.
But do not confuse a clever funnel move with a fixed business. Events is a vitamin, not the cure. The cure is positive user growth, and Tinder is still waiting on it after three years. The uncomfortable truth is that the healthiest version of Tinder’s brand (people meeting in real life and forming relationships) is also the version where they stop paying. Events buys Tinder time and reach. Whether it buys durable revenue depends entirely on that DAU line finally crossing zero and staying there. Watch that number, not the city count.