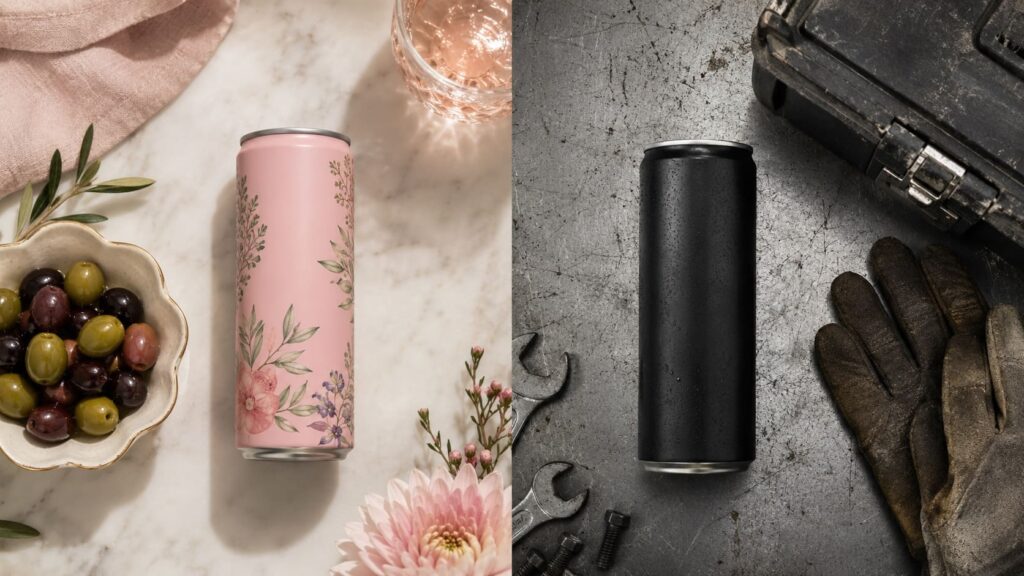

The non-alcoholic substitution opportunity, defined: The fastest-growing slice of beverage is not “healthy drinks” in general. It is the narrow category of products built to replace a specific alcoholic occasion, the beer at the cookout, the cocktail after work, the round at the bar. Packaged Facts projects this substitution segment will grow about 18.5% a year through 2029, roughly three times the broader non-alcoholic beverage market. Yet most of the brands chasing it are aimed at one customer. That gap is the business opportunity.
Picture a non-alcoholic drink brand. Odds are you just imagined the same thing everyone else does: a pastel can, a botanical name, a founder story about slowing down, and a marble countertop with a single bowl of olives nearby. That picture is not a coincidence. It is the entire category converging on one buyer.
The instinct for an operator looking at a hot category is to build a slightly better version of the leader. That instinct is wrong here. The leaders are not under-built. They are narrowly aimed. The money sitting on the table is not a prettier aperitif. It is the same underlying product pointed at the people the current brands were never designed for.
This is a positioning story before it is a product story, and positioning is where most beverage founders lose. Below is what the category actually looks like, why the white space is real and not wishful thinking, and the honest reasons it is harder to capture than a quick read of the trend suggests.
The market case is strong, and it is specific
The headline most founders chase (“non-alcoholic is booming”) is true but too blunt to act on. The booming part is concentrated in one segment.
| Segment | Projected annual growth | What it actually covers |
|---|---|---|
| NA alcohol alternatives | ~18.5% through 2029 | Drinks built to replace beer, wine, spirits, cocktails |
| Functional beverages | ~9.2% (2026 to 2033) | Adaptogen, vitamin, gut-health drinks |
| Total non-alcoholic beverages | ~6.0% (2024 to 2030) | Everything from soda to bottled water |
Sources: Packaged Facts (alternatives), Grand View Research (functional and total).
The distinction matters for where you put your money. A drink that competes as “wellness” lands in the 9% lane against Poppi, Olipop, and a hundred prebiotic sodas. A drink that competes as “the thing you hold instead of a beer” lands in the 18% lane with far less crowding. Same liquid, different shelf, very different growth math. (For how a functional-beverage challenger built its position from a narrow start, see our breakdown of the Poppi marketing strategy.)
The demand driver underneath the number is generational and durable, not a Dry January stunt. Gallup data shows only about 62% of US adults under 35 report drinking alcohol, down from roughly 72% two decades ago. When the youngest cohort of legal-age adults drinks less than any generation on record, “I am not drinking tonight” stops being an occasional exception and becomes a standing condition that needs its own products.
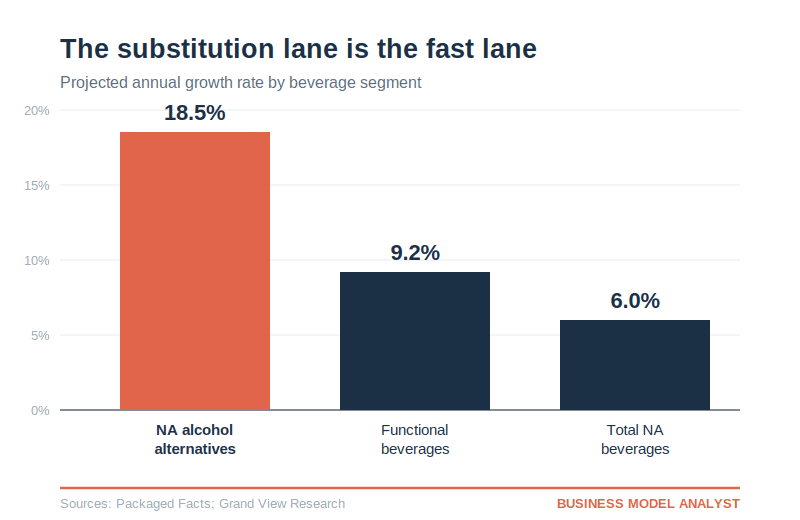
Information gain: The growth is not evenly spread across the non-alcoholic shelf. The substitution segment is growing at roughly triple the rate of the category it sits inside. Founders who frame their drink as “wellness” are competing in the slow lane by accident.
What De Soi and Ghia actually got right
De Soi, the non-alcoholic aperitif co-founded by Katy Perry and master distiller Morgan McLachlan, is the brand most people point to. It raised a $4 million seed round in 2022 and expanded into Erewhon, Boisson, Total Wine, and Amazon. Ghia, a Mediterranean-style non-alcoholic aperitif, sits alongside it as the other frequently cited leader. Third-party direct-to-consumer sales trackers rank both near the top of the celebrity and design-led NA aperitif tier, though as private companies their exact revenue figures are estimates, not disclosed numbers, and should be treated that way.
The lazy read is “celebrity slapped a name on fancy juice.” That misreads the move. The transferable insight is not the celebrity. It is the emotional reframe.
For decades the non-alcoholic option at a table was the consolation prize: club soda with a lime, the “I am driving” drink, the thing you held while apologizing for holding it. De Soi took that exact moment, the moment you order the boring thing, and made the boring thing the most attractive object on the table. Not-drinking became an upgrade rather than a deprivation.
That reframe is the whole category thesis in one sentence: give the person who is not drinking something they are proud to be holding. The problem is that De Soi and Ghia nailed it for exactly one persona, the design-literate host pouring a Sunday spritz on the patio. That is a real customer. She is not the whole market.
The proof that the reframe scales: Athletic Brewing
If you want evidence that the “proud to hold it” reframe works beyond the aesthetic-host buyer, look at non-alcoholic beer.
Athletic Brewing took the same emotional move and pointed it at a completely different person: the active, performance-minded adult who wanted a beer with the run crew, the tailgate, or the post-workout hang minus the alcohol. No flowers, no marble counter. The result is a brand reportedly valued at around $800 million in its 2024 round led by General Atlantic, on more than $100 million in 2023 revenue, now the best-selling beer brand at Whole Foods ahead of alcoholic options.
| Brand | Buyer it was built for | Reframe |
|---|---|---|
| De Soi / Ghia | Design-literate host, dinner and spritz occasions | “Sober is sophisticated” |
| Athletic Brewing | Active, performance-minded adult | “Sober is high-performance” |
Two brands, same underlying insight, two different people, two large businesses. That is the tell. The reframe is not buyer-specific. The execution is. Which means the number of viable brands in this category is roughly equal to the number of distinct drinking occasions and identities you can credibly serve.
Where the open lanes are
Think about how finely the alcohol industry segments by occasion and identity. There is a beer for the tailgate, a whiskey for the poker night, a tallboy for the job site, a shot for the bachelor party, a natural wine for the dinner party. Each one is a different product, package, and message aimed at a different moment.
Now look at the non-alcoholic substitution shelf. For most of these occasions, the only option on offer is a pink botanical spritz built for one persona. The asymmetry is the opportunity.
| Open lane | The customer | Why current brands miss it |
|---|---|---|
| The crew / poker night | The one guy not drinking tonight | Will not hold a floral rosé spritz; wants something that reads like the real drink |
| The job site / blue-collar 5pm | Quit drinking, still wants the cold-one ritual | Does not want a “wellness elixir” or a ritual; wants the crack and the hiss |
| The sports bar | Watching the game, early start tomorrow | Ordering a “sober drink” at a bar feels like outing yourself; needs an on-tap option nobody clocks |
| The gym / recovery crowd | Traded drinking for training | Only options are pastel adaptogen cans or NA beer; no masculine-coded wind-down drink exists |
None of these require a new liquid. They require a different name, package, channel, price point, and message. The product is close to solved. The positioning is wide open.
The strategic principle worth internalizing, well beyond beverage: when every brand in a hot category looks suspiciously alike, they are usually fighting over one customer profile and ignoring everyone else with the same underlying need. The win is rarely to out-pretty the leader. It is to find the person the leader was never built for and build the thing that is obviously theirs. This is occasion-and-identity segmentation, the same lens that lets a single company sell to a festival teenager and a parent buying a family multipack (see the layered approach in our Coca-Cola target market breakdown).
The skeptic’s case: why this is harder than it looks
A clean white-space map is seductive, and seduction is exactly when you should slow down. Here are the reasons this is not free money, and any operator should price them in before formulating a single batch.
“Underserved” can mean “tried and failed.” The aesthetic-host buyer is not who every brand serves by accident. She buys at premium price points, posts the can, and tolerates DTC shipping economics. The job-site worker and the sports-bar regular may be culturally underserved and also structurally harder to monetize: more price-sensitive, less likely to pay $6 a can, harder to reach without expensive retail and on-premise distribution. The current brands may be aimed where the willing money is, not where the headcount is.
Masculine-coded NA is a graveyard, not virgin territory. Plenty of brands have tried to sell men a non-alcoholic drink that is not beer. Most failed because the male “not drinking” customer often just buys Athletic, or a Liquid Death, or a regular soda, and feels no need for a dedicated identity brand. The absence of a product is not always proof of demand. Sometimes it is proof that the need is already met by an adjacent product.
Beverage is brutal on margin and capital. This is not a digital product. Co-packing, formulation, canning, cold chain, retail slotting fees, and distributor margins eat founders alive. The reason so many NA brands cluster in premium DTC aesthetics is that it is one of the few positions where the unit economics survive. Going mass-market and masculine often means going head to head with companies that have vastly deeper distribution, including the alcohol giants who have all launched NA lines.
Athletic already owns the masculine-performance lane. The single most attractive “open” lane, the active recovery-minded man, is arguably not open. Athletic has ~19% NA beer share, national distribution, and a Keurig Dr Pepper investment behind it. A new entrant there is not finding white space; it is attacking an entrenched leader.
The honest read: the occasion-segmentation thesis is directionally right, but the most valuable-looking lanes are either already contested or structurally harder to monetize than the patio. The real edge is probably a narrower wedge: one specific occasion, one specific channel, defended with sharp branding and a distribution angle the incumbents cannot easily copy. (The hardest part is almost always distribution, which is why the alcohol-adjacent businesses that scaled fastest often won on logistics, as our Drizly business model breakdown shows.)
Frequently asked questions
Is the non-alcoholic boom a fad? The evidence points to structural, not seasonal. The decline in drinking is led by the youngest adult cohort and has compounded over two decades, and the substitution segment is projected to grow about 18.5% a year through 2029. That is a demand shift, not a January spike.
Why are so many non-alcoholic brands aimed at the same customer? Partly because the premium, design-led, female-skewing host buyer supports the price points and DTC economics that keep a small beverage brand alive. The clustering is rational, not lazy, which is also why moving away from it carries real risk.
Is “men’s mocktails” a real opportunity or a meme? Both. The occasion gap is real: most male drinking moments have no dedicated NA equivalent. But the most obvious version of that lane (active recovery men) is already held by Athletic Brewing, and men who are not drinking often default to existing products. The opportunity is narrower and more occasion-specific than the broad pitch suggests.
What is the actual transferable lesson for a founder in any category? When every competitor looks identical, they are usually serving one persona. Map the other personas with the same underlying need, pick the one occasion you can own, and build the obviously-theirs version, rather than building a slightly nicer copy of the leader.
The Business Model Analyst Take
The sharpest insight in this category is not “non-alcoholic is hot.” It is that the hottest part of the category, drinks built to replace a specific alcoholic occasion, is being served almost entirely to one customer profile. The reframe that powers the winners, turning not-drinking from a consolation into an upgrade, is buyer-agnostic. De Soi proved it for the host. Athletic proved it for the athlete. The math says there is room for many more, one per defensible occasion.
But we would push back hard on anyone reading this as easy money. The most attractive-looking lanes are either already owned (Athletic in performance) or structurally tougher to monetize than the patio buyer that incumbents deliberately chose. Beverage punishes weak distribution and thin margins faster than almost any consumer category. The credible play is not “build a masculine De Soi.” It is to pick one specific occasion the incumbents ignore, win a channel they do not dominate, and let the branding make the product feel inevitable for that one moment. Same liquid, different person, defensible wedge. That is a brand. A prettier aperitif is not.