
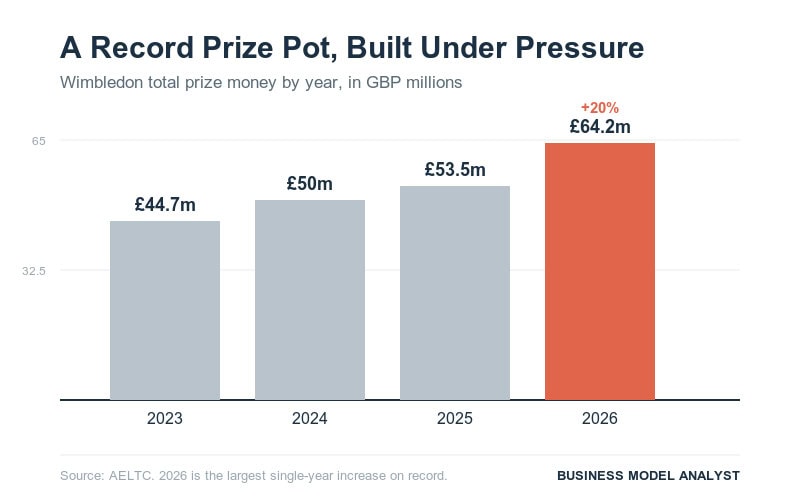
Wimbledon 2026 runs from 29 June to 12 July, and the headline number is a record: a £64.2 million prize pot, up 20% on last year, the single biggest one-year jump in the tournament’s history. The men’s and women’s singles champions each walk away with £3.6 million (about $4.76 million).
That sounds like a club spraying money around. It is not. The more interesting story is that the All England Lawn Tennis and Croquet Club (AELTC) runs one of the most profitable events in global sport precisely by refusing to squeeze it. Wimbledon deliberately leaves money on the table. And in 2026, that 100-year-old strategy is being tested from three directions at once: the players, the planners, and the government.
Here is how the machine actually works, and where the cracks are showing.
Definition Box: What Wimbledon Actually Is, Financially
The All England Lawn Tennis and Croquet Club (AELTC) is a private members’ club with fewer than 500 members that owns and operates the Wimbledon Championships. The tournament generates roughly £400 million-plus in revenue over two weeks, mostly from global media rights. Around 90% of the surplus is passed to the Lawn Tennis Association (LTA), British tennis’s governing body, which uses it to fund the sport from grassroots to elite level. Wimbledon is, in effect, a non-profit-style cash engine for British tennis that happens to be the most prestigious event in the sport.
The Money: A Steady Climb to Half a Billion Dollars
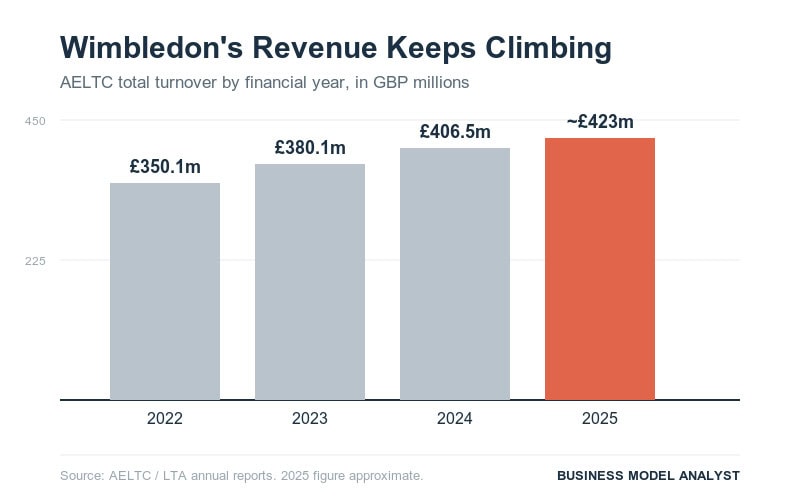
Wimbledon does something almost no other major sporting event does: it publishes a detailed annual report. That transparency lets us track a remarkably consistent growth curve.
| Financial year | AELTC turnover | Operating / pre-tax profit | Surplus to LTA |
|---|---|---|---|
| 2022 | £350.1m | ~£47.1m | ~£40m |
| 2023 | £380.1m | £53.7m | £48.7m |
| 2024 | £406.5m | £54.3m | £49.8m |
| 2025 | ~£423m | not yet detailed | not yet detailed |
In US dollar terms, the 2025 figure is roughly $559 million in revenue from a single two-week tournament. Revenue is up about 162% over the past decade. For context, visitor and related spending tied to the Championships contributes an estimated £434 million to the UK economy each year, including roughly £279 million to the local area around the grounds.
The revenue mix is where Wimbledon’s strategy becomes visible:
| Revenue stream | Approximate share | Notes |
|---|---|---|
| Media rights | Just over 50% | The single largest source. US (Disney / ESPN) and UK (BBC) lead. |
| Ticketing | ~16% to 18% | Kept deliberately cheap by primary-market standards. |
| Sponsorship | Material but undisclosed | Only about 15 partners, far fewer than rival Slams. |
| Concessions and merchandise | ~12% | Mostly merchandise. |
The US broadcast deal alone, signed with Disney for ABC, ESPN and ESPN+, is valued at about $52.5 million per year from 2024. Media is the engine. Everything else is deliberately throttled.
The 2026 Prize Money Record, and the Fight Behind It
The £64.2 million prize fund is a 20% jump from £53.5 million in 2025, an uplift of £10.7 million. That is the largest single-year increase Wimbledon has ever made, and it did not happen by accident. It is a direct response to a year of player pressure.
| 2026 prize money | Amount (GBP) | Change vs 2025 |
|---|---|---|
| Singles champion (each) | £3,600,000 | +20% |
| Singles runner-up | £1,800,000 | +18.4% |
| First-round singles loser | £80,000 | +21.2% |
| Doubles champions (per pair) | £760,000 | +10% |
| Qualifying total pool | £6,200,000 | +25% |
Here is the catch, and it is the number most coverage skips. Even after a record raise, the 2026 prize fund equals roughly 15.2% of the tournament’s prior-year revenue. The top players, organising through informal collective pressure, have been lobbying all four Grand Slams for a share starting at 16% and rising to 22% by 2030. So Wimbledon’s “biggest ever increase” still lands below where players say the floor should be.
The AELTC’s counterargument is straightforward: it cannot hand players 22% of revenue and keep funding facilities, the grass-court season, and the wider British game that depends on its surplus. Players have signalled their displeasure by limiting media appearances during the first week. Expect this standoff to define Grand Slam economics for the rest of the decade.
The Debenture Engine: A £500 Million Financing Trick Most Fans Never See
Most venues raise ticket prices every year and blame inflation. Wimbledon does something cleverer. It sells debentures: five-year securities that give the holder a premium Centre Court or No.1 Court seat for every day of the Championships across that period, plus the legal right to resell those specific tickets.
The most recent Centre Court debentures, covering 2026 to 2030, were priced at about £121,000 each, which works out to roughly £1,860 per ticket. Resale prices for marquee matches such as finals can hit £5,000 to £10,000 per seat. Over the past decade, debenture sales have raised more than £500 million (about $660 million), every penny of which is reinvested into the grounds. It is, in effect, an interest-free way to finance capital projects by selling future access to the wealthy, with no debt on the balance sheet.
There is now a threat to this. The UK government has consulted on capping ticket resale prices to fight touts. Wimbledon debentures are the only tournament tickets that can legally be resold, so a blanket cap near face value would gut the resale upside that makes a £121,000 debenture worth buying in the first place. The AELTC has asked for an exemption, proposing an “authorised resale” category that protects regulated programmes like its own while still targeting exploitative touting elsewhere. If it loses that argument, a core piece of its financing model takes a hit.
The £200 Million Expansion Fight
Wimbledon’s biggest bet is physical. The AELTC wants to nearly triple the size of its grounds by developing the former Wimbledon Park golf course it bought in 2018. The plan: 39 new grass courts and an 8,000-seat show court, bringing qualifying on-site for the first time and lifting daily spectator capacity from about 42,000 to 50,000. Price tag: roughly £200 million (about $265 million).
The economic logic is obvious. More courts and more capacity mean more tickets, more hospitality, more on-site spend, and a stronger pitch to broadcasters and sponsors. It is the most direct lever Wimbledon has to grow beyond its current footprint.
The obstacle is legal. The campaign group Save Wimbledon Park argues the land is held in a statutory trust for public recreation and should not be built on. The fight has run through multiple rounds:
| Stage | Outcome |
|---|---|
| GLA planning permission (2024) | Granted |
| Judicial review (July 2025) | Dismissed; permission upheld |
| High Court trust ruling (March 2026) | Land found not subject to a public recreation trust, favouring the AELTC |
| Court of Appeal | Permission to appeal granted; further proceedings expected through 2026 |
The AELTC has won the major rulings so far and signalled phased construction, but the saga is not over. Until the appeals clear, the single biggest growth project in the tournament’s modern history sits in legal limbo.
How Wimbledon Stacks Up Against the Other Slams
Wimbledon’s prize money is large, but it is not the largest. Its restraint is the point.
| 2025/2026 Grand Slam | Total prize money (approx.) |
|---|---|
| US Open | ~$90 million |
| Wimbledon 2026 | ~$85 million (£64.2m) |
| Australian Open | ~$78 million (AUS$111.5m) |
| French Open | ~$71 million (€61.72m) |
The same restraint shows up in sponsorship. Where the US Open covers nets and courts in logos, Wimbledon runs a “clean court” model with about 15 partners, mostly black low-visibility branding, and no title sponsor at all. Brands like Rolex, American Express, Emirates, Vodafone and Lavazza pay premium rates precisely because exclusivity and scarcity are the product. Most viewers cannot name a single Wimbledon sponsor, and the AELTC considers that a feature, not a bug.
The Business Model Analyst Take
Wimbledon is a case study in the counterintuitive truth that under-monetizing can be the highest-value strategy of all. The AELTC could almost certainly extract another £100 million a year by raising ticket prices to market, loading the courts with sponsors, and maximising every revenue line. It refuses, because the scarcity, the heritage, and the “clean” aesthetic are the moat. Cheap ballot tickets, the queue, the all-white dress code and the quiet branding are not nostalgia. They are brand equity that compounds, and they keep blue-chip partners paying premium rates to be associated with restraint.
The risk is that this model assumes the AELTC stays in control of its own scarcity. In 2026, that assumption is being tested. Players want to convert Wimbledon’s revenue into their own share. Campaigners want to deny it the land it needs to grow. The government may strip the resale upside that funds its capital plans. None of these alone breaks the machine. Together, they mark the first time in a generation that the people Wimbledon negotiates with, the talent, the community, and the state, are all pushing in the same direction at the same time.
For founders and operators, the lesson is sharp: a premium brand built on deliberate scarcity is enormously profitable, but its pricing power is borrowed from stakeholders who can eventually demand it back. Wimbledon spent a century building the most disciplined revenue model in sport. The next few years will reveal how much of that discipline was choice, and how much was leverage it is now starting to lose.
Frequently Asked Questions
How much money does Wimbledon make? The AELTC, which runs Wimbledon, generated roughly £423 million (about $559 million) in revenue in its most recent reported year, with operating profits in the £50 million-plus range. Around 90% of the surplus is passed to the Lawn Tennis Association to fund British tennis.
What is the total prize money for Wimbledon 2026? Wimbledon 2026 offers a record £64.2 million in total prize money, a 20% increase on 2025 and the largest single-year rise in the tournament’s history. The men’s and women’s singles champions each receive £3.6 million.
Where does Wimbledon’s revenue come from? Just over half comes from global media and broadcast rights. Ticketing contributes roughly 16% to 18%, concessions and merchandise about 12%, with the remainder from a small group of about 15 premium sponsors.
What is a Wimbledon debenture? A debenture is a five-year security that grants the holder a premium Centre Court or No.1 Court seat every day of the Championships for that period, plus the legal right to resell those tickets. The most recent Centre Court debentures (2026 to 2030) cost about £121,000 each, and the programme has raised more than £500 million for facilities over the past decade.
Why is Wimbledon trying to expand? The AELTC wants to add 39 courts and an 8,000-seat show court on the former Wimbledon Park golf course, a roughly £200 million project that would nearly triple the grounds and lift daily capacity from about 42,000 to 50,000. Campaigners are challenging it in court over the land’s protected status, with proceedings continuing through 2026.
Why does Wimbledon have so few sponsors? Wimbledon runs a “clean court” model with only about 15 commercial partners and no title sponsor, far fewer than other Grand Slams. The scarcity and low-visibility branding preserve the tournament’s premium image, which lets it charge blue-chip brands higher rates over long-term deals.