
Robotaxis stopped being a demo in 2026. Waymo runs half a million paid rides a week. Tesla dispatches empty Model Ys in four cities. Baidu moved 3.2 million driverless rides in a single quarter. The technology question is close to settled.
The money question is not.
A robotaxi company is a capital-intensive fleet operator wearing a software company’s valuation. It buys expensive hardware, parks it in expensive depots, insures it against a legal regime nobody has finished writing, and sells eight-mile rides for sixteen dollars. Whether that becomes a $415 billion industry or a very well-funded taxi company depends on one number, and almost nobody publishes it.
Below is how the business works, where the money comes from, where it goes, and what has to be true for the bull case to survive contact with a spreadsheet.
Definition Box: Robotaxi Economics at a Glance
| Question | Short answer |
|---|---|
| What is a robotaxi? | An autonomous vehicle (SAE Level 4) that carries paying passengers with no human driver and no safety monitor on board, hailed through an app inside a mapped geographic zone. |
| How do operators make money? | Per-ride fares (base fare plus per-mile plus per-minute), subscriptions, platform commissions, in-car advertising, and licensing the driving stack to third parties. |
| What are the main costs? | Vehicle depreciation, remote assistance staff, depot and cleaning operations, insurance, energy, mapping, and the R&D that never stops. |
| What is the break-even test? | Cost per revenue mile below the fare per mile, at high enough vehicle utilization to pay back the hardware. |
| Who leads today? | Waymo on driverless scale, Baidu Apollo Go on ride volume, Pony.ai on city-level unit economics, Tesla on cost per vehicle. |
| How big could it get? | Goldman Sachs Research forecasts roughly $415 billion globally by 2035, with about $48 billion in the US. |
A Short History: Twenty Years From Desert Race to Downtown Fare
The industry traces to a 2004 US military contest. DARPA offered $1 million to any team that could drive a vehicle 142 miles across the Mojave without a human. Every entrant failed. The best one covered seven miles. A year later, five vehicles finished, and Stanford’s Sebastian Thrun won.
Google hired Thrun and launched a self-driving project in 2009. That project became Waymo in 2016. Uber, General Motors, Ford, Baidu, Amazon and a long list of startups piled in behind it, and by 2018 the sector had absorbed tens of billions of dollars on the promise that driverless fleets were two years away. They were not.
The correction arrived between 2020 and 2024. Uber sold its self-driving unit. Ford and Volkswagen shut Argo AI. GM wound down Cruise in December 2024 after a pedestrian dragging incident in San Francisco, a decision the company said would save it more than $1 billion a year. The survivors were the ones with a parent balance sheet deep enough to fund a decade of losses.
Waymo opened fully driverless public rides in Phoenix in 2020, then San Francisco, then Los Angeles. In May 2024 it was doing 50,000 paid rides a week. Baidu deployed Apollo Go across Wuhan and reached per-vehicle profitability there. Tesla launched robotaxi service in Austin in June 2025 with safety monitors in the passenger seat.
Then the curve bent.
The 2026 Scene: Scale Arrives, Profit Does Not
Waymo crossed 500,000 paid rides a week in Q1 2026 across roughly 11 US metros, a tenfold increase in under two years. In February it raised $16 billion at a $126 billion valuation, the largest round ever for an autonomous vehicle company. Co-CEO Tekedra Mawakana set a target of one million weekly rides by year end.
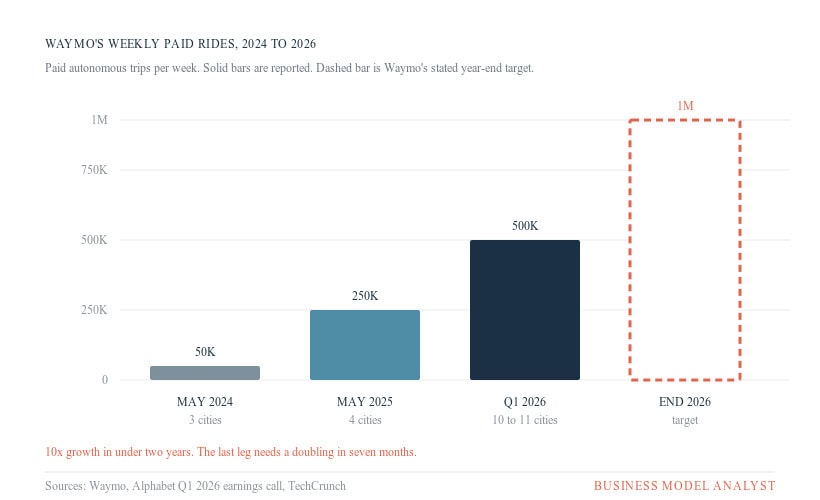
The ride counts are real. The fleet counts are the sobering part.
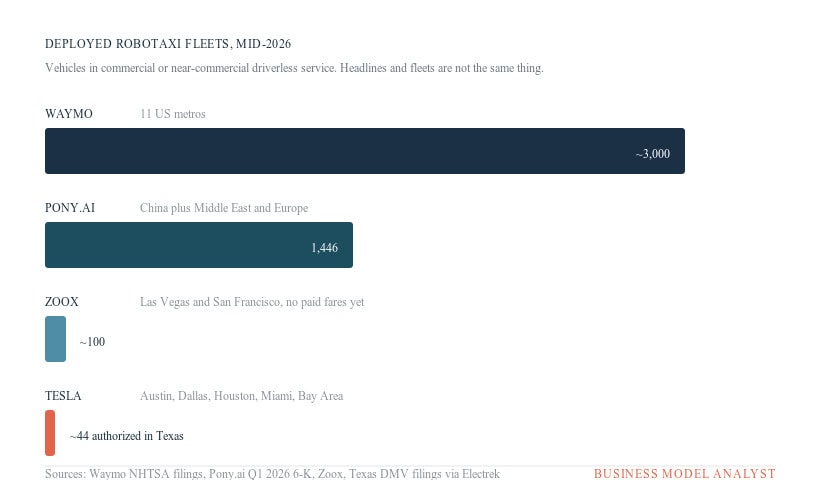
Waymo runs about 3,000 vehicles. Pony.ai reported a fleet of 1,446 as of late March 2026. Zoox, owned by Amazon, has around 100 vehicles on public roads and still cannot charge fares while it waits for a federal exemption covering a vehicle with no steering wheel. Tesla, whose robotaxi ambitions carry a large share of its equity story, had 42 vehicles authorized in Texas filings and roughly 20 running unsupervised as of late May.
For scale: Uber and Lyft drivers complete around 675,000 trips a day in New York City alone. The entire global robotaxi industry, after twenty years and something north of $100 billion in cumulative investment, moves fewer paid rides in a week than one American city hails in twenty-four hours.
Nobody is profitable at the corporate level. Alphabet’s Other Bets segment, which houses Waymo, reported $411 million of revenue against a $2.1 billion operating loss in Q1 2026 alone.
How Robotaxi Companies Make Money
Five revenue streams exist. Only the first one matters today.
| Revenue stream | How it works | Who uses it |
|---|---|---|
| Per-ride fares | Base fare plus per-mile plus per-minute. Waymo charges roughly $9.52 plus $1.66 per mile in San Francisco, and prices about 15% under Uber and Lyft on overlapping routes. Average revenue lands near $15 to $17 per ride. | Waymo, Tesla, Baidu, Pony.ai |
| Subscriptions | Recurring fee for discounts, priority pickup or free waiting. Waymo launched a $29.99 per month Premier tier in mid-2026. Uber One reached 50 million members and drives half of Uber’s gross bookings, which is the playbook being copied. | Waymo, and eventually anyone with density |
| Platform commission | Take a cut for supplying demand rather than supplying cars. Uber lists Waymo, WeRide, Motional, Avride and Zoox on its app in different cities and books the customer relationship without buying a single vehicle. | Uber, Lyft |
| Technology licensing | Sell the autonomy stack to a fleet owner or automaker instead of operating vehicles. Baidu has hinted its long-term role in the value chain is still open. | Baidu, WeRide, Wayve, Nuro |
| In-car media and data | A captive passenger with no driver to talk to, staring at a screen for eight miles. Barely monetized in 2026, and the most obvious margin lever nobody has pulled hard yet. | Nobody, at scale |
Fares dominate. Everything else is a rounding error or a slide in a deck.
The Cost Stack: Where a Robotaxi Dollar Goes
Removing the driver removes 50% to 60% of the cost of a human ride. It then adds back a set of costs that human ride-hailing never had.
| Cost line | What drives it | Direction |
|---|---|---|
| Vehicle depreciation | A Waymo Jaguar I-PACE with 5th-gen hardware cost an estimated $150,000 to $180,000. The 6th-gen system on the Geely Zeekr platform is estimated at $80,000 to $100,000. Goldman models depreciation falling from about $0.35 per mile in 2025 to $0.14 by 2035. | Falling fast |
| Remote assistance | Humans who unstick confused vehicles. Goldman estimates one operator covers about three cars today, rising to ten by 2030 and 35 by 2040. Pony.ai claims its Gen-7 system already reached 1 to 20. | Falling, and the biggest swing factor |
| Depot operations | Charging, cleaning, tire changes, sensor calibration, vandalism, vomit. Real estate in dense cities is not cheap. | Sticky |
| Insurance and liability | The operator carries the liability a human driver used to carry. Premiums fall as safety records build, but a single catastrophic event resets the whole line. | Falling, with fat tails |
| Energy | Electricity instead of gasoline, the cheapest line in the stack. | Negligible |
| R&D and mapping | Never ends. Every new city means new HD maps for lidar-based operators. Waymo needs multiple quarters per city launch. | Structural |
Put those together and you get the only chart that matters.
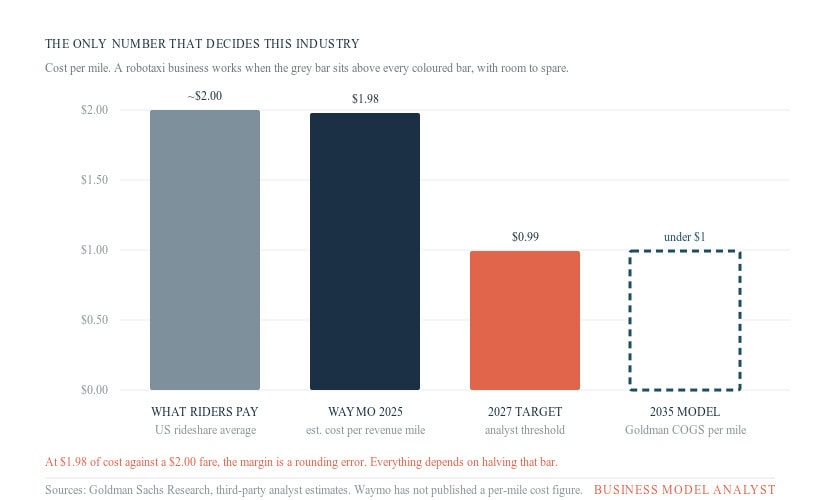
Third-party analysts put Waymo’s 2025 cost per revenue mile near $1.98. The average US rideshare fare is a little over $2.00 per mile. The gap between those two numbers is where an entire industry has to fit.
The $0.99 per mile figure is the threshold analysts describe as necessary to justify Waymo’s valuation, targeted for 2027. Goldman models a vertically integrated operator getting cost of goods sold below $1.00 per mile in the US by 2035.
Information Gain: The Unit Economics Nobody Publishes
Waymo has never released a per-vehicle P&L. You can build a rough one from figures the company and Alphabet have disclosed.
Take 500,000 paid rides per week, roughly 4 million rider-only miles per week, and roughly 3,000 vehicles.
| Derived metric | Calculation | Result |
|---|---|---|
| Rides per vehicle per day | 500,000 ÷ 3,000 ÷ 7 | ~24 |
| Miles per vehicle per day | 4,000,000 ÷ 3,000 ÷ 7 | ~190 |
| Average trip length | 4,000,000 ÷ 500,000 | 8.0 miles |
| Revenue per vehicle per year | 167 rides/week × $16 × 52 | ~$139,000 |
| Cost per vehicle per year at $1.98/mile | 1,333 miles/week × $1.98 × 52 | ~$137,000 |
| Implied gross contribution | Revenue minus cost | Close to zero |
Two things fall out of that table.
The first: 24 rides per vehicle per day already beats the roughly 18 rides a typical Uber driver completes. Utilization is not the problem. Waymo has solved the demand side.
The second: at $1.98 of cost against a $16 fare over 8 miles, the vehicle earns back nothing. Now run the same vehicle at $0.99 per mile. Annual cost drops to about $69,000, contribution jumps to roughly $70,000 per vehicle per year, and a $90,000 Zeekr-based robotaxi pays for itself in about sixteen months. That single halving turns a money furnace into one of the best returns on invested capital in transportation.
Every bull case in this sector is a bet on that one line falling by half. Everything else is commentary.
A third data point worth holding against the valuation: Waymo’s annualized revenue sat near $355 million in February 2026, when it raised at $126 billion. That is roughly 355 times revenue. Alphabet’s whole Other Bets segment, Waymo included, brought in $411 million in Q1 and lost $2.1 billion.
Four Business Models, One Industry
The players are not running the same company.
| Model | Who | Logic | Weakness |
|---|---|---|---|
| Vertically integrated operator | Waymo, Zoox, Tesla | Own the stack, the vehicle, the fleet and the customer. Capture the full margin, which Goldman models at 30% to 50% gross by 2035. | Brutal capex. Every new city is a construction project. |
| Asset-light aggregator | Uber, Lyft | Supply demand, not cars. Uber has committed over $10 billion across 20-plus AV partnerships and wants 100,000 autonomous vehicles on its platform by 2027, almost none of them its own. | You are a demand utility. If Waymo’s app wins the customer, your take rate goes to zero. |
| Technology licensor | Baidu, WeRide, Wayve, Nuro | Sell the driver, not the ride. Software margins, no depots. | You capture a slice of a slice, and your customers can build in-house. |
| Cost-first mass manufacturer | Tesla | Skip lidar and HD maps, use cameras and a Model Y that costs a fraction of a Waymo, then scale on price. Tesla prices around $0.81 per mile against Waymo’s $1.36 to $1.43. | Camera-only perception is under federal scrutiny, and 44 authorized vehicles is not a fleet. |
Uber’s position is the most interesting and the most fragile. The company is lobbying in Washington DC for rules requiring robotaxis to operate on networks that also carry human drivers, which would block a first-party Waymo monopoly. That puts Uber in a public regulatory fight with its own business partner. When your strategy requires legislation to keep your supplier from disintermediating you, the moat is thinner than the deck suggests.
How Big Can This Get?
Goldman Sachs Research forecasts the global robotaxi market at roughly $415 billion by 2035, with the US at $19 billion in 2030 and $48 billion in 2035. The global commercial fleet grows from about 7,000 vehicles in 2024 to around 1 million in 2030 and 6 million in 2035. Cumulative gross profit from robotaxis over the next decade: about $440 billion.
Those are enormous numbers. They also contain an assumption that deserves daylight.
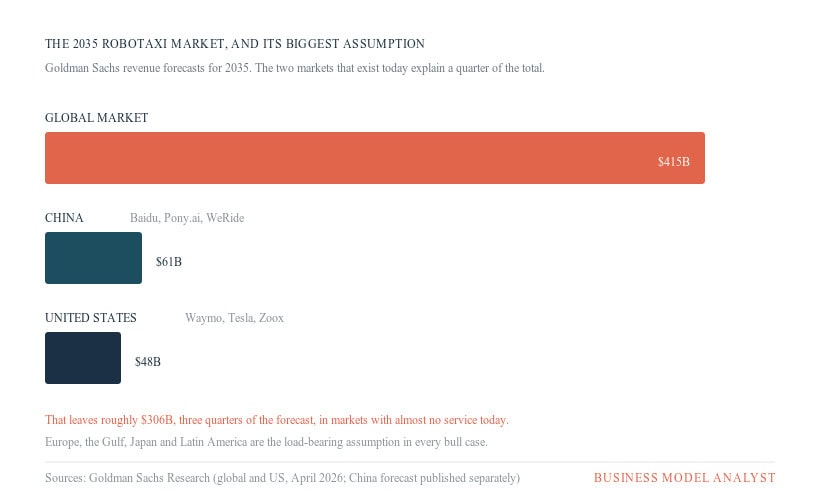
Goldman puts China at roughly $61 billion by 2035 and the US at $48 billion. Global lands at $415 billion. Subtract, and roughly $306 billion of the forecast, close to three quarters of it, comes from markets that today have almost no commercial driverless service at all. Europe, the Gulf states, Japan and Latin America carry the load.
Robotaxis exist in Europe as a pilot in Zagreb charging $2.33 a ride. Waymo has not yet completed a paid driverless trip in London. The forecast may prove right. It is not evidence.
The China market has a structural tailwind the West lacks: about 4 million taxi and ride-hailing drivers there will retire by 2035, and cities including Shenzhen and Hangzhou have already raised the maximum driver age to 65 to cope. Robotaxis fill a hole that demographics dug. In the US, they compete with a labor supply that is not going anywhere and that votes.
The Challenges Nobody Solved Yet
Safety, and its regulatory shadow. Waymo claims a 13x reduction in serious-injury crashes versus human drivers across 170 million autonomous miles. It also issued six recalls. In 2026 alone it recalled roughly 3,800 vehicles after one drove into a flooded road in San Antonio and was swept into a creek, then recalled about 3,900 more after 13 incidents of robotaxis entering freeway construction zones. It suspended all freeway driving on May 19 and was still running surface streets only weeks later. NHTSA has an open investigation after a Waymo struck a child near a Santa Monica elementary school in January, and the NTSB is investigating school bus passing violations.
Freeway miles are the high-margin miles. Losing them for a quarter is not a rounding error.
Capital intensity. Waymo needed a $16 billion round to fund a fleet expansion into 20-plus cities. Cruise burned more than $1 billion a year before GM shut it. This is not a business two founders bootstrap.
Geographic density. Robotaxi economics work in dense, warm, gridded, well-mapped cities. Phoenix, Austin, Miami. They work less well in Boston in February. Every operator has quietly picked the easy geographies first, which means the marginal city is always harder than the last one.
Liability. When a Waymo hits someone, Waymo is the defendant. There is no independent contractor to absorb the risk, which is the entire trick Uber used to build its cost structure. The Uber business model offloaded vehicles, insurance and liability onto drivers. Robotaxi operators take all three back onto the balance sheet.
Labor politics. The Teamsters and the Service Employees International Union are already at the table in Washington. Displacing several hundred thousand American driving jobs is a political event, not just a technical one.
FAQ
Are robotaxis profitable in 2026? Not at the company level. Baidu reached per-vehicle profitability in Wuhan, and Pony.ai hit city-wide unit economics break-even in Guangzhou in November 2025 and Shenzhen in February 2026. Those are single-city milestones, not corporate profits. Alphabet’s Other Bets segment, which includes Waymo, lost $2.1 billion in Q1 2026.
How much does a robotaxi cost to build? Waymo’s 5th-generation Jaguar I-PACE configuration is estimated at $150,000 to $180,000 per vehicle. The 6th-generation system on the Zeekr platform is estimated at $80,000 to $100,000. Tesla uses a production Model Y, which is why its cost per mile undercuts everyone. Goldman expects vehicle depreciation per mile to fall by roughly 60% between 2025 and 2035.
Do robotaxis still need humans? Yes. Remote assistance operators handle situations the vehicle cannot resolve, at roughly one operator per three cars today. Pony.ai claims a 1 to 20 ratio with its Gen-7 hardware. Getting that ratio up is the single largest operating-cost lever in the industry.
Will robotaxis kill Uber and Lyft? Only if riders switch to first-party apps. Uber’s counter is to become the demand layer for every autonomous fleet, with over $10 billion committed across 20-plus partnerships and a target of 100,000 AVs on its platform by 2027. Lyft is pushing AVs into its FlexDrive fleet-ownership arm. Both are betting that supplying demand is more defensible than supplying cars.
Why does Tesla’s approach cost less? Cameras instead of lidar, no HD-mapping requirement, and a mass-produced vehicle rather than a bespoke one. That is a genuine structural cost advantage, and it is why Tesla can price near $0.81 per mile. The open question is whether camera-only perception clears the safety bar in rain, glare and construction zones. Federal regulators flagged the sensor architecture as a potential deficiency in March 2026. See the Tesla business modelfor how autonomy fits the wider company, and the Tesla SWOT analysis for the risk side.
Which market matters most? China moves more robotaxi rides than the US. Baidu’s Apollo Go alone delivered 3.2 million fully driverless rides in Q1 2026, up more than 120% year over year. Average fares are far lower, around $2.80 in Goldman’s break-even model, so revenue per vehicle is a fraction of Waymo’s. Volume leadership and revenue leadership sit in different countries.
The Business Model Analyst Take
The robotaxi debate is stuck in the wrong argument. People fight about lidar versus cameras, Waymo versus Tesla, whether the cars are safe. Those questions are close to answered. The cars work. The cars are, on the available evidence, safer than the median human driver.
The unresolved question is whether a company can own thousands of $90,000 computers on wheels, staff the depots that clean them, employ the humans who rescue them, insure the accidents they cause, and still make money selling eight-mile rides at fifteen bucks. That is not a technology question. It is a fleet-operations question, and fleet operations is a low-margin business with a long history of eating optimistic capital.
Waymo has done the hard part. Twenty-four rides per vehicle per day beats Uber’s human drivers. Demand is not the constraint. Cost is. At roughly $1.98 per revenue mile against a $2.00 fare, the business is running to stand still, and the entire $126 billion valuation rests on cutting that in half within two years.
It might happen. Cheaper vehicles are shipping, remote-assist ratios are improving, and insurance falls as the safety record lengthens. But notice what the sector is asking investors to believe: that costs halve, that the remote operator ratio improves sixfold, that three quarters of the 2035 market appears in countries where the service does not yet exist, and that no single catastrophic incident resets public tolerance the way one did for Cruise.
Amazon spent two decades proving that a low-margin operational business can be a spectacular one if you own enough of the stack and wait long enough. The Amazon business model is the closest available template for what Waymo is attempting. Note how long it took, and note that Amazon had a cash-generating retail engine funding the wait.
Waymo has Alphabet. Zoox has Amazon. Tesla has its car business. Baidu has search. Pony.ai and WeRide have neither, which is why they are the ones talking loudest about city-level break-even.
Watch three numbers and ignore the rest. Cost per revenue mile. Remote operators per vehicle. Paid rides per vehicle per day. When the first falls under a dollar and the second passes one to fifteen, this becomes one of the great businesses of the decade. Until then it is the most expensive taxi company ever built.
Sources: Alphabet Q1 2026 earnings, Goldman Sachs Research, Pony.ai SEC filings, Waymo, NHTSA recall filings, Baidu Q1 2026 results, TechCrunch, CNBC.