Most SWOT analyses sort facts into four boxes and stop. Texas Roadhouse breaks that format, because its four boxes are wired to each other in series. The beef shortage sitting in the threat column is the same force filling the dining rooms in the strength column, and the company pays for both out of the weakness column. Read the quadrants as a circuit and the useful question changes from what the company has to what happens when the circuit opens.
What This Analysis Covers
SWOT analysis is a strategic framework that sorts a company’s position into internal strengths and weaknesses and external opportunities and threats. If you want the mechanics first, start with our guide to what a SWOT analysis is and the step-by-step version in how to do a SWOT analysis.
The finding here: Texas Roadhouse posted the best sales quarter in its 33-year history and slightly lower earnings per share in the same 13 weeks. That is not a contradiction. It is the design working as intended, and the quadrants only make sense once you trace the loop between them.
Texas Roadhouse at a Glance
| Metric | Latest reported | Period |
|---|---|---|
| Total revenue | $1.68 billion, up 11.1% | Q2 2026 (13 weeks ended June 30, 2026) |
| Full-year revenue | $5.88 billion, up 9.4% | FY2025 (52 weeks ended December 30, 2025) |
| Comparable restaurant sales | Up 6.2%, on 3.0% traffic and 3.2% check | Q2 2026 |
| Average weekly sales per restaurant | $177,252, a company record | Q2 2026 |
| Restaurant margin | 16.4% of sales, down 66 basis points | Q2 2026 |
| Diluted earnings per share | $1.85, down 0.7% | Q2 2026 |
| Commodity inflation | 7.0% in the quarter, guided to about 5% for the year | Q2 2026 |
| Restaurants | 832 system-wide (732 company, 100 franchise) | June 30, 2026 |
| Concepts | Texas Roadhouse, Bubba’s 33, Jaggers | |
| Employees | Over 100,000 | FY2025 |
| Founded / IPO | 1993, Clarksville, Indiana / NASDAQ 2004 |
Kent Taylor opened the first restaurant in 1993 with $300,000 raised from three Kentucky doctors, took the company public in 2004, and died in 2021. Jerry Morgan, the chain’s first-ever managing partner, runs it now. In April 2025, Technomic’s Top 500 data showed Texas Roadhouse passing Olive Garden to become the largest casual dining chain in the United States by systemwide sales, ending a run Olive Garden had held since 2018.
The Number That Refuses to Behave
Start with the quarter, because everything else in this analysis follows from it.
In the 13 weeks ended June 30, 2026, Texas Roadhouse grew restaurant sales by $168.9 million. Restaurant margin dollars rose $17.8 million. Income from operations fell $3.6 million. Diluted earnings per share came in a penny below the prior year.
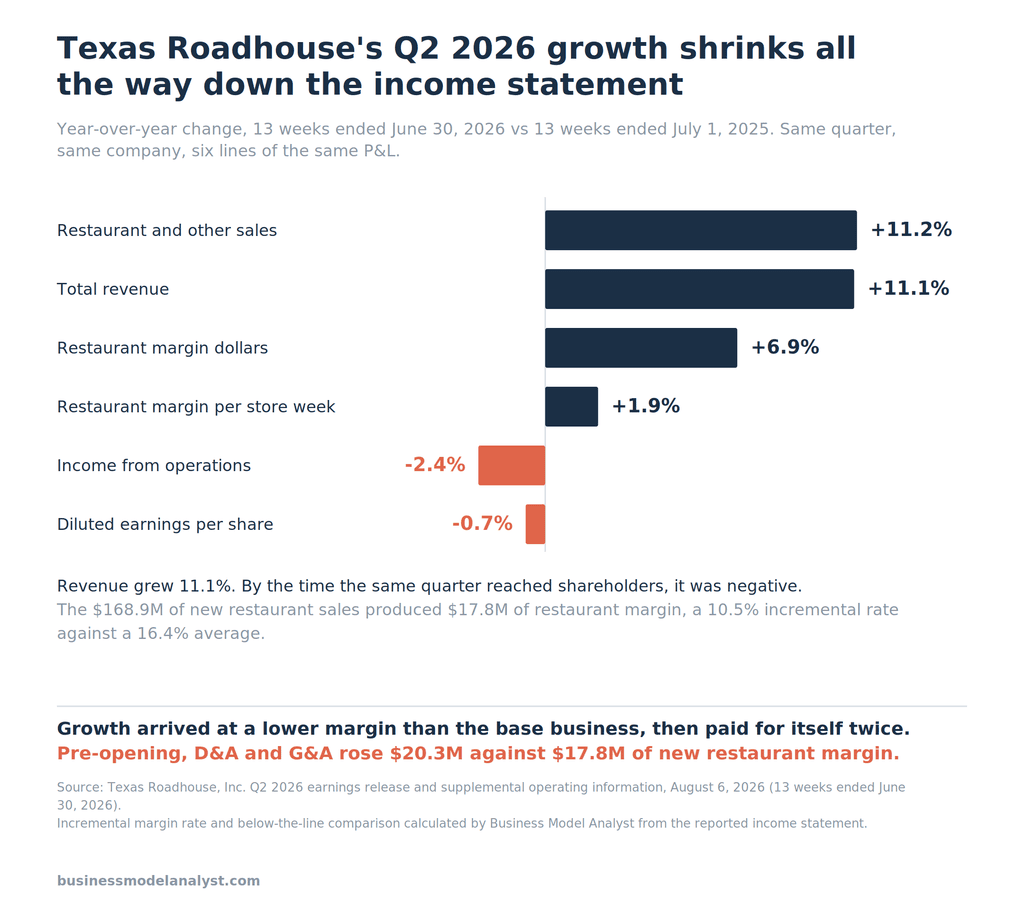
The incremental math is where this gets interesting. Those $168.9 million of new sales carried $17.8 million of restaurant margin, an incremental rate of 10.5% against a company average of 16.4%. Every new dollar of sales showed up nearly six points less profitable than the existing dollars.
The second bill lands below the restaurant line. Pre-opening expense rose $3.0 million, depreciation and amortization rose $7.6 million, and general and administrative expense rose $9.6 million. Together, the costs of running a bigger company grew $20.3 million against $17.8 million of new restaurant margin. Add the $1.0 million decline in royalties and the operating line reconciles to the dollar.
That is the whole company in one paragraph. Growth arrived at a discount, and the cost of producing it exceeded what it produced.
Strengths
Volume per building that nobody in casual dining matches. Average weekly sales hit $177,252 in Q2 2026, the first time above $175,000 in the company’s history, and comparable Texas Roadhouse restaurants ran $183,982 a week. Annualized, a mature Texas Roadhouse turns roughly $9.5 million through one dining room. For scale, McDonald’s averages about $4 million per US restaurant, and Chick-fil-A, the productivity champion of quick service, runs around $9 million at its stand-alone units. Texas Roadhouse does it with a full-service kitchen, a bar, and hand-cut steaks.
Traffic, not price, drives the comps. Fiscal 2025 comparable sales rose 4.9%, of which 2.8 points came from guest counts. Q2 2026 comps rose 6.2%, split 3.0 points traffic and 3.2 points check. Most casual dining chains have spent three years reporting positive comps built almost entirely on menu pricing while guest counts fell. Texas Roadhouse is selling more meals to more people. It has now recorded 60 consecutive quarters of comparable sales growth excluding 2020.
The managing partner contract. Each restaurant’s general manager puts up a refundable $25,000 deposit, signs a five-year employment agreement, and takes 10% of that restaurant’s profit on top of base pay. Morgan held the first one. Company president Gina Tobin started the same way. The arrangement produces operators who behave like owners of a single asset rather than employees of a chain, and it explains a chunk of why the volume advantage persists at 662 company Texas Roadhouse locations rather than eroding with scale.
Pricing restraint as a competitive weapon. The company took a 1.9% menu increase in early April 2026 against 7.0% commodity inflation. Management reviews pricing twice a year with input from restaurant operators. When retail beef sits near record levels and grocery steak stops looking cheap, a steakhouse that has not chased its costs into the menu becomes the best value in the category by default.
Cash generation and a clean balance sheet. Fiscal 2025 produced $730.1 million of operating cash flow. The company carried no long-term debt at year-end and funded $388.0 million of capital expenditure, $107.5 million of franchise acquisitions, $180.3 million of dividends, and $150.4 million of buybacks out of its own operations.
Weaknesses
The cost structure has no shock absorber. Food and beverage ran 35.4% of sales in Q2 2026, up 136 basis points year over year. Labor ran 32.5%. Together they consume more than two thirds of every dollar before rent, utilities, or a single corporate salary. In Q4 2025, commodity inflation hit 9.5%, restaurant margin fell 309 basis points to 13.9%, and diluted earnings per share dropped 26.1% on revenue that still grew 3.1%.

The operators absorb part of the squeeze. In Q2 2026, sales per store week rose 5.9%. Restaurant margin per store week rose 1.9%. The pool that managing partners are paid 10% of grew at roughly a third the rate of the restaurant’s sales. In Q4 2025 it was worse: restaurant margin per store week fell 15.1%, from $26,159 to $22,204, which cut a managing partner’s variable pay by something on the order of $5,100 in a single quarter. The ownership mentality that makes the model work is partly financed by the people who hold it.
The fastest-growing channel is the least profitable one. To-go accounted for $25,369 of the $177,252 in weekly sales, or 14.3%. But of the $9,902 increase in weekly sales, $3,126 came from to-go. That is 31.6% of the growth from 14.3% of the volume, 2.2 times its own weight.

Dining room sales per restaurant grew 4.7%. To-go grew 14.1%. Management named the growing to-go mix as the reason overall menu mix ran about 40 basis points negative in the quarter, even though dining-room mix turned slightly positive. A curbside order skips the appetizer, the second round, and most of the beverage margin that pays for the room.
Bubba’s 33 is not carrying its weight. The second concept posted comparable sales of 1.3% against the flagship’s 6.5%, decelerating from 4.3% a year earlier. Its quarterly average unit volume of $1.66 million is 70% of the flagship’s $2.38 million.

The company opened three Bubba’s and five Texas Roadhouses in the quarter, and Bubba’s store weeks grew 11.1% against the flagship’s 4.2%. New Bubba’s units open at $159,187 a week against $128,185 for the mature ones, which points the problem at the older cohort rather than the format.
No franchise buffer. Royalties and franchise fees came to $7.1 million in Q2 2026, down 12.6% year over year, against $1.67 billion of restaurant sales. Domestic Texas Roadhouse franchise units fell from 56 at the end of 2024 to 36 at the end of 2025 to 31 in June 2026, or 4.5% of the domestic base. When beef spikes, no franchisee balance sheet absorbs any of it. The company eats the entire move, which is the mirror image of the arrangement analyzed in our McDonald’s business model breakdown, where roughly four fifths of system sales sit on someone else’s books.
Opportunities
Unit growth with a real pipeline. Management guided to about 35 company openings in 2026 across the three brands and described a development pipeline running into 2029. Store week growth is guided at 5% to 6%.
Buying back its own restaurants. Texas Roadhouse is de-franchising while most of the industry refranchises. It acquired 20 franchise locations in 2025 for $107.5 million and five California restaurants on the first day of fiscal 2026 for roughly $72 million. Each acquired restaurant converts a royalty stream of a few percent into full ownership of a $9.5 million revenue line. The price moved sharply, though: about $5.4 million per restaurant in 2025 against about $14.4 million in 2026. The 2026 set was California, where both volume and real estate run above the system, and $32.8 million of the $71.8 million spent in the first half landed in goodwill.
International, at somebody else’s risk. Sixty-two international Texas Roadhouse locations operate under franchise across ten foreign countries and a US territory. It is the one place the company lets a partner fund the building.
Jaggers. The fast-casual concept sits at 11 company units and seven franchised, with weekly sales near $73,000. Small enough to be an option rather than a commitment.
Beverage attachment. The 2026 plan added mocktails, dirty sodas, and a $5 all-day beverage special. Beverage is the highest-margin line on the check and the one the to-go shift is eroding.
Threats
Beef, which is the whole story. The US cattle herd sits near its smallest level since 1951, and the breeding herd at counts last seen in the early 1960s. The USDA projects another 2% decline in beef production for 2026 and does not expect a meaningful rebuild before 2028. Weekly cattle slaughter in mid-August 2026 ran 517,000 head against 535,913 a year earlier. Steak anchors the menu and, by common industry estimates, accounts for close to half of menu sales, so Texas Roadhouse owns this exposure directly.
Wage inflation in a labor-heavy format. Wage and other labor inflation ran 3.9% in Q2 2026 against guidance of 3% to 4%. A full-service steakhouse employs far more people per dollar of sales than a drive-thru, which is why more than 100,000 people work there against 832 restaurants.
Capital returns now exceed cash generation. In fiscal 2025, capital expenditure, franchise acquisitions, dividends, and buybacks totaled $826.2 million against $730.1 million of operating cash flow. Cash fell from $245.2 million to $134.7 million, and by June 30, 2026, the company had drawn $50 million on its revolving credit facility, having carried no long-term debt at year-end. Guided 2026 capital expenditure is about $400 million on top of the franchise purchases.
Competitors who noticed. LongHorn Steakhouse passed Outback in Technomic’s rankings and keeps growing, and it sits inside Darden, which can subsidize a concept through a bad cycle. Chili’s rebuilt its traffic on value marketing. The comparison worth watching is the one we make in our Chick-fil-A SWOT analysis: an operator whose customer satisfaction lets it price without losing guests. Texas Roadhouse has the traffic but has chosen not to test whether it has the pricing power.
Holiday calendar mechanics. Management flagged roughly 75 basis points of drag on fourth-quarter comparable sales from Halloween and Christmas falling on different days.
The Circuit: How the Four Quadrants Feed Each Other
Set the boxes aside and follow the current.
Stage one. Cattle supply contracts to a 75-year low. Retail beef climbs. Steak at the grocery store stops being an ordinary purchase for a middle-income household.
Stage two. Those households go to Texas Roadhouse instead. This is not inference. Asked on the August 2026 earnings call what happens to traffic if retail beef retraces, investor relations vice president Michael Bailen said the company benefits from traffic and steak-category sales when retail beef prices are high, and that high beef prices introduce new guests to the brand. The threat in the fourth quadrant is a customer acquisition channel.
Stage three. Those new guests order steak, which the company buys at 7% inflation, and the company refuses to price for it. Restaurant margin falls 66 basis points. The refusal costs less than it looks. Restaurant operating costs went from 82.9% to 83.6% of sales. Holding cost dollars constant, an additional 0.84 points of menu price would have held the margin rate flat, taking the April increase from 1.9% to 2.74%. That is roughly $14 million of quarterly sales, about $57 million annualized, and it assumes no guest walks away.
Texas Roadhouse could close its entire margin gap with less than a point of price. It chose not to. The decision buys 3.0% traffic growth, record average weekly sales, and the value reputation that makes stage two work in the first place.
Stage four. The traffic requires more restaurants, and more restaurants cost $20.3 million a quarter in pre-opening, depreciation, and corporate overhead, which exceeds what the restaurants earned. Earnings per share goes flat.
Run the loop and every quadrant is a consequence of the one before it. The strength is manufactured by the threat. The weakness is the price of converting one into the other. The opportunities are what the company does with what is left, and there is not much left.
What Opens the Circuit
Beef is already coming off the peak. Choice boxed beef was quoted at $363.03 per hundredweight in USDA data for August 10, 2026, against roughly $412 in late August 2025. Texas Roadhouse cut its 2026 commodity inflation guidance from about 7% to about 5%, with the third quarter guided at 2% to 3%. The company had 80% of its third-quarter basket locked and 40% of the fourth.
The bull case reads this as margin recovery arriving on schedule. Take 2026 commodity inflation to 5%, hold the 1.9% price, and restaurant margin repairs itself without management doing anything.
The bear case reads the same sentence and asks what happens at stage two. If grocery steak becomes affordable again, the household that discovered Texas Roadhouse in 2025 has a cheaper option at home. Bailen was asked this directly and would not forecast it, saying only that the chain has held traffic through multiple cycles and that he believes the new guests will return in a lower-inflation environment.
Both cases are defensible. What is not defensible is scoring the threat quadrant without noticing that removing the threat also removes something from the strength quadrant. This is the part standard SWOT treatments of Texas Roadhouse get wrong. They list beef inflation as a risk, list traffic growth as an asset, and never connect them.
Frequently Asked Questions
Is Texas Roadhouse profitable in 2026? Yes. The company earned $245.4 million in the first half of fiscal 2026 on $3.31 billion of revenue, with diluted earnings per share of $3.72, up 4.2%. The second quarter alone earned $121.9 million. Profit is growing more slowly than sales, not disappearing.
Why did earnings per share fall while revenue rose 11%? Three things happened at once. Commodity inflation of 7.0% pushed food and beverage costs to 35.4% of sales. New sales arrived at a 10.5% incremental restaurant margin against a 16.4% average. And the fixed costs of a growing company, mainly depreciation, general and administrative expense, and pre-opening, rose $20.3 million against $17.8 million of new restaurant margin.
Does Texas Roadhouse franchise? Barely, and less every year. Only 31 domestic Texas Roadhouse restaurants were franchised as of June 30, 2026, down from 56 at the end of 2024. Royalties and franchise fees came to $7.1 million in the second quarter against $1.67 billion of company restaurant sales. Most international units are franchised. The domestic route into the business is the managing partner contract, not a franchise agreement.
What is the biggest risk to Texas Roadhouse? Beef supply, on the numbers. The US cattle herd is the smallest since 1951 and the USDA does not expect a rebuild before 2028. With steak anchoring the menu and no franchise base to spread the cost, Texas Roadhouse absorbs the entire move on its own income statement.
How does Texas Roadhouse compare to McDonald’s or Chick-fil-A? Different businesses that happen to sell food. McDonald’s collects royalties and rent from franchisees, as our McDonald’s SWOT analysis sets out. Chick-fil-A owns its restaurants and licenses operators under tight terms, covered in our Chick-fil-A business model breakdown. Texas Roadhouse owns nearly everything, which is why its revenue line and its systemwide sales are almost the same number, and why a commodity spike lands with full force.
Why does Texas Roadhouse keep prices low when its costs are rising? Management calls it preserving the value proposition, and it reviews pricing twice a year with operator input. The arithmetic suggests the restraint is cheaper than it looks. Roughly 0.84 additional points of menu price would have held second-quarter margin flat. The company spent that to protect traffic growth of 3.0% and the reputation that draws guests away from grocery steak.
How many Texas Roadhouse locations are there? 832 system-wide as of June 30, 2026, across 49 states, one US territory, and ten foreign countries. That splits into 732 company restaurants, of which 662 are Texas Roadhouse, 59 Bubba’s 33, and 11 Jaggers, and 100 franchise restaurants.
The Business Model Analyst Take
Texas Roadhouse is the rare company whose SWOT you can draw as a wiring diagram. Cattle scarcity pushes guests through the door, the guests eat steak the company will not fully price, and the resulting volume needs buildings that cost more to open than they immediately earn. Four quadrants, one current.
That makes the standard bull and bear arguments both incomplete. Bulls point to 60 straight quarters of comparable sales growth and $177,252 a week per restaurant and treat the margin compression as weather. Bears point to a 309 basis point margin collapse in Q4 2025 and treat the traffic as luck. Each is holding one end of the same wire.
The question that decides the next two years is narrow. When beef normalizes, does the traffic hold? Texas Roadhouse believes it does, and it has a real argument: 60 quarters of growth spanning several cattle cycles, an operator contract that produces consistent execution, and a value reputation built over 33 years rather than during one spike. If that is right, margin recovery is nearly free, because the company gets its cost line back without giving anything up.
If it is wrong, the company discovers that a meaningful share of recent traffic was a substitution effect it mistook for brand strength, and it discovers this while carrying $400 million of annual capital expenditure, a growing depreciation load, and shareholder returns that already ran $96 million ahead of operating cash flow in 2025.
Watch one number. The company will not tell you the answer, but its own pricing decision will. If Texas Roadhouse still refuses to price when commodity inflation drops to 2% or 3%, management is telling you it believes the traffic is bought, not earned, and it intends to keep paying. If it takes price into a falling cost environment, it has decided the guests are staying.