
Tesla has scrubbed the Solar Roof from its website. The product died because Tesla changed which end of the solar business it wants to own.
Tesla stopped selling the Solar Roof this week, redirecting the product page and its support pages to the generic solar landing page. The obvious explanation is that the product failed: it cost too much, installed too slowly, and ran hot enough to warp its own tiles. All true. The explanation that matters more is that Tesla now wants to manufacture 100 gigawatts of solar a year, and a bespoke roof installed by hand at 30 homes a week has no place inside a company organized around that number.
In October 2016, Elon Musk stood on the Universal Studios backlot set of Desperate Housewives and showed off four houses roofed in solar tiles that looked like slate and terracotta. The tiles were not working products. A Delaware court would later hear plaintiffs argue that the demo existed to sell shareholders on a $2.6 billion acquisition. Ten years later, Tesla is spending a comparable sum on Chinese cell-manufacturing tools bound for Texas, and the roof is gone.
What Happened
Tesla removed public-facing mentions of the Solar Roof from its website and pointed the URL at its conventional solar page. Electrek’s Fred Lambert reported the disappearance first, on August 20, and TechCrunch confirmed the redirects the following day. Two installers told TechCrunch they can still fulfill orders depending on project timing, which suggests Tesla is clearing warehouse inventory rather than honoring a product roadmap.
The company issued no announcement. Solar has always been the quietest line in the Tesla business model. Tesla has run this play before with the Solar Roof’s own numbers: in Q1 2024 it deleted the solar deployment line item from its quarterly report and folded the disclosure into a sentence about Megapack growth being partly offset by lower solar deployments.
What the roof achieved, before Tesla stopped counting:
| Milestone | Figure |
|---|---|
| Musk’s stated install target (2019) | 1,000 roofs per week |
| Actual rate, 2022 | 20 to 40 roofs per week |
| Peak quarterly deployment (Q2 2022) | ~2.5 MW, roughly 23 roofs per week |
| US systems installed through early 2023 | ~3,000 (Wood Mackenzie estimate) |
| Reported homeowner quotes | Up to $200,000 |
Tesla disputed the Wood Mackenzie count and never published its own. Take the estimate at face value and the entire American Solar Roof fleet adds up to roughly 27 megawatts of generating capacity, less than a tenth of what Tesla’s Buffalo panel line can produce in a single year.
The Backstory
Tesla bought SolarCity in November 2016 in an all-stock deal signed at $2.6 billion and worth about $2.1 billion by closing. Musk held roughly 22% of both companies and sat on both boards. Shareholders sued for $13 billion, arguing the purchase bailed out a company running out of cash. Vice Chancellor Joseph Slights ruled for Musk in April 2022, and the Delaware Supreme Court affirmed in June 2023.
Slights wrote something in that opinion worth more than the verdict. As of trial, he noted, Tesla still depended on outside solar companies to make and install parts of its own solar products. The integration Tesla had promised had not arrived six years after the deal closed.
Gigafactory New York tells the same story in concrete. New York State built the Buffalo plant for SolarCity, and Tesla said it would become the largest solar factory in the Western Hemisphere. Panasonic took over cell production there, then walked away in 2020. For years afterward Tesla used the building for Supercharger components and Autopilot data labeling. A billion-dollar solar factory spent half a decade as an office for people drawing boxes around traffic cones.
Meanwhile the storage business Tesla did not buy from SolarCity went vertical. Energy segment revenue climbed from $2.789 billion in 2021 to $12.771 billion in 2025, a 358% increase, on 46.7 GWh of deployments last year. Storage sells in gigawatt-hours and gets purchased in kilowatts, a unit mismatch that decides which battery businesses clear. In Q2 2026 alone Tesla deployed 13.5 GWh, its second-largest quarter, on $3.14 billion of energy revenue.
The Plan
At Davos in January 2026, Musk said Tesla and SpaceX would each build 100 GW per year of American solar manufacturing capacity, covering the chain from raw materials to finished panels. A Tesla job posting later put a date on it: 100 GW of solar manufacturing from raw materials on American soil before the end of 2028. Reuters reported Tesla in talks to buy roughly $2.9 billion of cell-production equipment from Chinese suppliers including Suzhou Maxwell, with delivery slated for late 2026. Electrek identified Brookshire, Texas, as the anchor site.
For scale, Intertek CEA put total US module manufacturing capacity slightly above 45 GW at the end of 2025, heading toward 60 GW in 2026. First Solar, the largest domestic manufacturer, expects around 18 GW by 2027. Tesla alone is talking about more than the entire country currently has.
The retail side got reorganized to match. Tesla stopped installing and started supplying, pushing hardware through certified third-party installers and holding an Installer Day to recruit them. In January it launched the TSP-415 and TSP-420 panels, assembled in Buffalo on a line rated at just over 300 MW a year. Those panels carry 18 independent power zones per module, a shading fix derived from the cascading-cell technology Tesla developed for the Solar Roof.
Tesla kept the physics and threw away the product.
The Business Model Angle
Run the arithmetic on the two businesses side by side and the decision writes itself.
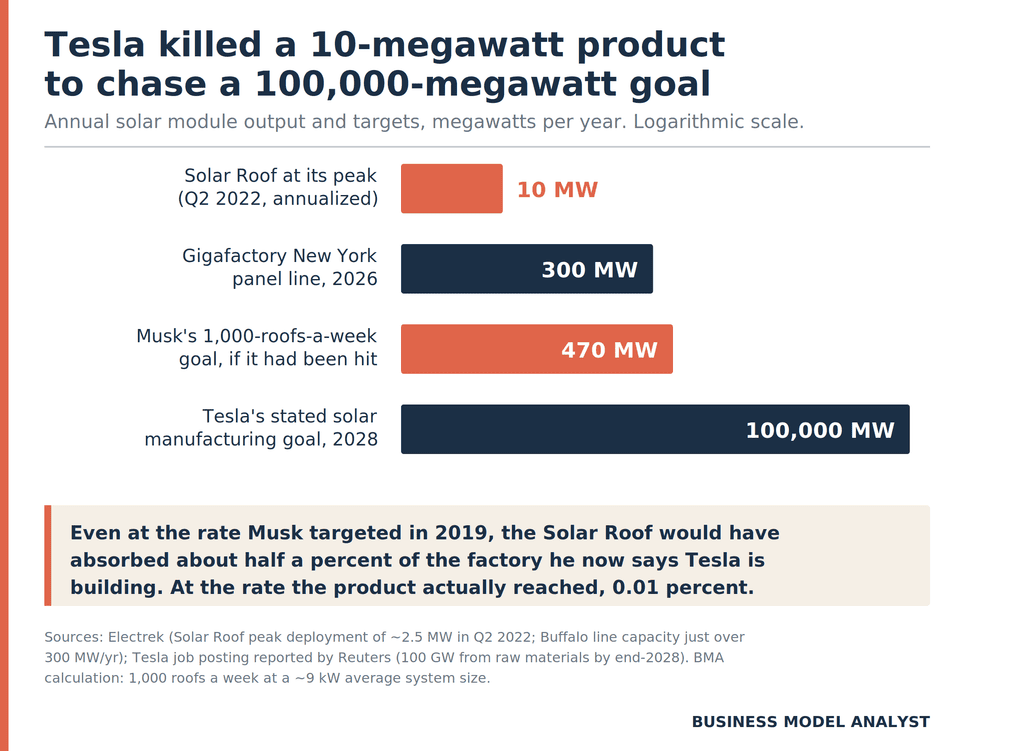
At its best quarter, the Solar Roof consumed about 10 MW of module output a year. Tesla’s stated 2028 goal is 100,000 MW. That is one hundredth of one percent. Push the roof to the rate Musk targeted in 2019, a thousand installs a week at a nine-kilowatt average, and you get 470 MW a year, still under half a percent of the factory he says Tesla is building. No version of the Solar Roof, including the fantasy version, absorbs a meaningful share of Tesla’s own solar ambition.
Two businesses sit at opposite ends of the same value chain, and they scale on different inputs. A module factory scales on capital and yield. Every dollar of tooling produces more watts per year forever. A solar roof scales on trained crews. Every additional roof requires another pitched surface measured, another underlayment spec, another set of penetrations, another 25-year liability attached to somebody’s house. Tesla spent six years engineering the cost curve out of a product whose binding constraint was labor, and got to 23 installs a week.
The tax code closed the argument. The One Big Beautiful Bill Act terminated Section 25D for expenditures made after December 31, 2025, ending the 30% residential credit seven years early. A homeowner buying a six-figure roof in 2026 lost $30,000 or more of federal support overnight. The surviving federal money flows through Section 48E to whoever owns the system, which routes demand into leases and power purchase agreements. Third-party ownership underwriting depends on standardized, removable, re-marketable hardware with a known salvage path. A financier can repossess a panel array. Nobody repossesses a roof.
SEIA logged 1,179 MWdc of US residential solar in Q1 2026, up 6% year over year but down 15% from Q4, and does not expect the segment to grow again until 2027, carried by third-party ownership. Tesla read the same data and moved its money upstream, where the customers are installers and developers rather than homeowners with a HELOC.
The Risk
Musk’s track record on manufacturing announcements argues against taking 100 GW at face value. Buffalo was supposed to be the largest solar plant in the hemisphere and became a data-labeling site. The Solar Roof was supposed to hit a thousand a week and reached 23. If the Texas plan lands the way Buffalo did, Tesla will have abandoned the consumer end of solar without arriving at the manufacturing end, leaving a 300 MW module assembler competing against First Solar and a wall of imports. Tesla carries the market capitalization of 37 automakers combined on businesses it has not built yet, and solar manufacturing is now one of them.
The cells are the tell. Tesla’s TSP-420 datasheet says the modules are assembled in Buffalo, which means someone outside the United States makes the cells inside them, and Tesla has not said who. Ingot, wafer and cell production carry most of the cost and all of the geopolitics. Tesla has not publicly claimed Foreign Entity of Concern compliance for the panel, which affects domestic-content eligibility on the lease financing that residential demand now runs through. Buying $2.9 billion of Chinese tooling to build American cells is a plan with an unresolved policy dependency sitting in the middle of it.
Then there is the installed base. Tesla’s Q2 2026 energy gross margin fell to 20.4% from 39.5%, driven by a $240 million warranty true-up that CFO Vaibhav Taneja tied to vendor cell issues on legacy deployments, alongside a Q1 tariff benefit that did not repeat and falling industrial storage prices. That charge had nothing to do with the Solar Roof, but it demonstrates the mechanism: obligations on hardware you sold years ago land in a quarter where they earn you nothing. Roughly 3,000 households now hold 25-year warranties on a discontinued product whose known failure modes include warping non-solar tiles, melting underlayment and underproduction. Taneja guided the energy business to normalize in the mid-to-low 20% gross margin range. Warranty tails are one reason why.
Quick Questions
Is the Solar Roof completely unavailable? Not yet. Installers told TechCrunch they can still supply it depending on project timing, which points to remaining inventory rather than continued production. Availability will depend on how full the warehouse is.
Does this mean Tesla is exiting solar? The opposite. Tesla launched a US-assembled panel in January, restarted the Buffalo line, expanded its solar team for the first time in five years and set a 100 GW manufacturing target. It exited one product category, not the industry. The full segment picture shows energy revenue rising while solar shrank inside it.
Why did the tiles underperform? Heat is the likely culprit. Solar cell voltage drops roughly half a percent per degree Celsius. Rack-mounted panels leave an air gap for cooling, and the Solar Roof’s gap was much smaller, so the cells ran hotter and produced less than Tesla projected.
Are integrated solar roofs dead as a category? GAF Energy and Merlin Solar are still selling. GAF’s Timberline Solar shingle installs with the same crew, tools and nail gun as an asphalt shingle, distributed through GAF’s existing network of roofing partners. Third-party estimates put solar shingle systems around $3.75 to $6.00 per watt installed against roughly $2.55 for rack-mounted panels, so the aesthetic premium remains real.
What happens to existing Solar Roof owners? Tesla has not published a support plan. The company redirected the product’s support pages along with the sales page, which owners of a 25-year asset will read as a warning sign.
The Business Model Analyst Take
Solar got cheap because the world standardized it. Billions of near-identical cells go into near-identical panels bolted to racks by crews who need one skill set. Every dollar of cost reduction over 15 years came from removing variation.
The Solar Roof was built on removing standardization. Its entire value proposition was that it did not look like everyone else’s solar, which meant custom tiles, custom tooling, custom engineering per house and a crew that could roof as well as wire. Tesla positioned a construction project as a consumer product and priced it as one. The cost curve that carried the rest of solar could never reach it, because that curve runs on sameness and the roof sold difference.
The survivors understood the channel better. GAF Energy is a roofing company that added solar and sells through roofers using tools roofers already own. Tesla was an electronics company that added roofing and tried to build the trade from scratch. When your differentiation sits upstream of your cost curve, you ride it. When it sits across the curve, you pay for the privilege forever.
For founders, the transferable question is narrower than solar. Ask which input your unit economics scale on. If it is capital and yield, growth compounds. If it is trained human hands touching a customized physical object, your cost per unit is close to flat no matter how good your engineering gets, and volume makes the problem larger rather than cheaper. Tesla took ten years and a $2.6 billion acquisition to learn that about roofs. It now proposes to spend a similar amount learning whether it can make cells.
The number to watch is not the 100 GW target. It is whether Brookshire produces a single American-made cell before the end of 2028. Panels assembled from someone else’s cells are the business Tesla already has.