
A Wall Street Journal report says Tesla executives were told to prepare to separate the China business ahead of a possible SpaceX merger. Musk called it “fake news.” The more useful fact is that Tesla China was designed to be cut loose years ago, and a defense contractor is the reason that design suddenly has a job to do.
The report, and the denial
On July 30, the Wall Street Journal reported that some Tesla executives had been told to prepare for a separation of the company’s China business, and that advisers had weighed a spinoff, sale, or outright closure, all ahead of a possible merger with SpaceX. The paper said it was unclear how fast Tesla could move and that the plans could change.
Elon Musk shot it down within hours. On X he called the report “absurdly fake news” and said the idea had “never even come up in a discussion ever,” adding that people should assume news is fake until proven otherwise. Tesla did not comment through official channels.
So treat the specific claim, “Tesla is preparing to sell China right now,” as single-sourced and disputed by the principal. That is the correct amount of skepticism. But it also sends most coverage chasing the wrong question. Whether or not a separation is being staged this quarter, the interesting part is already true and not in dispute: Tesla China was engineered to come apart cleanly, and a SpaceX combination is the scenario that would force the cut.
The thesis: this was architecture, not improvisation
Musk has spent years running Tesla with what the Journal described as a “laser” between the U.S. and China halves of the company. The stated reason was survival. If Beijing and Washington ruptured, or if China invaded Taiwan and choked off battery cells and Taiwanese chips, Musk wanted at least the U.S. side of Tesla to keep breathing. People involved put the target window at 2026 to 2027.
That is a hedge. What the merger talk exposes is that a hedge and a real option are the same object viewed from different angles. The exact modularity built to survive a geopolitical shock is also the modularity that would let Tesla hand off, spin out, or wall away its China unit for a corporate transaction. You do not build a detachable subsidiary twice. You build it once and then discover it has more than one use.
That is the business-model point most of the wire coverage skips. Corporate structure is not just plumbing. Designed well, it is stored optionality, and Tesla has been quietly funding that option for years.
The “laser” was cheap insurance that is now load-bearing
The separation kit is already partly built. Tesla runs two large Shanghai factories that make cars and batteries for China and for export, and unusually for a Western automaker, it owns them outright rather than through a Chinese joint venture. There is no local partner to negotiate out of the cap table, which is precisely what makes a clean detachment conceivable.
During the first Trump administration Tesla launched “Project Carbon” to move Chinese suppliers to Mexico. In 2025 it decided to stop using China-based suppliers in its U.S. factories by 2027. The Journal reports advisers have also discussed a separate sales entity for Shanghai exports and separate internal systems that would bar China-based staff from other units. Each of those steps looks like ordinary supply-chain and compliance hygiene in isolation. Stacked together, they are the pre-work for a corporate divorce, paid for one invoice at a time.
Why a merger forces the cut: the firewall math
Here is the constraint that makes the whole thing non-optional in a merger scenario. SpaceX is one of the most sensitive defense contractors in the country. It launches classified satellites, runs Starlink in active war zones, and books roughly a fifth of its revenue from the U.S. government, all under export controls and, for some programs, classification. A company like that cannot sit under the same corporate roof as wholly owned factories in China. The national-security machinery would not allow the crown jewel of American launch to be a sister company to Chinese manufacturing lines whose know-how and supply chain could be repurposed.
So a merger and a China business are mutually exclusive by construction. One of them has to go, and it is not going to be SpaceX.
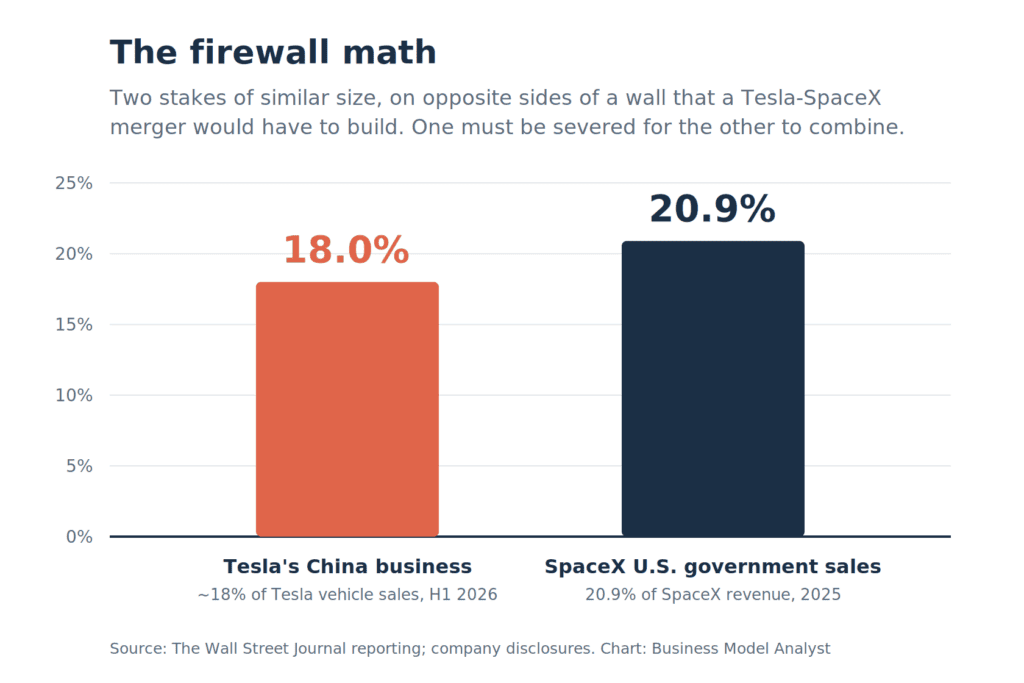
Two stakes of roughly equal weight sit on opposite sides of a wall a merger would have to build. Sources: WSJ reporting; company disclosures.
The tell everyone missed: this is an absorption, not a merger
Reset the frame. When people hear “Tesla and SpaceX merge,” they picture two Musk companies of similar stature joining hands. The valuations say otherwise. After its record June IPO, priced at $135 a share for an implied value near $1.77 trillion and the largest offering in history, SpaceX briefly traded above $2 trillion, worth more than Tesla, which sat near $1.2 trillion. SpaceX is now the larger animal.
And SpaceX has already run this exact play once. In February 2026 it absorbed xAI, folding Musk’s AI venture into the rocket-and-Starlink parent. Read the merger chatter through that lens and it stops looking like a partnership and starts looking like consolidation: Musk pulling his empire into a single, higher-valued holding entity built around SpaceX. In that story, Tesla is the company being brought in, and Tesla China is the one passenger that cannot board.
That reframing matters for how you weigh the whole thing. The question is not whether Tesla can detach China. It was built to. The question is whether the combination is worth more than the asset it costs.
What Tesla actually loses
Do not underrate the cost. China is not a rounding error Musk is trimming. It is the operation that turned Tesla from a volatile niche maker into a consistently profitable global EV leader. China is around 18% of sales in the first half of 2026, and Shanghai is Tesla’s export hub, shipping to markets around the world, everywhere except the U.S. In the most recent quarter the Shanghai factory was a core reason Tesla posted record deliveries even as operating profit thinned to a few hundred million dollars while capital spending jumped.
Cutting China loose severs Tesla’s cheapest production, a fifth of its demand, and its most efficient export base, and hands it to a market where BYD, Nio, and Xiaomi are already grinding Tesla’s share. For a fuller picture of how much of Tesla’s economics run through that operation, our Tesla business model breakdown and Tesla in charts both make the dependence hard to miss, and the current Tesla SWOT analysis already names BYD as the defining 2026 threat. Selling China does not make that threat smaller. It removes Tesla’s best position from which to fight it.
The precedents are real, and they cut both ways
Corporate history says this is doable. Yum Brands spun off Yum China in 2016 and sold stakes to local investors. Starbucks recently sold a majority stake in its China business. Splitting a China arm into a locally controlled entity is a well-worn move for U.S. multinationals nervous about the geopolitical tail.
But the sharpest precedent is a warning, not a template. In 2018 Qualcomm walked away from its purchase of NXP after failing to win clearance from Chinese regulators. That is the case that should worry Musk, because it shows Beijing can kill a deal it dislikes simply by declining to act. Which points at the real gatekeeper.
Beijing holds the veto, which is why “closure” is on the table
The binding constraint here is not American. It is Chinese. A Tesla-SpaceX combination would put a major U.S. defense contractor in control of factories on Chinese soil, and Beijing has every incentive to scrutinize that hard. Chinese regulators would worry about factory know-how flowing to the U.S. military, about the personal data of roughly two million Chinese Tesla owners landing inside an American defense company, and about dual-use materials like rare earths leaking from Tesla China toward SpaceX. Expect Beijing to demand guardrails, or to slow-walk approval the way it did to Qualcomm.
That is why the reported adviser menu is so revealing. Spinoff and sale are the friendly outcomes. “Closure” is the one nobody says out loud, and its presence on the list is the signal. It means the planners are pricing a world where China will not bless a clean handoff and Tesla may have to abandon the asset rather than transfer it. You only war-game a shutdown when you think the counterparty might refuse to let you leave with the furniture.
The Risk
The honest counterweight: Musk denied this flatly, it rests on unnamed sources, and it may be contingency planning dressed up as intent. Every serious multinational keeps a China break-glass plan; discovering that Tesla has one is not the same as Tesla executing it. On last week’s earnings call Musk declined to rule out a SpaceX combination but insisted it would need “the appropriate process,” which is what a CEO says whether a deal is imminent or purely hypothetical.
The market’s read is its own data point, and it is telling. Tesla shares rose more than 3% on the report. Investors are not treating a China separation as a loss to fear. They are treating a SpaceX merger as a prize to want, and they are willing to give up the China profit engine to get it. That enthusiasm is exactly the condition under which value-destructive deals get done, so it belongs in the risk column, not the reassurance column. The cleanest structure in the world does not guarantee the transaction is a good idea for the people holding standalone Tesla stock.
The Business Model Analyst Take
Strip away the denial and the drama and one durable idea remains. Tesla spent years building its China business as a module that could be removed without killing the host, and it paid for that optionality quarter after quarter through supplier relocations, ownership structure, and internal firewalls. That spending looked like geopolitical insurance. It turns out to double as merger infrastructure.
The lesson generalizes past Musk. In a fragmenting world, corporate structure is a strategic asset, and the boundary you draw around a business is itself an option you can exercise later. Companies that architect for separability, wholly owned where they can be, firewalled where they must be, buy themselves choices that rivals tangled in joint ventures and shared systems simply do not have.
Whether or not Tesla ever sells China, the reason this story is even plausible is that Musk already did the expensive part. The design is finished. The only open question is whether he decides the SpaceX prize is worth pulling the lever, and whether Beijing lets him. For how the two companies are put together on their own terms, see our SpaceX business model and Tesla value chain analysis.