
There is a version of the Tapestry story that reads like a straight triumph. Coach is the hottest handbag brand in America, the stock has roughly doubled in a year, the company has raised guidance three quarters running, and Wall Street now values the owner of Coach at nearly the same level as the owner of Gucci.
Then you open the segment tables.
In the fiscal third quarter of 2026, Coach delivered $595.2 million of operating income. Kate Spade delivered an operating loss of $20.7 million. Over the first nine months of the fiscal year, Coach produced $1.93 billion of operating income and Kate Spade produced $1.2 million. Not $1.2 billion. One point two million dollars, on $839.8 million of revenue.
That is the real Tapestry SWOT analysis. One brand is one of the best-run consumer businesses in the United States right now. The other is a $2.4 billion acquisition that has already been written down by $855 million and currently rounds to zero. Everything else follows from that gap.
SWOT analysis is a strategic framework that maps a company across four dimensions: Strengths (internal advantages), Weaknesses (internal constraints), Opportunities (external openings), and Threats (external risks). Strengths and weaknesses are things the company controls. Opportunities and threats are things it does not.
Tapestry, Inc. (NYSE: TPR) is the New York holding company that owns two brands: Coach and kate spade new york. It sold its third brand, Stuart Weitzman, to Caleres in August 2025. Most people searching for a “Coach SWOT analysis” are really looking for a Tapestry SWOT analysis, because Coach has no separate financials, no separate stock, and no separate strategy from its parent.
Accessible luxury is the market segment Tapestry plays in: handbags priced roughly between $200 and $600, above the mall brands and below Louis Vuitton and Chanel. It is a positioning choice, not a compromise, and in 2026 it is the segment that is winning.
Tapestry at a Glance
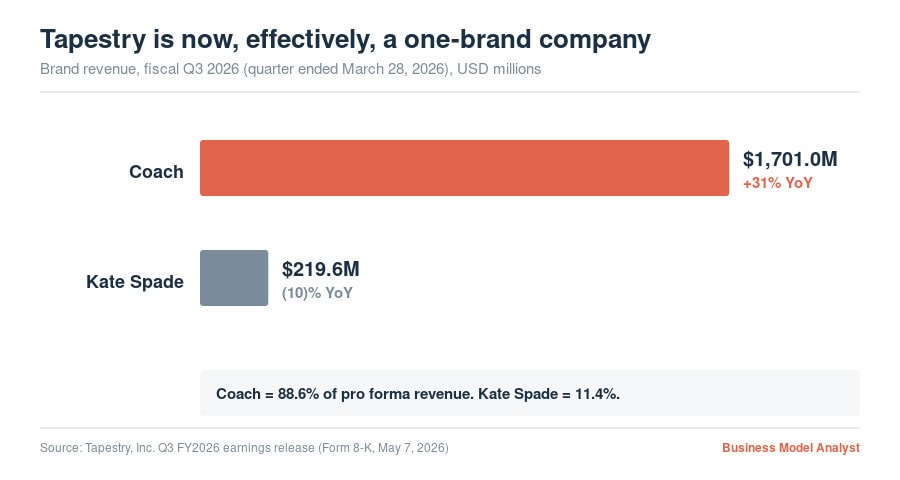
Two numbers frame the whole analysis. Coach is 88.6% of revenue. Kate Spade is 11.4%.
Strengths
| Strength | Why it matters |
|---|---|
| Coach’s brand turnaround is compounding | Six straight quarters of growth; Coach revenue up 31% in Q3 FY2026 |
| Gross margin near 77% | Higher than most listed luxury peers, and rising despite tariffs |
| Genuine Gen Z pull | Over 2.4 million new customers in Q3, with Gen Z more than 35% of them |
| Pricing power, not discount dependence | Handbag units up over 20% while average unit retail rose double digits |
| Fortress balance sheet | Leverage at 1.1x, roughly $1.6 billion returned to shareholders in FY2026 |
| Supply chain positioned away from China | Less than 10% of production sourced from China |
Coach is not “recovering.” It is compounding.
The distinction matters. A recovery implies a return to a previous level. What Coach has done is rebuild the brand’s entire demand engine around a small number of icon products, most visibly the Tabby and Brooklyn bags, sold at higher prices with less promotion. The proof is in the composition of growth. In the third quarter of fiscal 2026, Coach handbag units grew more than 20% and average unit retail rose at a low-double-digit rate at the same time.
That combination is rare and it is the single most important fact in this analysis. Most fashion brands can grow units by discounting or grow price by shrinking volume. Growing both simultaneously means the brand is more desirable this year than it was last year. Everything else on the strengths list is downstream of that one behavior.
The margin structure is quietly extraordinary
A 76.9% gross margin puts Tapestry in the same territory as European luxury houses that charge four times as much per bag. It gets there through a mix of high full-price sell-through, disciplined outlet strategy, and a sourcing base that is now roughly 70% concentrated in Vietnam, Cambodia, and the Philippines rather than China.
The operating margin tells the same story from the other end. Tapestry expanded GAAP operating margin by 630 basis points year over year in Q3 FY2026 while absorbing roughly 180 basis points of tariff and duty drag on gross margin. That is not cost cutting. Marketing spend actually increased by 160 basis points in the quarter. It is operating leverage from a brand people want.
One brand is doing all the work, and doing it superbly
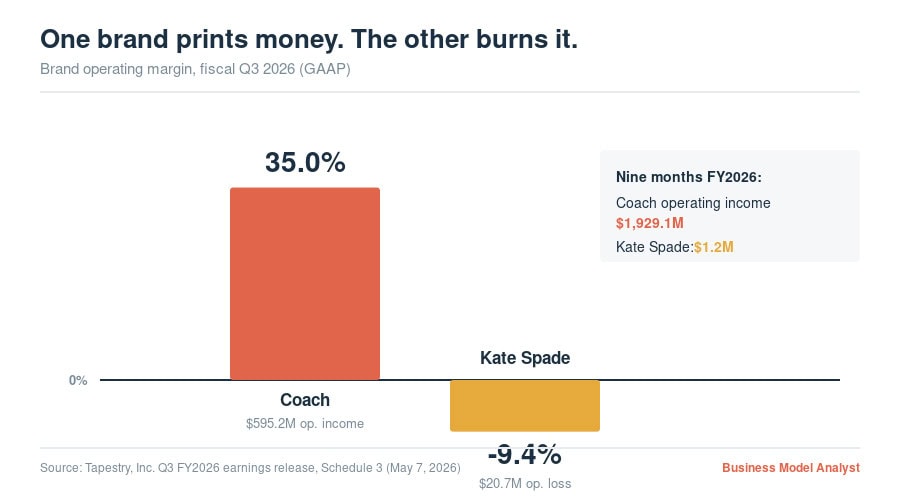
Coach’s 35% quarterly operating margin is the number that justifies the stock. It is also, awkwardly, the strongest possible argument that Tapestry does not need to be a “house of brands” at all.
Weaknesses
| Weakness | Why it matters |
|---|---|
| Kate Spade is a value-destroying asset | $855 million impairment in FY2025; roughly zero operating profit in FY2026 |
| Extreme single-brand concentration | Coach carries 88.6% of revenue and effectively all of the profit |
| Category concentration in handbags | Handbags are the majority of both brands’ sales |
| North America dependence | 57% of Q3 FY2026 revenue, with growth well below Asia |
| The Capri failure exposed a strategy gap | The $8.5 billion diversification plan was blocked, and there is no Plan B |
| Fashion risk is not diversifiable | Icon-led growth means an icon going cold is a company-level event |
Kate Spade is the weakness. Everything else is a footnote.
Tapestry bought Kate Spade in 2017 for $2.4 billion. Nine years later, the brand’s revenue is not meaningfully larger than it was at acquisition, it just absorbed an $855 million non-cash impairment against its brand intangible and goodwill, and it generated a $20.7 million operating loss in the most recent quarter.
The company is doing the sensible things. Eva Erdmann, hired from L’Oréal, has cut more than 30% of the handbag assortment to concentrate behind hero styles like the Duo bag at $295 to $495, has raised marketing spend, and has simplified the store experience. That is, almost line for line, the playbook that fixed Coach.
Here is the skeptical read, and it is the one most SWOT articles will not give you. The Coach playbook worked at Coach because Coach had latent brand heat to reawaken. Coach is an 85-year-old American leather house with genuine heritage and a logo people already wanted. Kate Spade is a brand with high awareness and, in Erdmann’s own framing, a conversion problem. Awareness without desire is a much harder starting position than dormant desire. You can spend your way to attention. You cannot reliably spend your way to want.
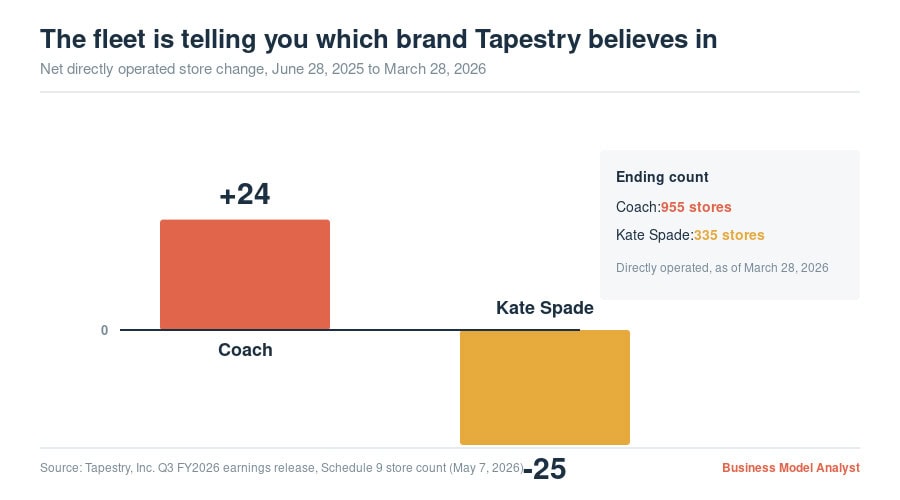
The store fleet shows what management actually believes, whatever the earnings call says.

The concentration risk is real, and it cuts both ways
Bulls will tell you Coach’s dominance is a feature: a focused company executing one strategy brilliantly. That is fair. But 88.6% of revenue in one brand, and the majority of that brand’s revenue in one category, means there is no internal hedge. If handbag fashion moves against Coach’s silhouettes, or if the Tabby cools the way logo-mania cooled for Michael Kors, there is nothing else in the portfolio to absorb it. Kate Spade cannot cushion a Coach slowdown. It cannot even cushion itself.
Opportunities
| Opportunity | Why it matters |
|---|---|
| Greater China | Grew 55% in constant currency in Q3 FY2026 off a small base |
| Europe | Grew 21% in constant currency; still a rounding error at $118.6 million |
| The luxury trade-down | European houses priced themselves out; accessible luxury is absorbing the shift |
| Gen Z acquisition | Gen Z is over 35% of new customers and compounds for decades |
| A disciplined acquisition, eventually | Leverage at 1.1x leaves enormous capacity |
| Kate Spade as pure option value | Written down and near zero profit, so any recovery is upside |
The geographic story is the growth story
North America is still 57% of the business and it grew 20%, which is an excellent number for a mature market. But the shape of the opportunity is offshore. Greater China grew 55% in constant currency on a base of $432.2 million. Europe grew 21% on a base of just $118.6 million.
Sit with that European number for a second. Tapestry generates less revenue in all of Europe in a quarter than Coach generates in about a week globally. For a brand with genuine international appeal and a price point that European consumers are actively migrating toward, that is either an indictment of past execution or the clearest runway on the whole income statement. It is probably both.
The trade-down is a structural gift, not a cyclical one
European luxury houses spent the 2010s and early 2020s raising prices aggressively. That worked until it did not. Shoppers who once stretched for an entry-level bag from a heritage house now find that bag priced beyond reach, and they are landing on Coach instead. This is why the market has closed the valuation gap between Tapestry and Kering to roughly $27 billion against $36 billion, when Kering was worth several times Tapestry only a few years ago, despite Kering owning ten brands to Tapestry’s two.
The skeptic’s counterpoint is worth stating: trade-down cuts both ways. If the consumer economy loosens and aspirational shoppers move back up to Gucci and Louis Vuitton, the same mechanic that filled Coach’s stores empties them. Tapestry’s counter is that it is not just capturing overflow, it is acquiring customers young and keeping them. The Gen Z acquisition numbers support that, but the thesis is unproven until it survives a genuine luxury upcycle. Compare this to how Gucci’s SWOT analysis reads from the opposite side of the same trade.
Threats
| Threat | Why it matters |
|---|---|
| Tariffs and trade policy | Roughly 120 basis points of margin headwind guided for FY2026 |
| Fashion cycle risk | Icon-led strategies fail suddenly, not gradually |
| The Michael Kors precedent | The last brand to win Gen Z with a hot logo bag lost them just as fast |
| Consumer weakness | Accessible luxury is discretionary, and mid-income wallets are stretched |
| Valuation expectations | The stock has roughly doubled; execution is now priced in |
| Regulatory limits on M&A | The FTC blocked Capri, so consolidation is no longer an easy lever |
Tapestry is now a fashion bet, not a value stock
The most underrated threat is not tariffs. Management has handled tariffs well, offsetting a 180 basis point gross margin hit in Q3 and still expanding margin. The threat is that Tapestry has been repriced from a cheap, unloved consumer name into a growth stock, and growth stocks are punished for stumbles that value stocks absorb.
At roughly $143 a share and a market cap around $30 billion, the market is now pricing in continued execution. Any quarter where Coach’s unit growth and average unit retail stop rising together is a quarter where the multiple, not just the earnings, comes under pressure.
The Michael Kors precedent should be tattooed on the boardroom wall
In the mid-2010s, Michael Kors was the hottest accessible luxury brand in America. Young consumers loved it. Growth looked structural. Then the brand overdistributed, over-discounted, lost its cachet, and spent the next decade in decline. Capri Holdings, its parent, was so weakened that Tapestry tried to buy it for $8.5 billion before the FTC blocked the deal in court in 2024.
Coach is currently doing everything Michael Kors did wrong in reverse: restricting promotion, holding price, controlling distribution. Management’s discipline here is the actual moat. But brand heat is a rented asset, and the rent is due every season.
The Capri failure removed the strategic escape hatch
Losing the Capri deal in the antitrust courts did not just cost Tapestry a target. It removed the entire diversification thesis. The company’s own capital allocation framing now says acquisitions wait until Coach is secure and Kate Spade has returned to sustainable growth. That is prudent. It also means the concentration risk is structural for years, not quarters, and it is being managed by buying back stock rather than by fixing the portfolio.
Tapestry by the Numbers
| Metric | Latest reported | Source and period |
|---|---|---|
| Revenue | $1.92 billion (+21%) | Q3 FY2026, quarter ended March 28, 2026 |
| Pro forma revenue growth | +25% (+23% constant currency) | Q3 FY2026, excludes Stuart Weitzman |
| Coach revenue | $1,701.0 million (+31%) | Q3 FY2026 |
| Kate Spade revenue | $219.6 million (-10%) | Q3 FY2026 |
| Coach operating income | $595.2 million | Q3 FY2026 |
| Kate Spade operating loss | $20.7 million | Q3 FY2026 |
| Gross margin | 76.9% (+80 bps) | Q3 FY2026 |
| GAAP operating margin | 22.3% (+630 bps) | Q3 FY2026 |
| GAAP diluted EPS | $1.65 (+74%) | Q3 FY2026 |
| Cash and short-term investments | $1.07 billion | As of March 28, 2026 |
| Total borrowings | $2.38 billion | As of March 28, 2026 |
| Leverage ratio | 1.1x gross debt to adjusted EBITDA | As of March 28, 2026 |
| Inventory | $844 million | As of March 28, 2026 |
| Kate Spade impairment | $855 million | FY2025, non-cash |
| Shareholder returns | $1.6 billion planned | FY2026 guidance |
| FY2026 revenue guidance | Approximately $7.95 billion | Raised May 7, 2026 |
All figures are from Tapestry’s Q3 FY2026 earnings release and financial schedules filed with the SEC on May 7, 2026, and its FY2025 fourth quarter and full year release of August 14, 2025.
How Tapestry Compares
| Dimension | Tapestry | Capri Holdings | LVMH / Kering |
|---|---|---|---|
| Positioning | Accessible luxury | Accessible luxury | Absolute and aspirational luxury |
| Brand count | 2 | Multiple | Dozens |
| Core price band | Roughly $200 to $600 | Roughly $200 to $600 | $1,500 and up |
| Current momentum | Strong, Coach-led | Rebuilding | Mixed, pressured by trade-down |
| Structural risk | Single-brand concentration | Brand heat recovery | Price ceiling reached |
| Relationship | Tried and failed to buy Capri | FTC blocked Tapestry deal | Competes for the same aspirational shopper |
The comparison exposes the strategic irony. Tapestry’s greatest strength, an intensely focused two-brand portfolio, is the exact thing it spent $8.5 billion trying to escape. The failed Capri deal may end up being the most valuable acquisition Tapestry never made.
For a contrasting model of brand-led fashion economics, see the Zara SWOT analysis, where speed replaces desire as the core competitive weapon.
Frequently Asked Questions
Is Coach the same company as Tapestry? Coach is a brand owned by Tapestry, Inc. The parent company was called Coach, Inc. until 2017, when it renamed itself Tapestry after acquiring Kate Spade and Stuart Weitzman. Coach has no separate stock or financial statements.
What is Tapestry’s biggest strength? Coach’s ability to grow handbag units and average selling prices at the same time. In fiscal Q3 2026, Coach handbag units rose more than 20% while average unit retail rose at a low-double-digit rate. That means demand is growing without discounting.
What is Tapestry’s biggest weakness? Kate Spade. The brand was acquired for $2.4 billion in 2017, took an $855 million impairment in fiscal 2025, and produced roughly $1.2 million of operating income across the first nine months of fiscal 2026 on $839.8 million of revenue.
Why did the Tapestry and Capri deal fail? The U.S. Federal Trade Commission successfully blocked the $8.5 billion acquisition in court, and Tapestry terminated the deal in late 2024. Tapestry then redirected the capital into share buybacks.
Does Tapestry still own Stuart Weitzman? No. Tapestry completed the sale of Stuart Weitzman to Caleres on August 4, 2025.
Is Tapestry exposed to tariffs? Yes, but less than most. Tariffs and duties cost roughly 180 basis points of gross margin in fiscal Q3 2026, and the company guided to roughly 120 basis points of headwind for the full year. Less than 10% of production comes from China, with the bulk sourced from Vietnam, Cambodia, and the Philippines.
The Business Model Analyst Take
Tapestry is two companies wearing one ticker, and the market has finally decided to pay for the good one.
Coach is currently the best-executed brand turnaround in American consumer goods. A 35% operating margin, 31% growth, Gen Z acquisition at scale, and pricing power in a discount-obsessed retail environment is not luck. It is a decade of disciplined refusal to chase volume, and it has earned Tapestry a valuation that now sits within striking distance of Kering, a company with five times the brands.
But the SWOT does not resolve as cleanly as the stock chart implies. Strip Kate Spade out and Tapestry is a single-brand, single-category, fashion-cycle-exposed business with no internal hedge and no acquisition path, because the regulator closed it. Management is returning essentially all of its free cash flow to shareholders, which is the right call when you have no better use for it, and also an admission that you have no better use for it.
The bull case and the bear case are the same sentence: Tapestry’s future is entirely a function of how long Coach stays hot. Bulls read that and see a brand with real heritage, genuine product discipline, and a young customer base compounding for decades. Bears read it and remember that Michael Kors was this brand ten years ago.
What we would actually watch is not revenue and not EPS. It is the units-versus-price relationship at Coach. As long as both keep rising together, the machine is healthy and every other risk is manageable. The quarter where units keep growing but average unit retail flattens is the quarter to pay attention, because that is what the beginning of a promotional slide looks like from the inside. Nobody announces it. It shows up in the mix first.
Kate Spade, meanwhile, should be judged on a much simpler test: has it made money yet. Everything else is narrative.