
Put these two on the same pitch and the pre-match graphics look absurd. One side is a small, landlocked, banking-and-pharma machine of nine million people that quietly prints one of the highest living standards on earth. The other is a continent-sized energy state of nearly fifty million, sitting on some of the largest gas reserves in the world and still figuring out how to turn that wealth into broad prosperity. On raw output per person, this looks like a mismatch. Look closer and it turns into the most interesting kind of business case: two completely different strategies for turning a country into a revenue engine.
This is the same lens we used for Norway vs Ivory Coast, and the pattern rhymes. So strip away the flags and read the tape.
The Economic Scoreboard

Switzerland’s nominal GDP sits at roughly $1.04 trillion in 2025, against Algeria’s $286 billion. That is a Champions League club playing a hungry, well-drilled side that has never won the trophy but knows how to frustrate a favorite. The headline gap is real. The story underneath it is where the match actually gets decided.
First half: Switzerland runs away with it
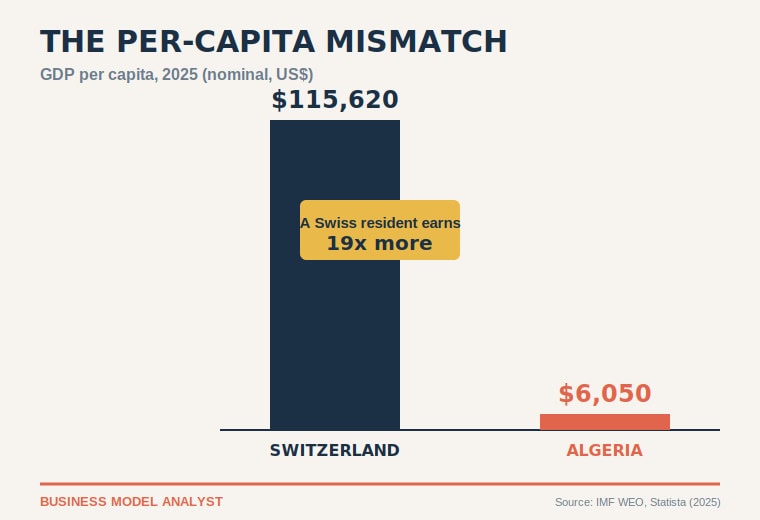
On the numbers that measure how rich each citizen actually is, this is not close. Switzerland’s GDP per capita is around $115,620. Algeria’s is about $6,050. That is roughly a nineteen-fold gap per person.
Switzerland earned that number the boring, durable way. It sells things the world cannot easily copy and cannot easily stop buying: pharmaceuticals from Roche and Novartis, private banking and wealth management, precision machinery, watches, and the kind of consumer brands that anchor entire categories. Nestlé alone, the Swiss food giant behind everything from Nespresso to global bottled water, is a case study in high-margin, defensible cash flow. The common thread is pricing power. When your export mix is drugs, capital, and trust, you are not competing on price. You are the price.
Add near-zero inflation (about 0.2% in 2025), a rock-solid franc treated as a global safe-haven asset, and a jobless rate that by the national measure sits under 3%, and you have an economy that behaves like a blue-chip balance sheet. Slow-growing, yes. But almost impossible to knock over.
The comeback: why Algeria is not out of this
Here is where lazy analysis stops and the interesting read begins. Nominal GDP flatters rich, expensive countries and punishes cheaper ones, because it converts everything at market exchange rates. Switzerland is one of the most expensive places on the planet to buy a coffee, a haircut, or an apartment. A dollar of income does far less there than it does in Algiers.
Adjust for that with purchasing power parity and the picture shifts. Algeria’s GDP per capita jumps to roughly $18,510 on a PPP basis, and its total economy is worth close to $875 billion in PPP terms, more than triple the nominal figure. Switzerland stays enormous, but its lead compresses meaningfully once you account for what money actually buys on the ground.
Then there is the clock. Algeria’s economy grew about 3.4% in 2025, more than double Switzerland’s 1.4%, and it has a median age under thirty against Switzerland’s demographic that is aging and shrinking without immigration. Switzerland is a mature champion protecting a lead. Algeria is a young side that is still growing into its body. Over a long enough tournament, that matters.
Two different engines
The most important chart in this match is not about size. It is about structure.
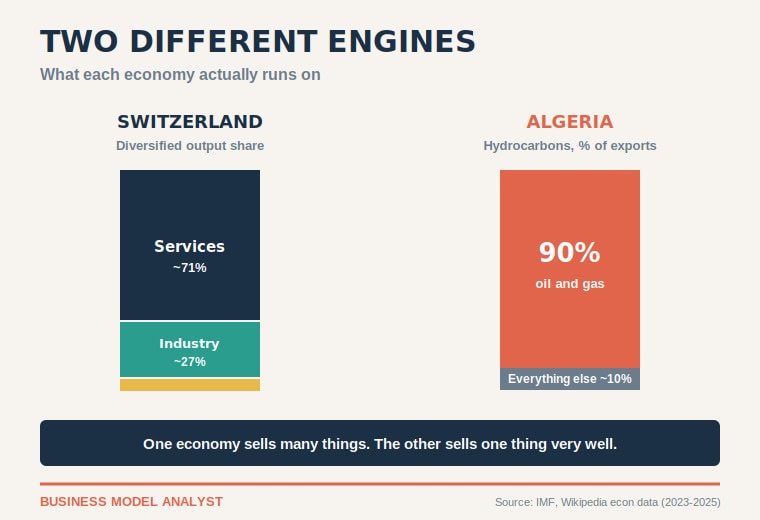
Switzerland’s output is spread across services (around 71%), high-value industry (around 27%), and a tiny farming sector. No single shock takes the whole thing down. Algeria runs the opposite model. Hydrocarbons account for roughly 90% of export revenue and about 60% of government income. The state oil and gas company, Sonatrach, is effectively the national team, the sponsor, and the stadium all at once.
That concentration is a strength and a trap. When gas prices are high, as they were after Europe scrambled to replace Russian supply, Algeria is flush and its budget balances. When prices fall, the whole economy catches a cold. This is the classic single-commodity vulnerability, and it is exactly the dynamic that makes the world’s most profitable companies list so oil-heavy and so cyclical. Owning a low-cost resource is a genuine moat. Depending on it for nine out of every ten export dollars is a bet you have to keep re-winning.
The strategic read for operators
Forget the flags for a second and this becomes a lesson every founder and operator already knows in their gut. Where in your value chain does the money actually stick, and how many ways can it be taken from you?
Switzerland is the business that spent decades moving up the value chain until it owned the margin: the brand, the IP, the customer relationship, the trust. Hard to disrupt, hard to displace, and it compounds quietly. Algeria is the business sitting on a fantastic raw input that still sells too much of it unrefined, capturing the commodity price rather than the finished-product margin. The upside is obvious. The government knows it, which is why diversification and downstream processing have been national priorities for years. The execution is the hard part, and it is unfinished.
For anyone tracking where the world’s growth and market-entry openings actually are, both models show up on the largest economies map for different reasons. One is a mature, high-trust market you sell premium services into. The other is a young, resource-rich market in the middle of trying to rewire its own engine, which is precisely when foreign expertise and capital get invited in.
The Business Model Analyst Take
On the scoreboard the world uses, Switzerland wins this comfortably: nineteen times the output per person, a fortress currency, and a diversified, defensible economy that behaves like a blue-chip stock. If the match were played today on living standards alone, it is not a contest.
But the smarter bet is structural, not final. Switzerland has already solved the problem every economy is trying to solve. It owns the high-margin end of its value chain and it is nearly impossible to knock over. Its risk is not collapse, it is slow fade: an aging, expensive economy growing barely above a crawl. Algeria has the harder, more exciting problem. It holds a world-class asset, a young population, and growth that laps its opponent, but it has staked almost everything on one input it does not control the price of. Diversify successfully and it climbs for a generation. Fail, and it stays hostage to the gas market.
The final read: Switzerland is the champion you would bet on to win the trophy. Algeria is the side you would bet on to still be improving five years from now. In football and in economics, those are two very different kinds of winning, and only one of them is finished.