
Sweetgreen’s target market is the affluent, college-educated urban professional aged roughly 25 to 45, buying a customizable $14 to $17 weekday lunch within walking distance of a dense office core. As of Q1 2026 the company operates 285 restaurants across 24 states and Washington, D.C., with 67.2% of revenue flowing through digital channels. That segment definition built the brand, and it is now the reason the brand is in trouble: same-store sales fell 12.8% in Q1 2026, driven almost entirely by an 11.2% collapse in guest traffic. Sweetgreen’s 2026 strategy is not a marketing refresh. It is an attempt to replace its target market.
Most analyses of Sweetgreen’s customer stop at a comfortable sentence: health-conscious millennials with disposable income. That sentence was true in 2019, it is repeated on a dozen competitor pages, and it explains nothing about what is happening to the company right now.
Here is the part that actually matters. Sweetgreen did not build a target market. It built a target occasion, and it built exactly one of them. The company monetized a single act: a salaried knowledge worker, in a dense metro, on a weekday, between roughly 11:30 and 2:00, buying lunch to eat at a desk. Everything else in the model, the real estate strategy, the digital ordering stack, the seasonal menu, the Infinite Kitchen automation, was engineering in service of that one occasion.
When one occasion is your entire business, you have no shock absorber. Sweetgreen is now discovering what that costs.
Who Sweetgreen Actually Sells To
The company does not publish customer demographic breakdowns, so anyone quoting precise household income percentages for Sweetgreen guests is guessing. What Sweetgreen does disclose, and what its own strategy reveals, is far more useful than a fabricated survey stat.
| Segmentation layer | The Sweetgreen customer | What the company’s own data confirms |
|---|---|---|
| Demographic | Adults roughly 25 to 45, college-educated, professional or knowledge-work employment, above-median household income | Menu priced at a $16 average check, positioned in premium urban real estate |
| Geographic | Dense metro cores, with heavy concentration in the New York metro area, plus Los Angeles, Boston, Chicago, and Washington, D.C. | 285 restaurants in 24 states and D.C.; analysts flag NY metro concentration and above-average urban exposure as a structural risk |
| Behavioral | Digital-first, high-frequency, habit-driven. Orders through the app, picks up, eats at a desk | 67.2% total digital revenue, 38.9% owned digital revenue in Q1 2026, both rising even as traffic falls |
| Psychographic | Health optimization, ingredient transparency, sustainability signaling, “eating well” as identity | Seasonal sourcing, published macros, protein-forward menu positioning |
| Occasion | Weekday lunch. Almost exclusively. | The entire 2026 turnaround is built on adding new occasions the company was not capturing |
That last row is the whole analysis. The other four are shared with Chipotle, Cava, and half of fast casual. The occasion row is what makes Sweetgreen structurally different, and structurally fragile.
The Numbers That Reframe Everything
Sweetgreen’s decline is not a slow fade. It is five straight quarters of accelerating contraction.
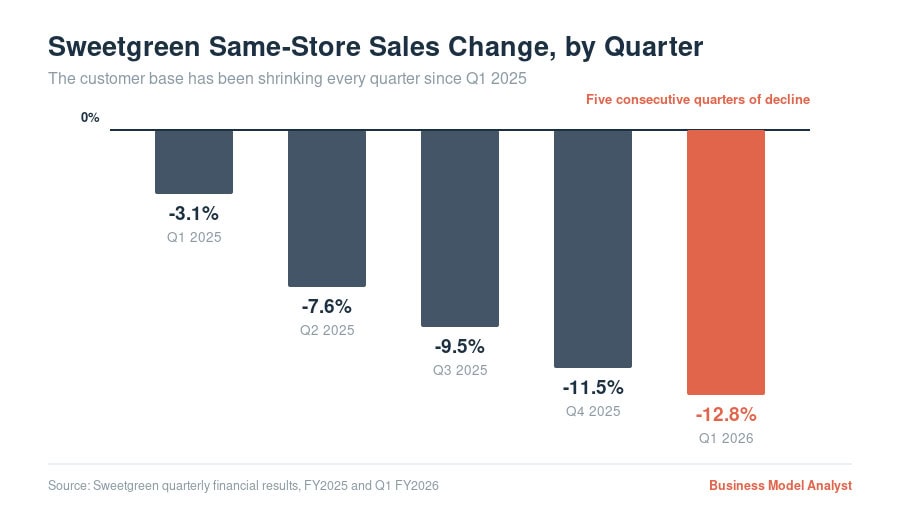
Q1 2025 was the first same-store sales decline in the company’s public history. Then it got worse every single quarter. Full-year 2025 same-store sales fell 7.9%, traffic dropped 13.3%, and the net loss widened to $134.1 million from $90.4 million the prior year. Q1 2026 posted revenue of $161.5 million, restaurant-level margin of 10.0% against 17.9% a year earlier, and an adjusted EBITDA loss of $8.1 million.
Now look at why the comp fell, because this is where the conventional read breaks.
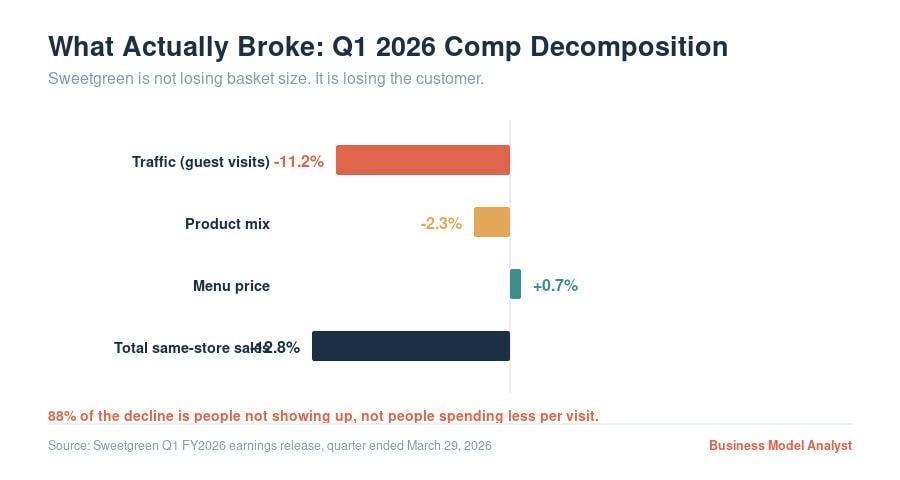
Of the 12.8% comp decline, 11.2 points came from traffic. Guests are not trading down inside Sweetgreen. They are not swapping the salmon bowl for the hummus crunch. They are simply not walking in the door.
That distinction matters enormously for a target market analysis. A basket-size problem means your customer is under financial pressure but still loyal. A traffic problem means your customer has substituted you for something else entirely, or has removed the occasion from their week.
The Price Story Everyone Gets Wrong
The internet consensus on Sweetgreen is that it sells $20 salads to people who have finally stopped tolerating $20 salads. It is a satisfying narrative. It is also not what the data says.
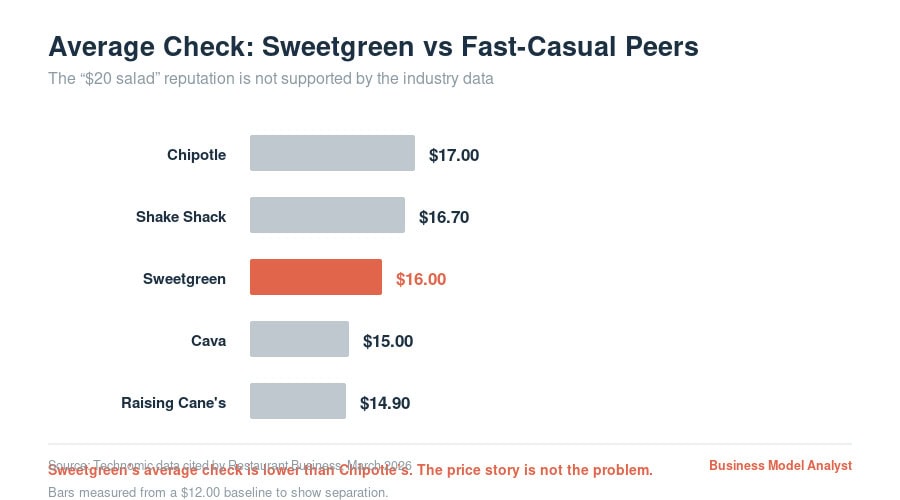
Technomic data cited by Restaurant Business puts Sweetgreen’s average check at roughly $16, which lands below Chipotle at $17 and Shake Shack at $16.70, and only modestly above Cava at $15. Sweetgreen’s average bowl price is closer to $14 nationally, and in Texas the average menu price falls under $13.
Chipotle and Cava are not collapsing. Sweetgreen is. If price were the binding constraint, the entire premium bowl category would be down 12%. It is not.
So the price narrative fails as an explanation. Which leaves the occasion.
The real diagnosis: Sweetgreen’s customer did not get poorer. That customer’s lunch changed. Hybrid work thinned the weekday office lunch rush in exactly the dense urban cores where Sweetgreen concentrated its real estate. The occasion did not trade down. It disappeared on Mondays and Fridays, and it got optional on the days that remained. A brand with dinner traffic, family traffic, or suburban drive-thru traffic absorbs that. A bowl-only lunch concept in Midtown does not.
Reputation still matters here, but as a perception problem rather than a pricing one. Sweetgreen carries the price penalty of a premium brand without actually charging premium-versus-peer prices. That is the worst possible position: you pay the reputational cost of expensive without collecting the revenue.
Sweetgreen Is Not Repositioning. It Is Replacing Its Segment.
Read what the CEO said in February 2026 about the new wraps line, and read it as a target market statement rather than a menu announcement:
Jonathan Neman said the addressable market for wraps and handhelds represents a large population segment that a bowl-only concept was never capturing, and that the launch widens the aperture on both the customers and the occasions the brand can serve.
That is a chief executive publicly conceding that the company’s target market was too narrow to support the business it built. Wraps launched nationally in May 2026, priced from $10.95, the most significant menu expansion in years by the company’s own framing.
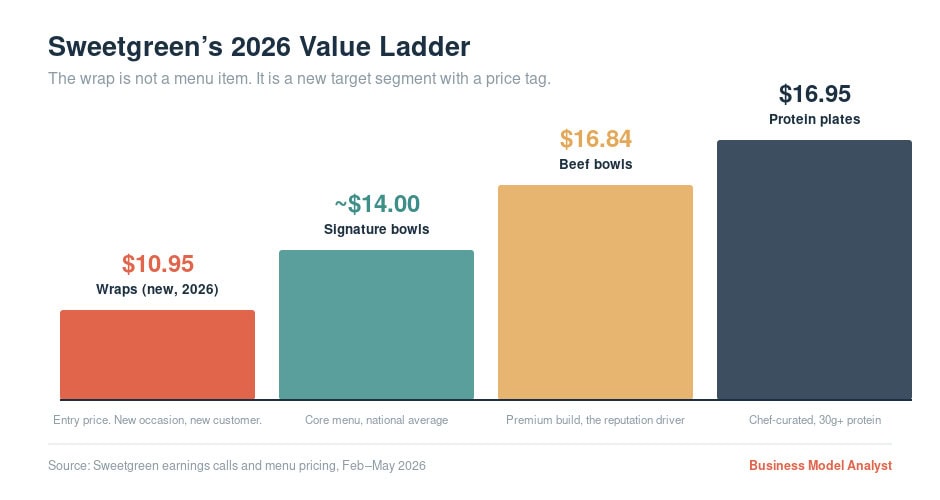
Stack the 2026 moves together and the pattern is unmistakable. Every one of them is a segment-expansion play dressed as a menu or pricing initiative:
| 2026 move | Presented as | What it actually does to the target market |
|---|---|---|
| Wraps at $10.95 to $15 | Menu innovation | Creates a sub-$12 entry point and a handheld, portable occasion the bowl format excluded |
| Repricing “Create Your Own” (about a quarter of sales) | Price clarity | Lowers the perceived cost of entry for the price-sensitive lapsed guest |
| 30g+ protein dishes, macro calculator, 25% larger chicken and tofu scoops | Menu innovation | Chases the fitness and gym-adjacent consumer, a demographic that skews more male than the historical base |
| Clear entry prices with trade-up ladders | Value perception | Converts a flat premium menu into a tiered one that can serve multiple income segments at once |
| SG Rewards replacing Sweetpass+ | Loyalty upgrade | Shifts from a paid subscription that only rewarded the highest-frequency loyalist to a broader engagement layer |
| Infinite Kitchen automation, 33 of 285 restaurants | Operational efficiency | Lowers the labor cost floor, which is what makes a $10.95 price point survivable |
None of these serve the affluent urban professional who was already buying a $16 Harvest Bowl. All of them serve someone else.
The Strategic Trap
Here is the counterargument Sweetgreen’s management has to answer, and it is a serious one.
The company is trying to broaden its target market downward on price while maintaining a cost structure built on seasonal sourcing, high-rent urban real estate, and made-to-order assembly. Those are premium-brand costs. Restaurant-level margin has already fallen to 10.0%, partly because the company increased protein portions, a decision that raised food costs to win back value perception.
Widen the funnel with a $10.95 wrap and you get more guests. You also get a lower average check, a thinner margin per transaction, and a brand that has voluntarily surrendered the one thing it had left: a clear premium identity. Restaurant Business made this point sharply in March 2026, noting that a heavy focus on menu price could push existing customers toward the cheaper items and, because Sweetgreen is not profitable to begin with, trigger a cost-cutting spiral that damages the product itself.
That is the trap. Sweetgreen’s original segment was too narrow to support 1,000 restaurants. Its new, broader segment may be too price-sensitive to support Sweetgreen’s cost structure. There is no obvious version of this company that serves both.
The company’s own capital allocation shows management knows it. Unit growth for 2026 was cut to roughly 13 to 15 net new restaurants, down from 35 opened in 2025, with a stated willingness to close units that are not cash-flow positive. You do not slow expansion by 60% if you believe your addressable market is intact.
How Sweetgreen’s Segment Compares to Fast-Casual Peers
| Brand | Core occasion breadth | Average check | Structural advantage Sweetgreen lacks |
|---|---|---|---|
| Chipotle | Lunch and dinner, urban and suburban, families and individuals | $17 | Dinner daypart and suburban drive-thru format |
| Cava | Lunch and dinner, growing suburban footprint | $15 | Lower entry price and a cuisine with dinner permission |
| Shake Shack | Lunch, dinner, indulgence, families | $16.70 | Indulgence occasion is recession-resilient in a way health optimization is not |
| Sweetgreen | Weekday lunch, urban, individual | $16 | None of the above |
The Chipotle target market analysis is instructive as a contrast. Chipotle sells to a similar demographic but across at least two dayparts and two geographic formats. That optionality is not a nice-to-have. It is what lets a brand survive a shock to any single occasion.
Information Gain: The Data Points Competitors Do Not Have
- 11.2 of the 12.8 points. Traffic, not price, accounts for 88% of Sweetgreen’s Q1 2026 comp decline. Almost every competing article on this topic frames Sweetgreen’s problem as pricing. The company’s own filings say otherwise.
- $16 versus $17. Sweetgreen’s average check is below Chipotle’s, per Technomic data cited by Restaurant Business. The “$20 salad” framing is a reputation artifact, not a fact.
- 35 to roughly 13. Net new restaurant openings dropped from 35 in 2025 to a guided range of about 13 to 15 in 2026, with half featuring Infinite Kitchen automation.
- 67.2%. Total digital revenue percentage in Q1 2026, up from 59.9% a year earlier. Digital penetration is rising while traffic falls, meaning the remaining loyalists are the most digitally habituated segment. The casual walk-in guest is the one who left.
- $134.1 million. FY2025 net loss, widened from $90.4 million in FY2024, despite opening 35 restaurants.
- 10.0%. Q1 2026 restaurant-level profit margin, down from 17.9%, with larger protein portions cited as a contributing cost.
FAQ
Who is Sweetgreen’s target market? Affluent, college-educated urban professionals aged roughly 25 to 45, buying a customizable weekday lunch at a $14 to $17 price point in dense metro areas. As of 2026 the company is actively trying to broaden this to include price-sensitive guests, fitness-focused consumers, and portable handheld occasions through its wraps line, which starts at $10.95.
Is Sweetgreen too expensive? Not relative to peers. Technomic data cited by Restaurant Business puts Sweetgreen’s average check at about $16, below Chipotle at $17 and Shake Shack at $16.70. Sweetgreen has a perception of being expensive that exceeds its actual price position, which is arguably the worse problem.
Why are Sweetgreen sales declining? Same-store sales fell 12.8% in Q1 2026, and 11.2 points of that came from a drop in guest traffic rather than smaller baskets. The most credible explanation is occasion loss: the brand is overwhelmingly dependent on the urban weekday office lunch, an occasion that thinned structurally with hybrid work and has no second daypart to compensate.
What is Sweetgreen doing to fix it? The Sweetgrowth transformation plan combines a national wraps launch at entry prices from $10.95, a repricing of the Create Your Own menu, protein-forward marketing with a macro calculator, the SG Rewards loyalty platform, the Project One Best Way operations program, Infinite Kitchen automation in 33 restaurants, and a sharp slowdown in new unit openings.
Who are Sweetgreen’s main competitors? Cava is the most direct threat, competing on the same bowl format at a lower average check with broader daypart appeal. Chipotle competes for the same customer with a wider occasion set, and Starbucks competes for the same urban professional’s daily discretionary food spend.
Does Sweetgreen still target health-conscious millennials? Yes, but that is no longer the strategy. The 2026 pivot is explicitly about serving customers the bowl-only format excluded. Management has stated that a large population segment was never being captured, which is a direct admission that the original target market was too narrow.
The Business Model Analyst Take
The story every competitor page tells about Sweetgreen is that its customers got tired of expensive salads. The data does not support it. Sweetgreen’s check is lower than Chipotle’s, and Chipotle is fine.
The real story is that Sweetgreen confused a target occasion for a target market. It built a beautiful, digitally sophisticated, operationally elegant machine for one moment in one person’s week, in one type of neighborhood, on one type of day. For a decade that focus was the source of its advantage. Then hybrid work quietly removed a chunk of that moment from the calendar, and the company found it had nothing else to sell to anybody else.
The 2026 turnaround is the right diagnosis. Wraps, entry prices, protein plates, and macro calculators are all attempts to buy occasions the company never owned. But management should be honest with itself about what it is doing, and so should investors. This is not “improving value perception.” This is a premium urban lunch brand attempting to become a mainstream fast-casual chain while carrying a premium urban cost structure, with a 10% restaurant-level margin and no profits to fund the transition.
The segment that made Sweetgreen worth $6 billion at IPO is not coming back at the size it once was. The segment Sweetgreen is now chasing already belongs to Cava, Chipotle, and Panera, all of whom have better unit economics and broader footprints. Whether Sweetgreen can take share in a category it has never competed in, using a cost base designed for a category it is leaving, is the only question about this company that matters.
Watch traffic, not comps. If traffic turns positive while the average check holds above $14, the new segment is real. If traffic turns positive only because the check collapses toward $12, Sweetgreen has not found a new market. It has just discounted its way into someone else’s.
Financial figures from Sweetgreen’s Q1 fiscal 2026 results (quarter ended March 29, 2026) and fiscal year 2025 results. Average check data from Technomic as cited by Restaurant Business.