
On June 11, 2026, the US Climate Prediction Center quietly upgraded its alert from an El Niño Watch to an El Niño Advisory. The wording shift matters more than it sounds. A Watch means an event is likely to form. An Advisory means it has arrived. El Niño conditions are now present in the equatorial Pacific, and forecasters put the odds of it reaching “very strong” status this winter at 63 percent. For global business, that single number is the start of a supply shock that historically takes years, not months, to play out.
The headlines are already calling it a “Super El Niño.” Before any company builds that phrase into a risk model, it is worth being precise about what it does and does not mean.
What “Super El Niño” Actually Means (And What It Doesn’t)
Here is the first thing most coverage gets wrong: “Super El Niño” is not an official classification. The World Meteorological Organization does not use the term because it is not part of any standardized operational system. It is media shorthand for a very strong event, which NOAA defines as sea surface temperatures running more than 2.0 degrees Celsius above average in the central Pacific.
That distinction is not pedantic. It tells you how to read the forecasts. NOAA currently assigns a 63 percent probability to a very strong event during the November to January peak, and European models from ECMWF have floated anomalies potentially exceeding 2.5 degrees by October. If realized, the 2026-27 event would join a short list of only six comparable El Niños since 1950: 1972-73, 1982-83, 1997-98, 2015-16, and 2023-24. Those years are the historical template for what follows.
The caveat every operator should hold onto: these forecasts are being issued near the end of the spring predictability barrier, the time of year when ENSO forecast skill is weakest. The probabilistic signal is unusually strong, but the magnitude and timing of the peak remain genuinely uncertain. Plan for the central case, hedge for the tail.
The Trillion-Dollar Price Tag
The most useful number in this entire story comes from a 2023 study in Science by Dartmouth researchers Christopher Callahan and Justin Mankin. They tracked GDP growth before and after every El Niño from 1960 to 2019 and reached a conclusion that reframes the whole conversation: economies do not absorb a hit and bounce back. They stagnate for years.
Their attribution figures are the ones to anchor on. The 1982-83 event cost the global economy roughly 4.1 trillion dollars in lost income. The stronger 1997-98 event cost about 5.7 trillion. Looking forward, they project 84 trillion dollars in cumulative economic losses across the 21st century as warming amplifies ENSO swings. Most strikingly, their data suggests the drag from a single major El Niño can persist for up to 14 years after the event itself.
A separate 2023 analysis in Nature Communications puts harder edges on the near-term hit. It estimates the contemporaneous loss in the event year alone at 246 billion, 401 billion, and 739 billion dollars for the 1982-83, 1997-98, and 2015-16 events respectively, roughly 1 percent of global GDP each time. The cumulative four-year toll reached as high as 3.9 trillion dollars, or 4 to 5 percent of global GDP, for the strongest of the three. That is the order of magnitude businesses are budgeting against if 2026-27 lands where forecasters expect.
Where the Pain Lands First: Soft Commodities
The fastest transmission channel is the grocery aisle. Every strong El Niño in the past 55 years has reduced global cocoa production, and the market is already pricing it. New York cocoa futures spiked to a multi-month high near 4,700 dollars per tonne in May before pulling back, as traders weighed dry, warm conditions in West Africa during the critical 2026-27 main crop establishment window that begins in October. Ivory Coast, Ghana, Nigeria, and Cameroon supply the bulk of the world crop, which means a single regional drought reverberates through every chocolate maker on earth.
The exposure list runs wider than cocoa. El Niño typically puts upward pressure on cocoa, palm oil, rice, sugar, and coffee, the tropical commodities most sensitive to heat and drought. Indonesia and Malaysia, which dominate palm oil, can see yields fall 5 to 10 percent depending on event severity, with the production hit showing up 6 to 12 months after the peak. India’s monsoon, which delivers roughly 70 percent of the country’s annual rainfall, weakens in El Niño years, threatening rice and sugar and frequently triggering export restrictions that ripple into global markets.
For consumer goods companies, the playbook is familiar and brutal. Newsweek reported analyst warnings of potential price shocks of 10 to 50 percent across core commodities, with retail increases possible within three to six months. Because demand for staples is inelastic, even small supply deficits produce outsized price moves. Chocolate and coffee giants such as Nestlé, Hershey, and Mondelez face the squeeze directly: either absorb margin compression or pass costs to consumers already fatigued by food inflation. Coffee-led chains like Starbucks and beverage majors like Coca-Cola, with deep sugar exposure, sit in the same crosshairs.
The Supply Chain Squeeze: Panama Canal and Shipping
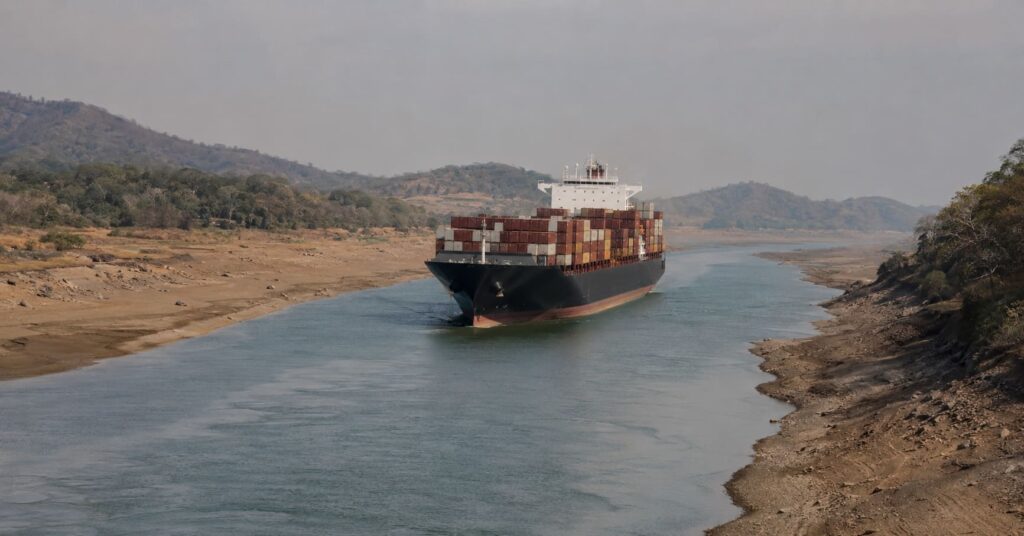
The 2023-24 El Niño delivered a preview of the logistics risk. Drought drained the Panama Canal to historic lows and forced operators to cut daily transits from 36 ships to roughly 24. LNG transits fell by as much as 73 percent. This is not a niche problem: around 40 percent of US container traffic and some 270 billion dollars in annual trade move through those locks.
When the canal constricts, ships reroute around Cape Horn, adding up to two weeks and roughly a million dollars in operating costs per voyage. The Panama Canal Authority has signaled it is already planning for operational changes in 2027, when it expects El Niño’s effect on water levels to peak, and its mitigation megaprojects, including a new reservoir and a natural gas liquids pipeline, will not be finished in time. For procurement and logistics teams, the window to lock in slot reservations and build inventory buffers is now, not when conditions harden.
Energy, Mining, and the Insurance Bill
The disruption compounds across hard assets. El Niño-driven heatwaves strain power grids precisely when hydropower reservoirs run low. India’s coal-fired generation is expected to rise around 10 percent year over year to fill the gap. Indonesia’s nickel operations, which underpin global steel, depend on hydropower and face curtailment risk, while heavy rain in Chile can block access to the mountain regions that hold much of the world’s copper.
Insurers carry the residual risk, and they are repricing it. Swiss Re analysis flags a 6 billion dollar crop protection gap in Latin America alone and projects climate-related insurance schemes to grow 50 percent by 2030. The structural shift worth watching: insurers are moving El Niño-linked flood and drought events out of the “act of God” category and into “modellable risk,” which is the language that precedes higher premiums and, in the worst cases, withdrawn coverage.
Who Actually Wins
Strong opinions require strong counterweights, and the doom narrative oversimplifies. El Niño is not uniformly negative. Southern Brazil and Argentina typically receive above-average rainfall during the warm phase, which can lift soybean and maize yields, a genuine tailwind for those agricultural exporters. Coffee supply may prove more resilient than the headlines suggest, because Brazil’s record 2026-27 crop is already being harvested and cushions the global balance. Cocoa’s near-term picture is muddied by a 2025-26 surplus, with Ivory Coast raising its delivery estimate to 2.2 million tonnes, which is currently softening prices even as the 2027 supply risk builds.
There are also direct commercial winners. LNG shippers and energy traders who re-commit to Panama transit can lock in favorable long-term pricing, and the canal’s 8.5 billion dollar infrastructure program is a multi-year opportunity for contractors and capital. Parametric insurance providers are entering a structural growth market. The lesson is that El Niño redistributes value as much as it destroys it, and the businesses that map their specific regional and crop exposure will see the trades that a blanket “everything goes up” thesis misses.
What Businesses Should Do Now
The action items are unglamorous and time-sensitive. Hedge forward commodity exposure for Q4 2026 and 2027 deliveries before the supply hit physically arrives, because markets price the news fast while the production effect builds slowly. Lock in shipping slots and pre-position inventory ahead of any Panama constriction. Stress-test energy and water dependencies in tropical operations. Review insurance coverage now, while events are still “modellable” rather than excluded. And treat NOAA’s monthly ENSO updates from now through September as the single most important leading indicator on the calendar.
The Business Model Analyst Take
The trap with a story like this is letting “Super El Niño” do the thinking for you. It is a media label, not a forecast, and treating it as a guaranteed catastrophe is as lazy as ignoring it. The disciplined read is narrower and more useful: a very strong El Niño is now a high-probability event, its damage is concentrated in identifiable sectors and regions, and the peer-reviewed cost evidence says the economic drag outlasts the weather by years, not weeks.
The companies that come out ahead will not be the ones that panic over a buzzword. They will be the ones that already know their exact cocoa, palm oil, shipping-lane, and energy exposure, and have hedged the tail while their competitors are still reading the same headlines. In a warming world, ENSO volatility is no longer a once-a-decade surprise to be weathered. It is a recurring, modellable line item, and the firms that build it into their planning now will treat 2026-27 as a managed cost rather than a crisis.