
A debt product that was supposed to be paid off decades ago is now reaching people in their 60s and 70s, and the biggest change to federal student lending in a generation takes effect July 1, 2026.
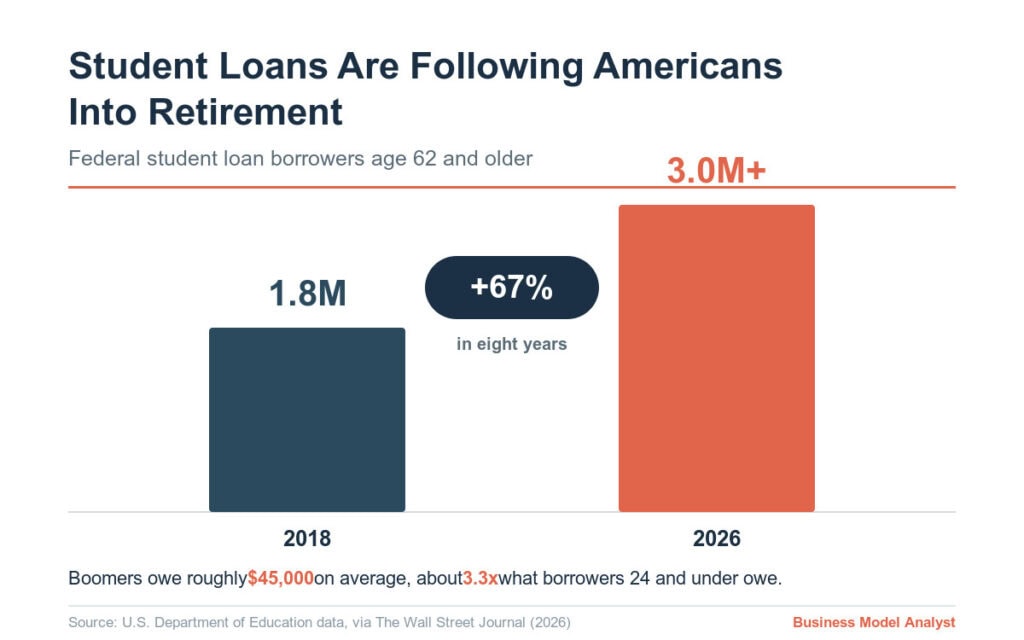
More than three million Americans age 62 and older now owe federal student loans, up from 1.8 million in 2018, according to Education Department figures reported by The Wall Street Journal. That is a 67 percent jump in eight years, and it runs against the intuition that student debt is a young person’s problem. Baby boomers with federal loans owe roughly $45,000 on average, more than three times the $13,800 carried by borrowers 24 and under.
The timing matters. On July 1, the repayment system these borrowers depend on is being rebuilt under the Working Families Tax Cuts Act, the law widely known as the One Big Beautiful Bill. For older borrowers living on fixed incomes, the change is not abstract. It resets monthly payments, closes the plan that was protecting many of them, and arrives as the government restarts collections it had frozen since 2020.
Why the oldest borrowers owe the most
The pattern looks strange until you trace where the debt comes from. Older borrowers are heavy on two products that compound quietly. The first is graduate-school debt, often taken on in mid-career for a degree in nursing, social work, or law. The second is Parent PLUS loans, borrowed on behalf of children, which carry higher interest rates and fewer repayment options than student loans do.
Both share the same trap: negative amortization. When a borrower moves onto a lower monthly payment to ease cash flow, the payment can fall below the monthly interest charge. The unpaid interest gets added to the balance, and the loan grows even as the borrower keeps paying. The Journal documented one couple whose original $114,000 in graduate debt has ballooned toward half a million dollars, and a borrower who has paid $91,000 against a Parent PLUS loan yet still owes $51,000. These are not deadbeats. They are people who made payments for decades and watched the number climb anyway.
That dynamic is exactly what the new system claims to fix, and where the business mechanics get interesting.
What actually changes on July 1
The old menu of repayment plans collapses into two new ones for anyone taking a federal loan on or after July 1. The headline feature, and the one that matters most for retirement-age borrowers, is that the new income-driven plan finally stops balances from growing.
| Plan | Who it is for | How it works | The catch |
|---|---|---|---|
| Repayment Assistance Plan (RAP) | New income-driven option | Payments of 1 to 10 percent of adjusted gross income, $10 minimum, minus $50 per dependent. Waives unpaid interest and adds a $50 principal match so balances always fall | Forgiveness only after 30 years, not 20 or 25. Not available for Parent PLUS loans |
| Tiered Standard | New fixed-payment option | Fixed terms of 10, 15, 20, or 25 years based on total balance | Higher balances stretch longest, meaning more interest over time |
| SAVE plan | 7.5 million current enrollees | Ends. Borrowers get a 90-day notice to pick a legal plan | Miss the window and you are auto-enrolled in a standard plan, usually at a higher payment |
A few details land hardest on the people this story is about. RAP will not accept Parent PLUS loans, so parents who borrowed for their children lose a path to income-driven relief unless they consolidate before July 1. New Parent PLUS borrowing is also capped at $20,000 a year per student rather than the full cost of attendance, and Grad PLUS is being phased out for new borrowers entirely. Borrowers on SAVE, which capped some payments near $100 a month, now face recalculated bills. One borrower profiled by the Journal estimated her payment could jump from about $100 to roughly $900.
There is one sweetener: borrowers enrolled in auto pay become eligible for a 1 percent interest rate reduction starting July 1.
The collections engine restarts
Here is the part that turns a repayment story into a balance-sheet story. The federal government holds roughly $1.6 trillion in student loans and is the largest consumer lender in the country. For five years it ran that book like a frozen asset, pausing collections. That era is ending.
More than five million borrowers were in default as of mid-2026, and the Education Department has warned that figure could approach ten million, which would put nearly a quarter of the entire portfolio in default. To recover that money, the government is restarting the Treasury Offset Program, which garnishes wages, tax refunds, and Social Security checks.
Older borrowers are the most exposed. The Consumer Financial Protection Bureau estimates that the number of Social Security recipients facing forced collection grew more than 3,000 percent in under two decades, and roughly 452,000 beneficiaries are currently in default and at risk of having up to 15 percent of their monthly benefit seized. For someone whose check is their primary income, that is the difference between covering medicine and skipping it.
Frequently Asked Questions
What changes for student loans on July 1, 2026?
Two new federal repayment plans launch: the income-driven Repayment Assistance Plan (RAP) and the Tiered Standard plan. The SAVE plan ends, new Parent PLUS borrowing is capped at $20,000 a year per student, Grad PLUS is phased out for new borrowers, and borrowers enrolled in auto pay qualify for a 1 percent interest rate reduction.
What is the Repayment Assistance Plan (RAP)?
RAP is the new income-driven plan for federal loans taken on or after July 1, 2026. Monthly payments run from 1 to 10 percent of adjusted gross income, with a $10 minimum and a $50 reduction per dependent. It waives unpaid interest and adds a $50 principal match so balances always fall, with forgiveness after 30 years of payments.
Are Parent PLUS loans eligible for RAP?
No. Parent PLUS loans cannot enroll in RAP. Parents who want an income-driven option generally need to consolidate their Parent PLUS loans before July 1, 2026, and enroll in a qualifying plan first. New Parent PLUS borrowing is also capped at $20,000 per year per student.
Is the SAVE plan ending?
Yes. The SAVE plan ended after a court-approved settlement, and about 7.5 million enrolled borrowers will receive a 90-day notice to switch to a legal repayment plan. Borrowers who miss that window are auto-enrolled in a standard plan, which usually carries a higher monthly payment.
Can the government take Social Security for defaulted student loans?
Yes. Through the Treasury Offset Program, the government can withhold up to 15 percent of a monthly Social Security benefit to collect on a defaulted federal student loan. The Consumer Financial Protection Bureau estimates about 452,000 beneficiaries are currently in default and exposed once collections resume.
Are student loans forgiven at retirement age?
No. Federal student loans are not forgiven based on age or retirement. They stay due until paid off, discharged through a qualifying program, or forgiven at the end of the plan’s repayment term, which is 30 years under RAP. Unpaid balances can follow borrowers into retirement and reduce Social Security benefits.
The Business Model Analyst Take
Strip away the human-interest framing and what July 1 really represents is a lender restructuring a distressed loan book. The federal student loan program is pivoting from the forbearance-and-forgiveness posture of the prior administration to a repayment-and-recovery posture, and the unit economics are being rewritten to match.
Three shifts are worth watching. First, RAP’s interest waiver and principal match kill negative amortization for the borrowers who enroll, which is genuinely better product design, but it trades a faster payoff for a longer 30-year forgiveness clock. The government collects more total interest from disciplined payers while marketing the plan as relief. Both things are true at once.
Second, capping Parent PLUS and phasing out Grad PLUS pulls the federal government out of the high-balance graduate and parent lending segments. That volume does not vanish. It migrates to private lenders, the Sallie Mae and SoFi side of the market, which now inherits demand the government is deliberately shedding. The losers are graduate and professional students who may turn to costlier private debt with weaker protections.
Third, restarting collections converts a frozen receivable into cash flow, and it reactivates the asset-recovery industry that spun out of the old Sallie Mae and Navient world. A defaulted loan is not a dead loan. It is an input to a collections business, and that business is coming back online against a borrower base that is older, sicker, and on fixed income than at any point in the program’s history.
The retirement angle is not a sad footnote to this overhaul. It is the leading edge of it. The fastest-growing segment of the federal portfolio is the segment least able to absorb a payment shock, and the new rules and the restarted collections engine are arriving on the same day.