The biggest overhaul of federal student loans in a generation went live on July 1, 2026. If you are one of the more than 42 million Americans carrying federal student debt, the rules you planned your repayment around have changed, and some of the forgiveness paths you were counting on no longer work the way they used to.
Here is what actually changed, what survived, and what to do about it.
What Changed on July 1
Most of the new system traces back to a single law: the One Big Beautiful Bill Act (OBBBA), also branded the Working Families Tax Cuts Act, which President Trump signed on July 4, 2025. The U.S. Department of Education spent the following year in negotiated rulemaking and finalized the package in spring 2026. The bulk of it took effect July 1, 2026, with a few pieces phasing in through 2028.
Three things happened at once. A new income-driven repayment plan called RAP launched. The Biden-era SAVE plan officially ended after losing in court. And a new rule narrowing who qualifies for Public Service Loan Forgiveness went into effect. Each one hits a different group of borrowers, which is exactly why the moment feels so confusing.
The New Plan: RAP
The headline change is the Repayment Assistance Plan, or RAP. For anyone who takes out a new federal Direct Loan on or after July 1, 2026, RAP and a revised Tiered Standard plan are now the only two repayment options that exist. Everything else is gone for new borrowers.
RAP works differently from the plans it replaces. Instead of basing payments on discretionary income, it charges a flat percentage of your full adjusted gross income (AGI), scaling from 1% to 10% across income bands. Borrowers earning $10,000 or less pay a flat $10 minimum. Each dependent knocks $50 off the monthly bill, down to that same $10 floor.
The chart below shows the base rate at each income level.
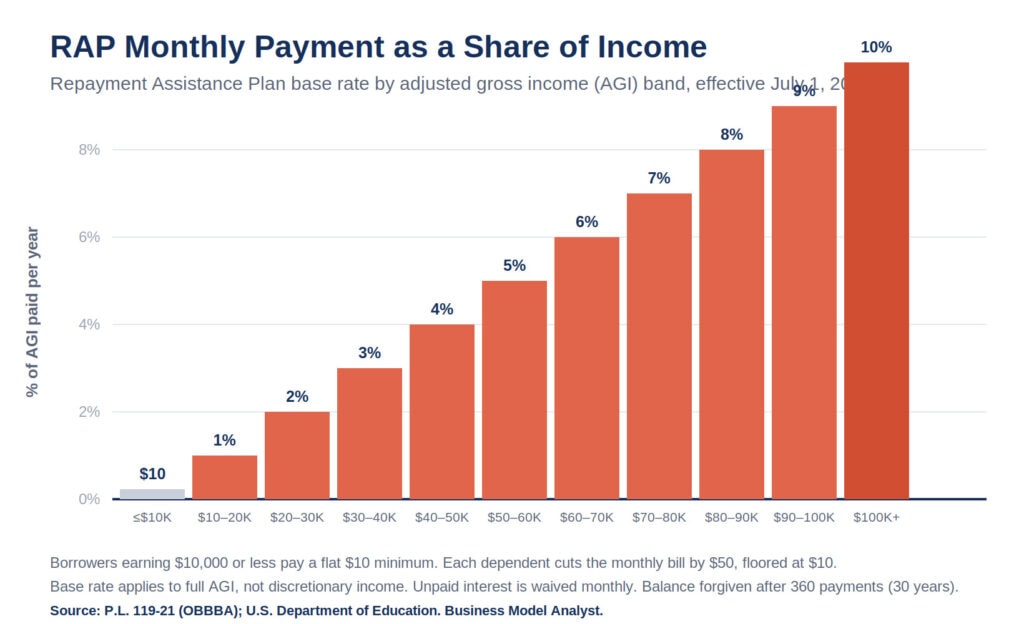
RAP has two features borrowers will actually like. If your payment does not cover the month’s interest, the government waives the difference, so your balance cannot balloon. And if your payment chips away less than $50 of principal, the government tops it up to $50, guaranteeing your balance moves down every on-time month.
The catch is the timeline. RAP forgives any remaining balance after 360 payments, which is 30 years. That is longer than the 20 or 25 years most older plans offered, and once you start RAP you cannot switch back to a Standard plan.
The Plan That Died: SAVE
The most generous plan of the last few years is now gone. A federal court vacated the SAVE plan on March 10, 2026, ending the Biden administration’s signature income-driven option.
If you are one of the roughly 7.5 million borrowers still in SAVE, this affects you directly. Servicers began sending notices on July 1, and each notice starts a clock of at least 90 days to pick a legal plan. Miss the window and the Department can move you into a plan built to fully repay your balance, which can shrink or erase what would have been forgiven. The payments you already made under SAVE are generally expected to still count toward your income-driven forgiveness total.
What Still Works: IBR
Income-Based Repayment survived, and for many existing borrowers it is now the most legally solid path to forgiveness. IBR stays available for anyone whose loans were disbursed before July 1, 2026. It keeps its 20-year or 25-year forgiveness timeline, and the Department waived the old partial-financial-hardship requirement, so more people can enroll regardless of income.
One wrinkle: the Department has temporarily paused the processing of IBR forgiveness discharges while it recalculates payment counts. Enrollment and payment counting continue, so you keep earning credit. It only affects when final discharges go out.
PAYE and ICR are on the way out and will sunset by July 1, 2028. If you are on either one, or on the defunct SAVE plan, you will need to move to IBR or RAP before that deadline or your servicer will do it for you.
Public Service Loan Forgiveness: Intact, but Narrower
Public Service Loan Forgiveness (PSLF) is not going away. It is written into the Higher Education Act, and only Congress can repeal it. The core deal still stands: 120 qualifying payments over 10 years of full-time public service, and the remaining balance is forgiven tax-free. RAP counts as a qualifying plan for PSLF, and payments made under it count toward the 120.
What changed is who counts as a qualifying employer. A new rule effective July 1, 2026 lets the Secretary of Education disqualify employers found to have a “substantial illegal purpose.” The Department estimates fewer than 10 employers a year will be affected, and payments made before any disqualification stay protected. The rule is being challenged in court by a coalition of states, cities, and nonprofits, so expect this piece to keep moving.
The practical takeaway for public servants: file your employment certification now to lock in the credit you have already earned, and keep thorough records.
The Tax Bomb Nobody Mentions
Here is the change with the biggest dollar impact and the least press. The American Rescue Plan provision that made forgiven student debt tax-free at the federal level expired on December 31, 2025.
That means income-driven forgiveness received in 2026 or later is generally taxable as ordinary income, unless you qualify for an IRS insolvency exclusion. On a large forgiven balance, that tax bill can run into five figures. PSLF forgiveness stays permanently tax-free, and so do death and disability discharges. If you are close to an IDR forgiveness date, the timing math suddenly matters a lot.
What Is Closed for Good
If you are still waiting on “Biden’s student loan forgiveness,” the one-time relief of up to $10,000 (or $20,000 for Pell recipients), that application is closed and is not coming back. Grad PLUS loans are also eliminated for new graduate and professional borrowers after July 1, 2026, and new federal borrowing carries tighter caps. Parent PLUS borrowers lose their pathway to PSLF and to RAP unless they consolidate under specific deadlines.
What Borrowers Should Do Now
The single most useful move is to find out which plan you are actually on, because your next step depends entirely on that. SAVE enrollees should watch for the servicer notice and treat the 90-day clock as real. Borrowers on PAYE, ICR, or SAVE need to choose IBR or RAP before the July 1, 2028 cutoff. Public servants should file a PSLF certification now rather than waiting for a prompt. And anyone approaching an IDR forgiveness date should run the tax math before assuming the forgiven amount is free.
The Department’s Loan Simulator now includes RAP, which makes side-by-side comparisons easy. Run your own numbers before committing, because RAP is a one-way door.
Frequently Asked Questions
Is student loan forgiveness still available in 2026 ?
Yes. PSLF, IBR forgiveness, borrower defense, and death and disability discharges all remain open. What ended is the one-time Biden relief of up to $10,000 to $20,000 and the SAVE plan. Forgiveness did not disappear, but the paths and timelines changed.
Did the SAVE plan really end?
Yes. A federal court vacated SAVE on March 10, 2026. The roughly 7.5 million borrowers still enrolled are being moved off it, with servicer notices starting July 1, 2026 and a window of at least 90 days to choose a new plan.
What is RAP and who has to use it?
RAP is the Repayment Assistance Plan, the new income-driven option launched July 1, 2026. Anyone taking out a new federal Direct Loan on or after that date can only use RAP or the Tiered Standard plan. Existing borrowers can switch to RAP but are not forced to.
Is RAP better than IBR?
It depends on your income and family size. RAP waives unpaid interest and guarantees principal reduction, which helps low balances get paid faster. But it uses full AGI instead of discretionary income and forgives only after 30 years, so higher earners and larger families often pay more and wait longer than under IBR. Run both in the Loan Simulator before choosing, because RAP is a one-way door
Is forgiven student debt taxable in 2026?
For income-driven forgiveness, generally yes. The federal tax exclusion expired on December 31, 2025, so IDR forgiveness in 2026 or later is treated as taxable income unless you qualify for an IRS insolvency exclusion. PSLF, death, and disability discharges stay tax-free.
Is PSLF going away?
No. PSLF is written into federal law and only Congress can end it. The 120-payment, 10-year structure is unchanged. A new rule can disqualify a small number of employers deemed to have a “substantial illegal purpose,” and that rule is being challenged in court.
What happens if I do nothing?
This is the expensive choice. If you ignore a SAVE transition notice, your servicer can move you into a plan built to fully repay your balance, which can shrink or erase forgiveness you were on track for. Borrowers on PAYE or ICR who take no action before July 1, 2028 get auto-enrolled too.
The Business Model Analyst Take
The framing battle here is more revealing than the mechanics. The administration is selling this as simplification, and on one axis it is: five confusing plans collapse into two, and the interest-waiver and principal-match features genuinely protect borrowers from watching balances grow. But simplification and generosity are not the same thing. RAP’s 30-year clock and the return of taxable forgiveness quietly shift real cost back onto borrowers, especially higher earners and professional-degree holders who now face a longer, more expensive road to relief.
The smart read is to stop thinking about forgiveness as a promise and start treating it as a moving target with deadlines attached. The borrowers who lose the most in this transition will not be the ones who chose the wrong plan. They will be the ones who did nothing and got auto-enrolled. In a system this fluid, inertia is the expensive option.
This article is for informational purposes and is not financial or legal advice. Confirm your specific situation with your loan servicer or a qualified advisor before acting.