
The largest captive agent network in American insurance is being rebuilt while it carries the load
State Farm’s strengths and weaknesses trace back to one asset: 19,200 exclusive agent offices. That network sits on the most valuable customer pool in US personal lines, and it costs about the same share of premium as Progressive’s national advertising does. It also cannot be switched off in a bad quarter. That is why Jon Farney spent 2026 rewriting the contract underneath all 19,000 agents while his largest competitor turned the advertising dial up instead. The SWOT reduces to a single question: can State Farm make an installed cost base behave like a variable one without breaking the thing it installed?
A SWOT analysis sorts a company’s position into four buckets. Strengths and weaknesses are internal, meaning management controls them. Opportunities and threats are external, meaning management can only respond. The framework is useful when a business has assets that cut both ways, and State Farm is close to a pure case: the agent force, the mutual balance sheet and the homeowners book each appear on two sides of the ledger.
State Farm at a glance
| Item | Figure |
|---|---|
| Founded | 1922, Bloomington, Illinois |
| Ownership structure | Mutual, 14 property-casualty companies plus 2 life companies |
| CEO | Jon Farney, president since January 2024, CEO since June 1, 2024 |
| 2025 total revenue | $132.3 billion |
| 2025 net income | $12.9 billion |
| Net worth (State Farm Mutual) | $170.0 billion, up from $145.2 billion |
| P&C earned premium | $111.6 billion |
| P&C underwriting result | Gain of $1.5 billion, BMA-computed combined ratio 98.7 |
| Auto | $71.3 billion earned, $4.6 billion gain, combined ratio 93.5 |
| Home, CMP and other | $39.2 billion earned, $3.1 billion loss, combined ratio 107.7 |
| Distribution | 19,200+ agent offices, 62,000+ employees |
| Scale | 96 million+ policies and accounts |
| 2025 advertising expense | $1.139 billion |
| AM Best financial strength rating | A+ (Superior), downgraded from A++ on November 14, 2025 |
| US private passenger auto share | 18.64% on NAIC data year 2025 |
Figures are from State Farm’s 2025 results release of February 26, 2026, except advertising (NAIC filing reported by Popular Information), the AM Best action and the NAIC share data.
The SWOT matrix
| Strengths | Weaknesses |
|---|---|
| 19,200 exclusive offices holding the bundled-homeowner segment rivals are trying to buy their way into | Home book lost $3.1 billion at a 107.7 combined ratio in a year with no major hurricane landfall |
| $170 billion of net worth with no shareholder claim on it; AM Best still grades balance sheet strength “strongest” | Roughly 72% of group surplus sits in common stock, so the capital base moves with the equity market |
| Expense ratio parity with direct-model rivals despite carrying an agent force | AM Best cut the rating to A+ in November 2025 and moved operating performance from strong to adequate |
| Auto returned to a $4.6 billion underwriting gain at a 93.5 combined ratio | Approved rates since 2021 trail industry averages by 14 points on home |
| Life in force of $1.22 trillion and $2.1 billion of net income | HiRoad, the direct-channel answer, has reached two states in nine years |
| Opportunities | Threats |
|---|---|
| OpenAI Frontier and the Navi agent assistant across 19,200 offices | Progressive took an estimated 86% of top-10 auto premium growth in 2025 |
| Contract reset shifts agent pay toward new business for the first time | Agent attrition through the 2026-2028 signing window and the STEP exit program |
| Tort-reform states such as Florida, where State Farm auto rates fell about 20% since 2024 | California enforcement action alleging 432 claims-handling violations |
| Drive Safe & Save telematics feeding risk-based pricing | Convective storm and hail severity across the Midwest |
| Defending the segment Progressive says is worth $20 billion to enter | A softening auto market in which shopping frequency rises |
Strengths
The agent network owns the segment everyone else is trying to buy
Progressive sized the prize in its own second-quarter 2026 investor materials. Captive agents control $120.7 billion of premium from consistently insured households that bundle home and auto, against $78.1 billion held by independent agents and $30.1 billion sold direct. Progressive’s share of that segment runs near 3.9%. Pat Callahan put a price on closing the gap in the direct channel alone: roughly $20 billion against a homeowners market of $160 billion to $170 billion.
State Farm is the largest captive network in the country. The $120.7 billion pool Progressive describes as its largest unpenetrated opportunity is, to a meaningful degree, State Farm’s existing book. Our Progressive SWOT analysis runs that gap from the attacker’s side. From the defender’s side the reading flips: State Farm already holds the position, and the competitor with the best rating engine in the industry has spent four years assembling the property products, the quoting platform and the agency appointments needed to come after it.
Nineteen thousand offices cost the same as national television
The standard criticism of State Farm holds that a captive agent force is an expensive way to sell insurance compared with a direct model. The arithmetic does not support it.
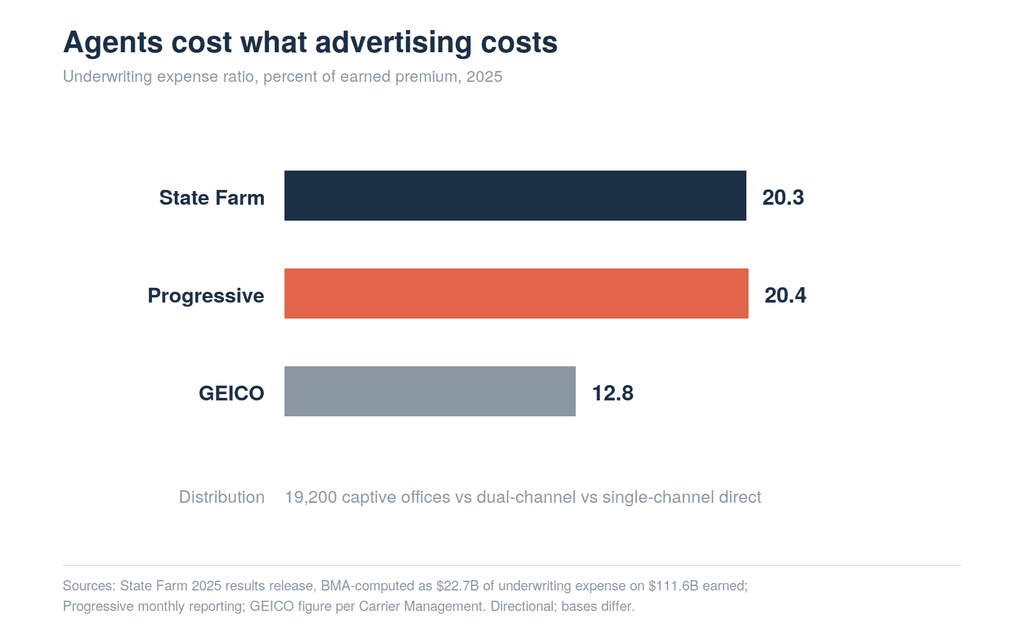
State Farm’s 2025 disclosure gives underwriting expenses of $14.1 billion on the auto book and $8.6 billion on home, commercial multiperil and other lines. Against $111.6 billion of earned premium, that is an expense ratio of 20.3%. Progressive’s companywide expense ratio ran in the 20.3 to 20.4 range through 2025 on its own monthly reporting. Two companies with opposite distribution architectures land within a fraction of a point of each other.
The bases are not identical, and the comparison should be read as directional rather than exact. The direction is clear enough. Agent commissions and office support consume about the same slice of premium at State Farm that policy acquisition and advertising consume at Progressive. GEICO is the outlier, running an expense ratio near 12.8, and GEICO is the model that both of the larger carriers have declined to copy.
A balance sheet with no claimant
State Farm Mutual’s net worth reached $170.0 billion at the end of 2025, up $24.8 billion in a single year. No shareholder can ask for any of it. AM Best kept its balance sheet strength assessment at “strongest” even while cutting the group rating, citing the strongest level of risk-adjusted capitalization on its BCAR measure.
That capital is what lets State Farm stay in lines and states where thinner rivals would price out or leave. We walked through the mechanics of how the mutual structure converts surplus into staying power in the Progressive comparison piece; the short version is that a company answering to policyholders can carry an unprofitable line for years in a way a public carrier cannot explain to the market.
The auto book worked in 2025
Auto earned $71.3 billion and produced a $4.6 billion underwriting gain at a 93.5 combined ratio, against a $2.7 billion loss and a 104.0 combined ratio the year before. Life added $2.1 billion of net income on $1.22 trillion of insurance in force, with record new policy volume of $130 billion and record policyholder dividends of $924 million. The parts of State Farm that are not exposed to weather performed.
Weaknesses
The home book lost money in the calmest year available
State Farm’s home, commercial multiperil and other lines earned $39.2 billion and lost $3.1 billion at a 107.7 combined ratio. The two-year deficit reaches $6.7 billion. Catastrophe claims across the group came to about $15 billion, roughly a third of it from the January 2025 Southern California wildfires, with Midwest hail supplying much of the remainder.
The 2025 Atlantic season produced no major US hurricane landfall, the first such year in a decade. State Farm’s homeowners book lost three billion dollars anyway. Break-even on that line now depends on a quiet hurricane season rather than being helped by one.
The surplus is a stock portfolio wearing an insurance company
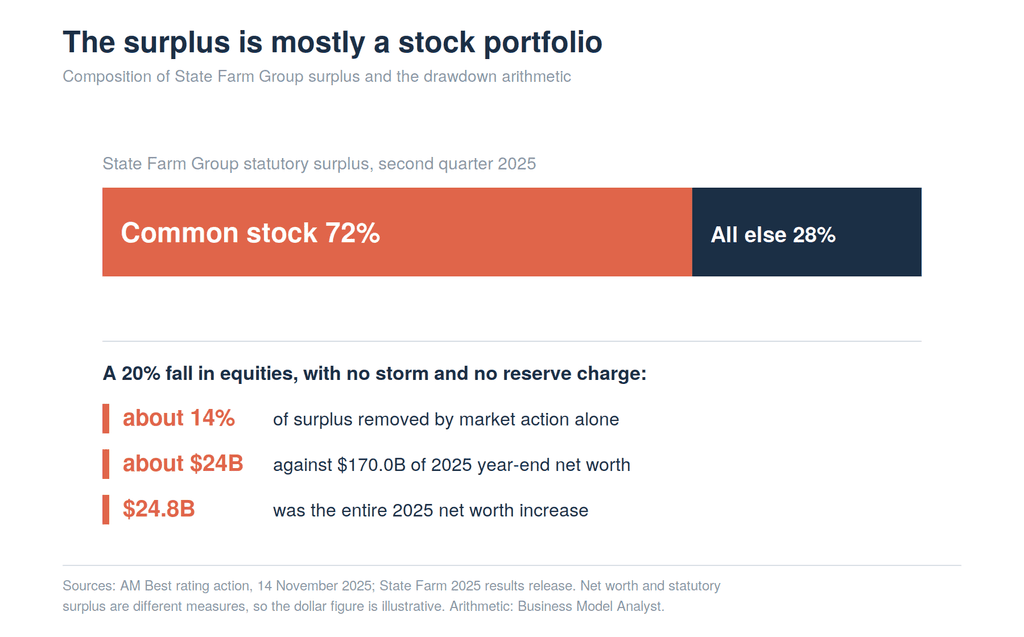
AM Best’s November 2025 rating action includes a number that no competing analysis of State Farm mentions: common stock made up approximately 72% of group surplus at the second quarter of 2025. State Farm’s own results release attributes the $24.8 billion net worth increase “in large part” to appreciation in the property-casualty companies’ unaffiliated stock portfolios.
Run the arithmetic. At a 72% equity weighting, a 20% drawdown in equities removes roughly 14% of surplus with no storm, no wildfire and no reserve strengthening required. Applied against $170 billion of net worth, that is on the order of $24 billion, close to the entire 2025 gain reversed by market action alone. Net worth and statutory surplus are not the same measure, so treat the dollar figure as illustrative and the ratio as the point. The capital that funds the retention machine is priced by the equity market, not by underwriting.
AM Best moved the rating down
On November 14, 2025, AM Best downgraded the financial strength rating of State Farm Mutual, State Farm Fire and Casualty and State Farm County Mutual of Texas to A+ (Superior) from A++ (Superior), and the long-term issuer credit ratings to “aa” from “aa+”. The same action hit the State Farm Life companies. The outlook improved to stable from negative.
The stated reason was a revision in the operating performance assessment to adequate from strong, reflecting elevated loss ratios in private passenger auto and homeowners, a challenging regulatory environment, and weather losses from hurricanes, convective storms and wildfires. AM Best also flagged trends of adverse reserve development.
Most published State Farm profiles still cite an A++ rating. That has not been accurate since November 2025.
The company under-raised the market
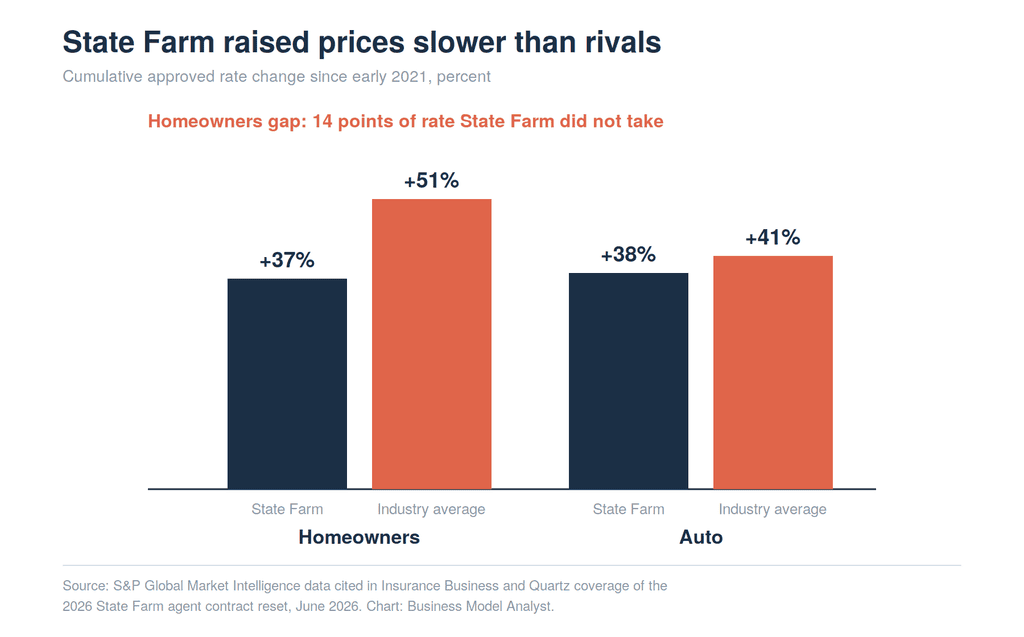
S&P Global data cited in trade coverage puts State Farm’s approved rate increases since early 2021 at 37% for homeowners and 38% for auto, against industry averages of 51% and 41%. State Farm left 14 points of homeowners rate on the table relative to its peers and 3 points on auto.
That gap explains the retention and the underwriting losses in the same breath. Customers stayed because their renewals climbed less than the market’s. The book lost money because the renewals climbed less than the losses did.
There is no direct channel
State Farm launched HiRoad Assurance in Rhode Island in 2017, a state where it keeps no captive agents, as a smartphone-native usage-based auto product. HiRoad reached its second state, Arizona, in 2021. It is still in two states. AM Best rates it A (Excellent) and assesses its operating performance as marginal.
Nine years and two states. Progressive’s direct book wrote $21.2 billion of net premium in the first half of 2026 alone; the channel structure behind that number is covered in our Progressive business model breakdown. State Farm has no non-agent distribution operating at scale, which is the reason the company is rewriting agent contracts rather than building a parallel channel. There is no parallel channel to build on.
Opportunities
The AI layer is aimed at agent throughput, not agent replacement
Farney introduced Next Gen Good Neighbor on May 6, 2026, built around faster claims, prices matched to risk and data-driven underwriting. State Farm joined OpenAI’s Frontier platform as a launch participant in February 2026, under chief digital information officer Joe Park. The visible pieces are Navi, an agent-facing assistant rolling out across the 19,200 offices; a virtual assistant piloting first notice of loss; expanded Drive Safe & Save telematics feeding renewal pricing; and consolidation onto a single insurance platform.
Read it against the expense-ratio finding above. If State Farm’s constraint is not cost but quote supply, and an agent office can handle more households per year with an assistant that surfaces coverage gaps before the conversation starts, then the network becomes a demand engine rather than a fixed overhead. That is the bull case for the whole program, and it does not require a single agent to be removed.
The contract reset is a lever on new business that has never been pulled
Farney told roughly 19,000 agents at a Las Vegas convention that their contracts were being replaced with one standardized agreement. Commissions shift from trailing renewals toward new business. Missing sales benchmarks in consecutive years reduces commission rates. Agents sign by 2028 or take a buyout of $50,000 to $300,000 at State Farm’s discretion.
Strip out the labor conflict and the design intent is legible. State Farm has paid its distribution to keep policies for a century. It is now paying to write them. In a market where households shop more often, a compensation system that rewards retention above acquisition produces a network optimized for the wrong decade.
Florida and the tort-reform states
State Farm’s Randy Schell has pointed to Florida auto rates falling nearly 20% since 2024 following litigation reform, and has contrasted it with states where regulatory structures slow the ability to match price to risk. Florida is a large market where the loss environment improved for structural reasons rather than cyclical ones. Progressive is already harvesting it, and recorded a $1.2 billion policyholder credit in 2025 because its Florida auto profits exceeded the statutory limit.
California stops being an open wound
The July 23, 2026 commissioner order settled the State Farm General rate dispute: homeowners holds at +17.0%, condominium drops to about 5.8%, rental dwelling to 32.8%, with refunds carrying 10% interest. Capital triggers in the order require a new rate review if premium-to-surplus reaches 2:1 and a 2.5% discount at 1.5:1. The affiliate structure and the $400 million surplus note that made this possible sit outside this analysis, but the practical effect is that the largest single overhang on the brand now has a defined shape.
Threats
Progressive is converting stored margin into permanent share
Tricia Griffith told investors that Progressive’s private passenger auto written premium growth of $8.9 billion in 2025 represented 86% of the $10.4 billion recorded by the top ten carriers combined. Progressive grew personal vehicle net premiums 11.6% over the trailing year to March 2026 while State Farm’s slipped 0.1%. On S&P Global Market Intelligence’s estimate, Progressive’s trailing twelve-month private auto direct premiums reached about $70.2 billion against State Farm’s $68.7 billion, ending a run at number one that dated to 1942.
Carry the caveat. That estimate includes modeled results for two New Jersey-domiciled Progressive subsidiaries that file no public quarterly statements, and S&P notes that publicly available data still shows State Farm slightly ahead. On published NAIC figures for data year 2025, State Farm holds 18.64% and $69.164 billion against Progressive’s 18.60% and $69.006 billion, a gap of $158 million on a $371 billion market. The overtake is a well-supported estimate rather than a settled fact.
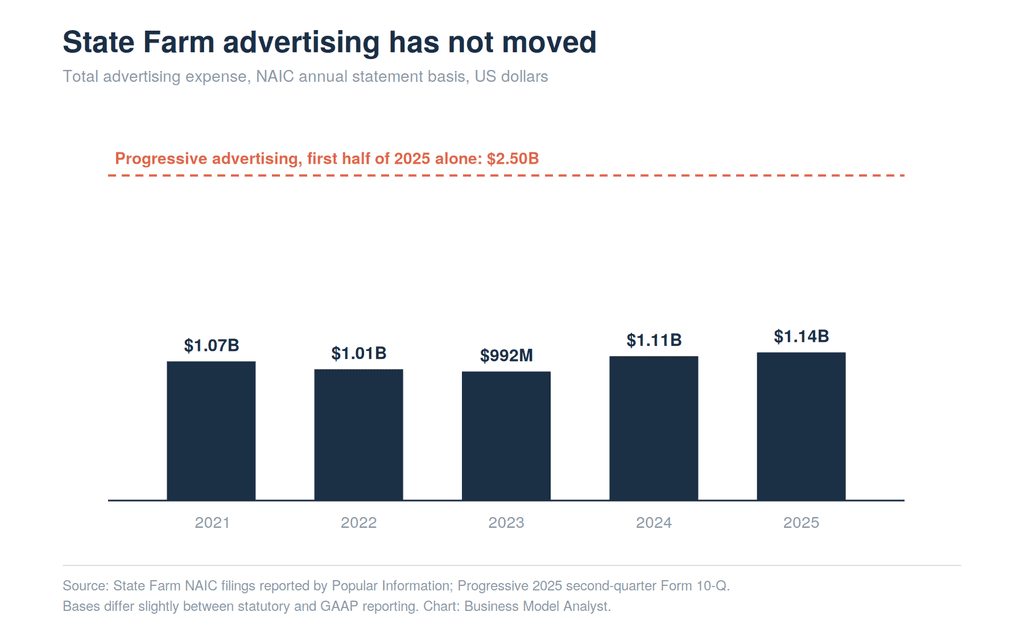
Underneath the ranking sits the mechanism. Progressive spent $2.5 billion on advertising in the first half of 2025 alone, more than twice what State Farm spent across all of 2025. State Farm’s advertising has been flat in nominal dollars for five years: $1.07 billion in 2021, $1.01 billion in 2022, $992 million in 2023, $1.11 billion in 2024, $1.139 billion in 2025. Adjusted for inflation, the budget shrank.
The asymmetry matters because of what each company can do with the money. Progressive cut advertising roughly 30% in 2023 and its combined ratio improved that year. State Farm cannot cut agent compensation by 30% and keep its distribution. Advertising is a valve. An agent network is an installation. Every strategic move State Farm made in 2026 is an attempt to fit a valve to something that was poured as concrete.
The agent force may not sign
Health coverage for agents and spouses ends December 31, 2026, at a cost two sources put near $585 per person per month. Medicare supplement support for retired agents, $2,400 per person annually, ends at the same time. The Annual Investment Payment Program was partially restored in a June 12, 2026 video from chief agency officer Kristyn Cook, with payments continuing through 2028 before becoming performance-linked from 2029. The STEP exit program closed applications on September 30, 2026, with payment reserved for agents who stay through the fourth quarter of 2027.
Trade coverage of the Wall Street Journal reporting suggests total earnings could fall by up to 40% for long-tenured agents whose books lean on home and auto renewals. One former agent cited a 35% to 40% base commission cut; State Farm disputed that figure as speculation, and it should be carried with that qualifier attached. The risk is not the arithmetic. The risk is that a network built on twenty-year relationships loses its most tenured operators in the window between now and 2028, and every departing agent’s book gets reassigned to someone the customer has never met.
The California enforcement action
On May 4, 2026 the California Department of Insurance filed an Accusation and Order to Show Cause against State Farm General alleging 432 violations of the Unfair Insurance Claims Practices Act, 398 from a market conduct exam and 34 from complaints, across a review of 220 claims. The statutory cap of $5,000 per violation, or $10,000 if willful, puts the financial ceiling near $4.3 million. Against $170 billion of net worth that is a rounding error.
The exposure is reputational and regulatory. State Farm spent $1.139 billion in 2025 telling the country it shows up when things go wrong. A public hearing on a 52% violation rate in wildfire claims handling is the most expensive possible contradiction of that message, and it costs the department nothing to hold.
Weather is not reverting to a friendlier mean
The $15 billion catastrophe bill in 2025 arrived without a major hurricane landfall. Convective storms and hail across the Midwest are producing record event counts, and repair costs have climbed with them. State Farm has already reshaped its footprint in response: between 2014 and 2024 it cut homeowners exposure in Texas by close to half while the broader market expanded, even as it doubled homeowners premium in two other states that competitors were exiting. Managing that map is now a permanent function rather than a cycle response.
The market is softening, which favors the shopper
J.D. Power’s 2026 US Auto Insurance Study found overall satisfaction flat at 644 on a 1,000-point scale, with price satisfaction up 3 points as fewer customers reported insurer-initiated increases. A softening market means more carriers quoting, more households shopping and lower switching costs. Progressive’s own disclosure shows the average number of carriers returning a quote on comparative raters up more than 30% since early 2024. Every one of those conditions works against a carrier whose economics depend on households that do not shop.
What the SWOT adds up to
State Farm is not losing because it chose a worse distribution model. The expense ratio comparison rules that out. It is losing ground in auto because its distribution produces quotes at agent speed while Progressive produces them at media speed, and because it declined to raise prices as fast as the industry did, which cost it 14 points of homeowners rate and five years of underwriting results.
Both of those are choices a mutual can make and a public company cannot. The $170 billion balance sheet absorbed them. What the balance sheet cannot absorb is a distribution network that stops producing, which is the risk Farney accepted when he opened every agent contract at once. The AI program and the compensation reset are the same bet from two directions: raise the output of an installed network fast enough that the company never has to answer whether it needed a direct channel.
The bear case is that the reset costs State Farm its most tenured agents during the same window in which Progressive is spending $2.5 billion a half-year to reach their customers, and that a 72% equity weighting in surplus turns the next market correction into a capital event on top of it.
Frequently asked questions
Is State Farm still the largest auto insurer in the United States? On the most recent published NAIC data, for data year 2025, yes, but by very little: State Farm holds 18.64% of private passenger auto premium against Progressive’s 18.60%, a gap of about $158 million on a $371 billion market. S&P Global Market Intelligence estimates that Progressive passed State Farm on a trailing twelve-month basis through March 31, 2026, with roughly $70.2 billion against $68.7 billion. That estimate models two New Jersey-domiciled Progressive subsidiaries that file no public quarterly statements, and S&P notes that public data still shows State Farm slightly ahead.
What is State Farm’s biggest strength? The 19,200 exclusive agent offices, and specifically their hold on households that bundle home and auto. Progressive’s own investor materials put $120.7 billion of that segment’s premium inside captive networks, against $30.1 billion sold direct, and place Progressive’s share of the segment near 3.9%.
What is State Farm’s biggest weakness? The homeowners book. It lost $3.1 billion at a 107.7 combined ratio in 2025 and $6.7 billion across two years, and it did that in a year with no major US hurricane landfall.
Why did AM Best downgrade State Farm? AM Best cut the financial strength rating to A+ from A++ on November 14, 2025, citing a revision in operating performance from strong to adequate. The rationale named elevated loss ratios in auto and homeowners, a challenging regulatory environment, and weather losses from hurricanes, convective storms and wildfires. Balance sheet strength stayed at the strongest assessment level, and the outlook improved to stable.
Does State Farm’s agent network make it more expensive than direct insurers? Not against Progressive. State Farm’s 2025 underwriting expenses of $22.7 billion on $111.6 billion of earned premium give an expense ratio of 20.3%, and Progressive ran 20.3 to 20.4 companywide through 2025. GEICO is the genuinely low-cost operator at roughly 12.8. The comparison spans slightly different reporting bases, so read it as directional.
Does State Farm sell insurance directly? Barely. HiRoad Assurance, launched in Rhode Island in 2017 and extended to Arizona in 2021, is State Farm’s direct usage-based auto brand. It operates in those two states and AM Best assesses its operating performance as marginal. Customers can quote and buy State Farm policies online, but the policy is assigned to an agent.
What is State Farm changing about agent contracts? Every one of roughly 19,000 exclusive agent contracts is being replaced with a single standardized agreement. Health coverage for agents and spouses ends December 31, 2026, retired-agent Medicare supplement support ends at the same time, and commissions shift from trailing renewals toward new business, with reduced rates for agents who miss sales targets in consecutive years. Agents sign by 2028 or accept a buyout of $50,000 to $300,000 at State Farm’s discretion. Deferred compensation under the Annual Investment Payment Program continues through 2028 and becomes performance-linked from 2029.
The Business Model Analyst Take
The interesting thing about State Farm right now is that the received criticism is wrong and the real problem is worse.
Every competing analysis says the captive agent force is an expensive legacy that direct competitors have priced past. Run the numbers and State Farm converts premium into expense at the same rate Progressive does. The agent network is not a cost problem.
It is a speed problem, and a fixity problem. Progressive can decide in March to spend another billion dollars reaching households and see policies in July. State Farm’s equivalent lever is 19,200 independent business owners, each with an office lease and a staff, whose contracts pay them to keep what they already have. Turning that into a growth engine takes years, and Farney is trying to do it in eighteen months while the same people learn a new compensation formula and a new AI stack.
Behind all of it sits a balance sheet that is 72% common stock. State Farm has spent five years using capital to subsidize price, which bought loyalty and cost the AM Best rating. The subsidy works as long as the portfolio compounds. If equities give back a fifth of their value while the agent network is mid-transition, the mutual advantage that made all of this possible turns into the constraint that ends it.
Watch two things. The first is whether agent count holds through the 2028 signing deadline. The second is whether State Farm’s personal vehicle premium turns positive again in 2027. Everything else is commentary.