
State Farm is the largest home and auto insurer in the United States, and almost nothing about how it makes money resembles how its closest competitor makes money. Progressive prices risk and returns the surplus to shareholders. GEICO sells direct and hands its float to Berkshire Hathaway. State Farm has no shareholders at all, holds roughly four times as much capital per premium dollar as Progressive does, deliberately loses money on homeowners insurance year after year, and distributes its products through 19,200 offices whose owners it does not employ and whose books it does not let them keep.
That combination is not sentimentality about mutuality. It is a business model with a specific engine: State Farm uses an unusually heavy balance sheet to hold multi-product households through pricing cycles that force leaner competitors to move. In 2025 the model produced its best year in a decade. In 2026 the company started rewriting the contract that holds half of it together.
What is the State Farm business model? State Farm is a mutual insurance group with no external shareholders, owned in principle by its policyholders. It sells auto, homeowners, commercial, life and health products almost entirely through a network of exclusive independent-contractor agents who cannot sell competing carriers’ products. Revenue comes from premiums and investment income. Because there is no stock to issue and no dividend obligation to Wall Street, retained surplus is the company’s only source of capital, and that surplus is deployed to absorb underwriting losses, subsidize unprofitable lines, and fund policyholder givebacks that a listed insurer could not match.
At a Glance: State Farm in 2025
| Metric | 2025 | 2024 |
|---|---|---|
| Total revenue | $132.3B | $123.0B |
| Net income | $12.9B | $5.3B |
| Net worth, State Farm Mutual | $170.0B | $145.2B |
| P&C earned premium | $111.6B | $103.0B |
| P&C underwriting result | +$1.5B gain | $6.1B loss |
| P&C pre-tax operating profit | $8.5B | $111M loss |
| Auto earned premium | $71.3B | $67.5B |
| Homeowners, CMP and other earned premium | $39.2B | $34.5B |
| Life insurance in force | $1.22T | $1.18T |
| Policies and accounts | Over 96 million | n/a |
| Agent offices / employees | 19,200+ / 62,000+ | n/a |
The Structure Comes First: Fourteen Companies, One Brand, No Shareholders
Most write-ups treat “mutual” as a marketing adjective. At State Farm it is the load-bearing wall.
The group’s insurance operations consist of 14 property and casualty companies and two life companies, and State Farm’s own disclosure adds a line that most readers skip: each affiliate must satisfy solvency and regulatory requirements on an individual entity basis, without regard to the financial condition of any other affiliated entity. State Farm is not one $170 billion balance sheet. It is a family of separately capitalized balance sheets that share a brand, a claims organization, and a distribution force.
Three consequences follow, and they explain almost everything else about the model.
No equity market means no equity discipline, and no equity rescue. State Farm cannot issue stock. Every dollar of capital it will ever have must come from retained earnings or investment appreciation. That makes surplus accumulation the primary long-run objective rather than a byproduct, because surplus is the only currency the company can spend on growth, catastrophe capacity, or a bad decade.
The time horizon genuinely differs. Jon Farney, who became chief executive in June 2024, told the S&P annual insurance conference in June 2026 that the mutual structure “really does the best job of aligning long-term interest with customers.” Progressive’s own personal lines president has made the same observation from the other side, noting to trade press that mutual carriers price their products against different objectives and a different time horizon. When the competitor concedes the point, it is worth taking seriously.
Capital is not fungible across the family. This is the part almost nobody writes about, and California proved it in 2025.
Where the Money Actually Comes From
Auto is the business. It represented 63 percent of the property and casualty companies’ combined net written premium in 2025, on $71.3 billion of earned premium. Homeowners, commercial multiple peril and everything else made up 36 percent, on $39.2 billion. Life is comparatively small in premium terms at $6.9 billion but enormous in exposure, with $1.22 trillion of individual life insurance in force. Individual health is a rounding error at $756 million of net written premium, and it loses money.
The 2025 headline was a $1.5 billion property and casualty underwriting gain on $111.6 billion of earned premium, which works out to a combined ratio of roughly 98.7. Set against the 2024 combined ratio of about 105.9, that is a swing of more than seven points in a single year.
But the group number hides the mechanism. Split it by book and the model becomes visible.
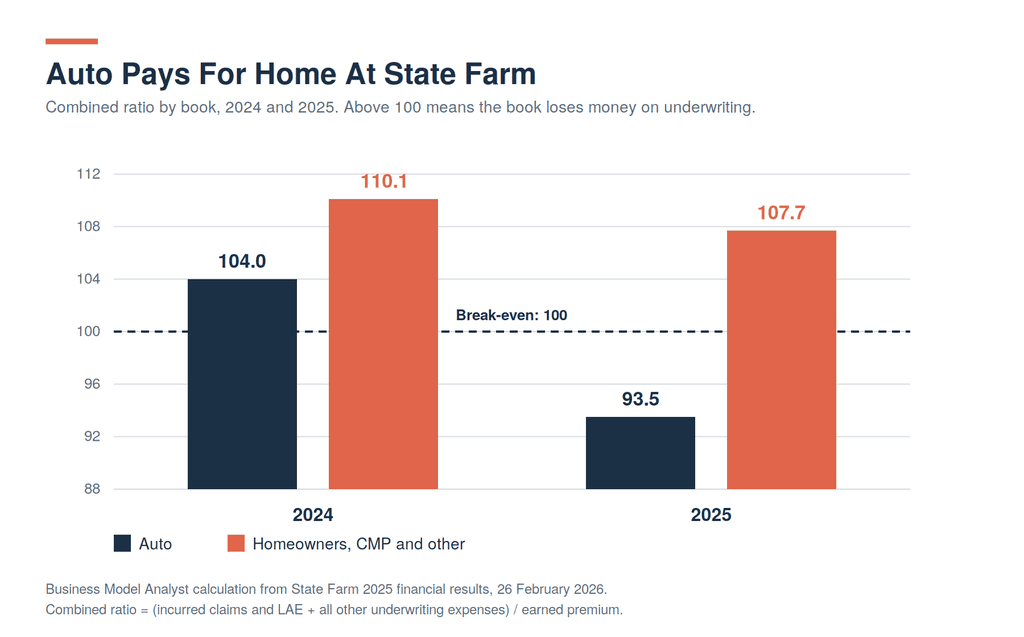
Auto ran a combined ratio of about 93.5 in 2025, down from 104.0 in 2024, producing a $4.6 billion underwriting gain. Homeowners, CMP and other ran about 107.7, an improvement on 110.1, and still lost $3.1 billion. The home book lost $3.6 billion in 2024 and $3.1 billion in 2025, a two-year underwriting deficit of $6.7 billion, and 2025 was the year it improved.
Bringing the home book merely to break-even at 2025 volumes would have consumed 67 percent of the auto underwriting gain. That is the trade State Farm makes on purpose.
Information Gain 1: The Cross-Subsidy Is the Product
The conventional framing is that State Farm bundles home and auto because bundling improves retention. True, but backwards. State Farm sells a structurally unprofitable product in order to hold a household that a structurally profitable product then monetizes.
Homeowners insurance in 2025 was not a margin business for State Farm and has not been one for years. Auto was. The bundle is the mechanism by which the loss-making line buys the switching costs that protect the profitable line. A multi-line household with a named local agent, a life policy, and fifteen years of claims history does not re-shop every renewal, which is precisely why the direct channel has never been able to price its way into the segment.
This is also why Progressive is spending so heavily to attack it. Progressive’s own investor materials describe consistently insured bundled households as roughly 35 percent of the US auto market where its share sits near 4 percent, with 85 percent of that premium sold through independent agents. The segment Progressive has identified as a roughly $20 billion opportunity is the segment State Farm already owns, and owns by running one half of it at a loss.
The vulnerability is symmetrical. State Farm’s home book is where climate risk lands, and the subsidy only works while auto is earning. Auto lost $2.7 billion in 2024. A repeat of 2022 and 2023, when the group posted underwriting losses reported in excess of $10 billion in each year, would put the subsidy and the retention machine under pressure at the same time.
Information Gain 2: The Balance Sheet Is the Competitive Weapon
Here is the number that separates State Farm from every listed competitor.
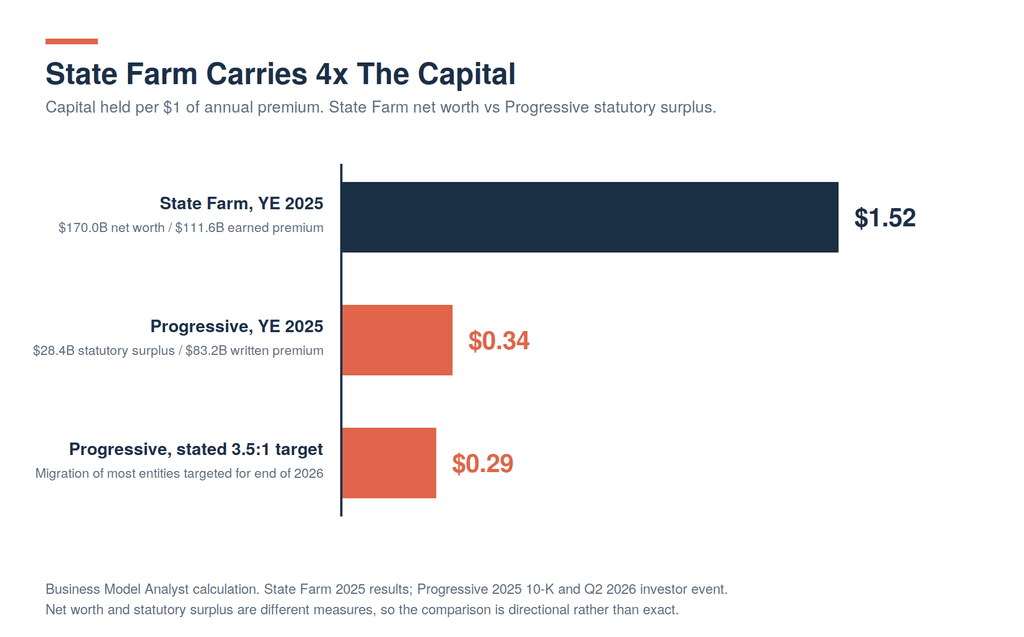
State Farm ended 2025 with $170.0 billion of net worth against $111.6 billion of property and casualty earned premium. That is about $1.52 of capital standing behind every dollar of annual premium. Progressive ended the same year with roughly $28.4 billion of statutory surplus against $83.2 billion of net written premium, or about $0.34, and has told investors it is migrating most of its entities to a 3.5-to-1 premium-to-surplus ratio by the end of 2026, which would take that figure toward $0.29.
Net worth and statutory surplus are different accounting measures, so treat the gap as directional rather than exact. Directionally, State Farm carries something like four times the capital per premium dollar that its closest rival does, and the rival is actively moving the other way.
Conventional analysis reads that as inefficiency. A listed insurer would be criticized for it, because idle capital drags return on equity. State Farm has no return on equity to defend. What the capital buys instead is the ability to be wrong for three years without changing strategy, and to lose money in California, Florida and the tornado belt without exiting.
That is the whole argument for the model. Progressive’s leverage converts pricing accuracy into growth faster than State Farm can. State Farm’s capital converts patience into retention longer than Progressive can afford.
Information Gain 3: The Giveback Exceeds the Earnings
In February 2026, State Farm announced a one-time $5 billion cash dividend to qualifying auto customers, on top of auto rate reductions in 40 states worth roughly $4.6 billion annually in lower premiums.
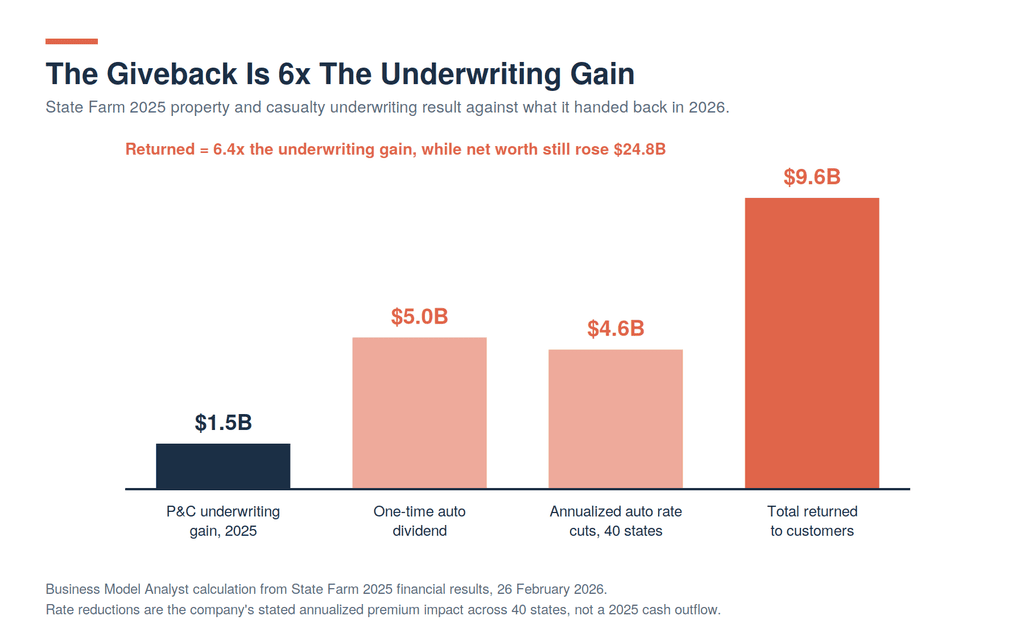
That is $9.6 billion returned against a $1.5 billion underwriting gain. The giveback is 6.4 times the entire underwriting result of the property and casualty group, and 1.1 times the $8.5 billion pre-tax operating profit that only reaches that level after $7.0 billion of investment and other income is added in.
The underwriting business did not fund the giveback. The balance sheet did. And the balance sheet barely noticed: net worth still rose $24.8 billion over the year, an increase State Farm attributes largely to appreciation in the property and casualty companies’ unaffiliated stock portfolios.
Read that sequence in competitive terms rather than benevolent ones. State Farm cut price across 40 states and mailed a $5 billion check in the same year Progressive was cutting new-business rates across states representing 63 percent of its premium and raising advertising spend. Both leaders are buying share at once, from opposite motives. Progressive is spending an unspent underwriting cushion because its framework says growth is the correct use of it. State Farm is spending investment gains because it has no other legitimate use for them. The customer sees the same thing: cheaper auto insurance from the two largest carriers simultaneously.
Information Gain 4: The Distribution Asset State Farm Owns, and the One It Does Not
State Farm reports more than 19,200 agent offices, over 62,000 employees, and over 96 million policies and accounts. That averages roughly 5,000 policies and accounts per agent office and about $6.9 million of group revenue per office.
The agents are independent contractors. State Farm does not pay their rent, their staff, or their utilities. But they are exclusive: they cannot sell a competitor’s product. And critically, they do not own their book. When an agent retires or leaves, the policies stay with State Farm and get reassigned. An independent agency principal can sell a book at a multiple of revenue. A State Farm agent gets whatever the contract provides.
That structure is a third distribution model, distinct from both of the ones the industry usually discusses. GEICO owns its distribution and pays for it directly. Progressive rents access to more than 40,000 independent agencies it does not control. State Farm gets control without ownership and scale without payroll, and it retains the customer asset that the distributor generates.
In 2026 the company began repricing that arrangement for the first time in decades. At an agent convention, Farney told the roughly 19,000 exclusive agents their existing contracts were being replaced with a single standardized agreement. Reported terms include the elimination of company-sponsored health coverage for agents and spouses at the end of 2026, restructuring of the Annual Investment Payment Program deferred compensation scheme, a shift in commission weighting from trailing renewals toward new business, mandated use of new AI tools, and a requirement to sign the new contract by 2028 or accept a discretionary buyout reported in the $50,000 to $300,000 range. A June 2026 partial reversal preserved deferred compensation payments through 2028 before tying them to sales targets. Some agents have described base commission reductions in the 35 to 40 percent range; State Farm has disputed that characterization.
Strip away the labor-relations framing and the business logic is legible. The captive agency force is the asset that holds the multi-product household, and it is also the most expensive distribution structure in personal lines at a moment when a quote costs nothing to generate. State Farm is trying to keep the retention benefit while lowering the unit cost, and it is using its own AI program to argue the cost can come out without the benefit going with it. That bet is unproven, and it is the single largest open question in the model.
Information Gain 5: California Showed Where the Mutual’s Capital Stops
In January 2025 the Palisades and Eaton fires became the most destructive wildfire insurance event in US history. State Farm’s California property risk sits in State Farm General Insurance Company, a separate subsidiary.
The parent had $145.2 billion of net worth at the end of 2024. State Farm General still had to file for emergency rate relief, submit to a public administrative hearing, and receive a $400 million capital injection structured as a surplus note that must be repaid with interest. State Farm’s own statement explained the structure plainly: customers outside California should not be expected to pay for risks in California.
That single sentence is the clearest available description of how the mutual actually works. The $170 billion is not a pooled reserve that flows to whichever affiliate needs it. It is capital held by entities that answer to their own regulators, and moving it requires permission.
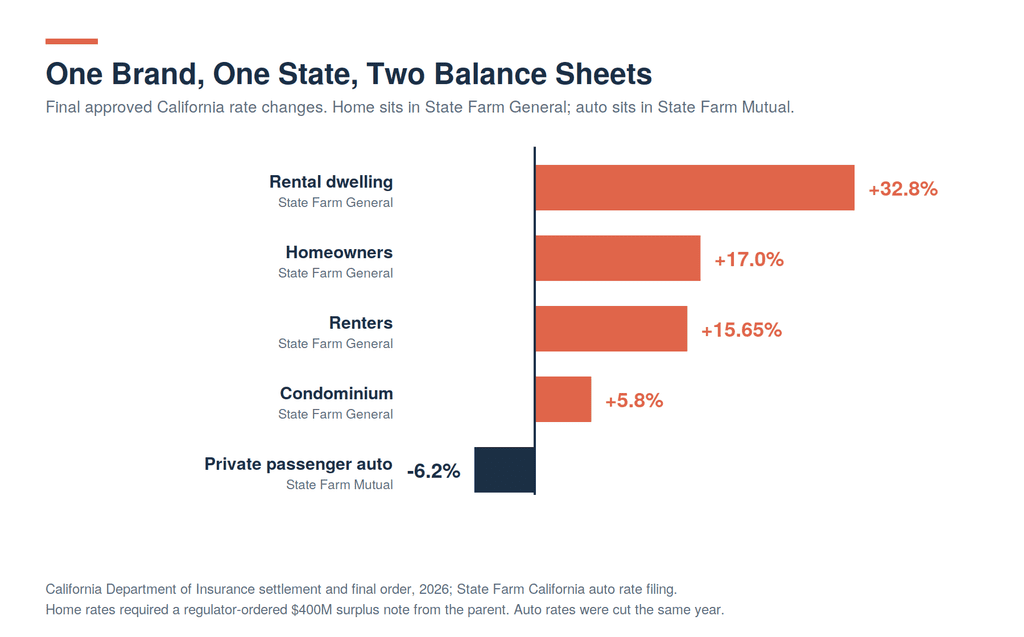
The endgame makes the point twice. A three-party settlement among the California Department of Insurance, Consumer Watchdog and State Farm General, finalized by the Commissioner in July 2026, held homeowners at the 17 percent interim increase rather than the roughly 30 percent originally sought, reduced condominium rates to about 5.8 percent and rental dwelling to 32.8 percent with refunds plus 10 percent interest, and set renters at about 15.65 percent. The settlement also wrote capital triggers directly into the rate order: State Farm General must return for review within 90 days of its premium-to-surplus ratio reaching 2 to 1, and must grant a one-time 2.5 percent premium discount when it reaches 1.5 to 1.
Meanwhile, in the same state and under the same brand, State Farm Mutual won approval to cut California private passenger auto rates by 6.2 percent. Two affiliates, one market, opposite directions, because they are two balance sheets.
State Farm General has also disclosed that over a nine-year window it paid $1.26 in losses for every premium dollar collected, producing more than $5 billion of cumulative losses. And the regulatory exposure did not end with rates: in May 2026 the Department filed an Accusation and Order to Show Cause alleging 432 violations of California’s Unfair Insurance Claims Practices Act in the handling of wildfire claims. At the statutory maximum of $10,000 per willful violation, the monetary penalty caps out around $4.3 million, which is roughly 0.0025 percent of the group’s net worth. The money is trivial. The license risk and the brand damage in a state where State Farm insures roughly one in five homeowners are not.
Market Position: Number One, With an Asterisk
On published NAIC data for data year 2025, State Farm held 18.64 percent of the US private passenger auto market with $69.164 billion of direct premiums written, against Progressive at 18.60 percent and $69.006 billion. The gap between first and second collapsed from $7.7 billion in 2024 to $158 million.
Be careful with the “Progressive has overtaken State Farm” headline. S&P Global Market Intelligence has shown Progressive ahead on a trailing-twelve-month basis through 31 March 2026, but its own note concedes that figure incorporates estimates for two New Jersey-domiciled Progressive subsidiaries that do not file public quarterly statements, and that public data still shows State Farm slightly ahead. On published annual filings, the overtake had not happened as of data year 2025. Treat it as contested rather than settled. The related question of what Progressive intends to do with its cash position is covered in our piece on Progressive dethroning State Farm, and the contrasting float-and-cost-of-capital model at GEICO sits inside Berkshire Hathaway’s business model.
What the Model Adds Up To
State Farm’s business model is a capital-financed retention machine. It accumulates surplus that no shareholder can claim, spends that surplus to stay in lines and states that leaner competitors would price out of, and uses an exclusive agency force to convert that persistence into multi-product households that do not shop. The underwriting result is an output, not the objective. In 2025 the underwriting result was $1.5 billion and the net worth increase was $24.8 billion, which tells you which one the company is actually managing.
The three pressures on it are all live right now. Climate risk keeps landing on the half of the book that already loses money. Regulators have started writing capital-leverage triggers and claims-conduct enforcement into the terms of doing business in the biggest states. And the agency force that makes the whole thing work is being asked to accept materially worse economics at the exact moment competitors are targeting the customers those agents hold.
FAQ
Is State Farm publicly traded? No. State Farm Mutual Automobile Insurance Company is a mutual insurer with no publicly traded stock. Policyholders are the nominal owners. There is no share price, no external equity issuance, and no obligation to pay shareholder dividends, which is why retained surplus is the company’s only capital source.
How does State Farm make money? Primarily from auto insurance premiums, which represented 63 percent of the property and casualty companies’ combined net written premium in 2025, plus investment income on the assets backing reserves and surplus. Life, health and investment planning services are comparatively small. In 2025, investment and other income of $7.0 billion contributed more to pre-tax operating profit than the $1.5 billion underwriting gain did.
Why does State Farm keep so much capital? Because it cannot raise any. With no equity market access, surplus is the only buffer against catastrophe years and the only funding for growth. The result is roughly $1.52 of net worth per dollar of annual property and casualty earned premium, against about $0.34 of statutory surplus per premium dollar at Progressive.
Are State Farm agents employees? No. They are independent contractors who hire their own staff, but they are exclusive and cannot sell competing carriers’ products. They also do not own their book of business; when an agent departs, the policies remain with State Farm and are reassigned.
Is State Farm leaving California? It has not exited. Its California property subsidiary, State Farm General, received emergency and then final approved rate increases, took a repayable $400 million surplus note from the parent, and agreed under a 2026 settlement to renew existing policies and pause new block non-renewals. Separately, State Farm Mutual cut California auto rates by 6.2 percent in 2026.
Is Progressive now bigger than State Farm in auto? It depends which data set you use. On published NAIC annual data for 2025, State Farm was still narrowly first at 18.64 percent versus 18.60 percent. Some trailing-twelve-month estimates put Progressive ahead, but those incorporate estimated figures for subsidiaries that do not file public quarterly statements. It is contested, not settled.
Why does State Farm lose money on homeowners insurance? Because it prices to hold households rather than to maximize line-level margin, and because catastrophe losses have outrun rate adequacy in several major states. The homeowners, CMP and other book lost $3.6 billion in 2024 and $3.1 billion in 2025. The auto book funds the gap.
The Business Model Analyst Take
The mistake most analyses make with State Farm is measuring it with a shareholder’s ruler. Judged on return on capital, a company holding $170 billion against $111.6 billion of premium and generating a 98.7 combined ratio looks slow and overcapitalized. Judged on what it is actually built to do, the capital is the product. It is what allows State Farm to keep writing homeowners insurance at a loss for the third straight year, to absorb the largest wildfire event in US history, and to hand back $9.6 billion in the same breath.
The uncomfortable question is whether that model still works when the quote is free. State Farm’s defense has always been the agent who knows your name and holds four of your policies. That defense costs more per policy than a direct quote engine and more than an independent agency relationship the carrier does not have to maintain. The 2026 contract reset is management admitting the cost is too high while insisting the benefit is intact. Both halves cannot obviously be true.
Watch two things. First, whether the 2027 to 2028 agent transition produces net attrition in offices, because the household lock is agent-shaped and there is no evidence yet that an AI claims workflow reproduces it. Second, whether the homeowners subsidy holds if auto normalizes; 2025’s 93.5 auto combined ratio is a peak-cycle number, not a run rate, and the rate cuts already announced will pull it back toward 100. If auto reverts while home stays above 105, the mutual’s patience will be tested against the one constraint it cannot vote its way around, which is a regulator in Sacramento holding a premium-to-surplus trigger.