SpaceX already broke the satellite industry. Now its Starlink unit is aiming at the one part of telecom it does not yet touch: the phone in your pocket. According to reporting from The Wall Street Journal, SpaceX President Gwynne Shotwell told investors this year that the company is weighing whether to build a ground network of its own to sell retail mobile service directly to consumers. If that sounds like a satellite company deciding to become a cell carrier, that is exactly the point, and it is a bigger deal for the business model than for the physics.
What Shotwell Actually Said
The trigger was an investor meeting tied to SpaceX’s recent IPO roadshow, first reported by the Financial Times and followed by the Journal. In it, Shotwell floated two ideas that go well beyond Starlink’s current role. First, a Starlink-branded retail mobile product sold straight to consumers. Second, and more striking, the possibility of building terrestrial infrastructure on the ground to support it.
That is a sharp departure from what Starlink does today. Right now it plays a supporting role: it beams a supplemental signal from orbit to fill dead zones for partner carriers. In the US, that partner is T-Mobile, whose T-Satellite service uses Starlink to keep phones connected where towers cannot reach. Selling its own plans would flip Starlink from a wholesale supplier into a direct rival of the same carriers it currently supplies.
Key Facts at a Glance
- 10.3 million Starlink subscribers as of March 31, 2026, across more than 160 countries (these are broadband customers, not mobile).
- $11.39 billion of SpaceX’s $18.67 billion in 2025 revenue came from Starlink, making it the company’s financial engine.
- Roughly $20 billion committed to wireless spectrum since 2025, led by the EchoStar deals (about $17 billion in September 2025 and $2.6 billion in November).
- 65 MHz of exclusive-use, nationwide mid-band spectrum cleared by the FCC in May 2026 (40 MHz of AWS-4, 15 MHz of unpaired AWS-3, and 10 MHz of H-Block).
- 0 direct retail mobile subscribers today. The three incumbents count roughly 399 million combined.
The Coverage Gap in Numbers
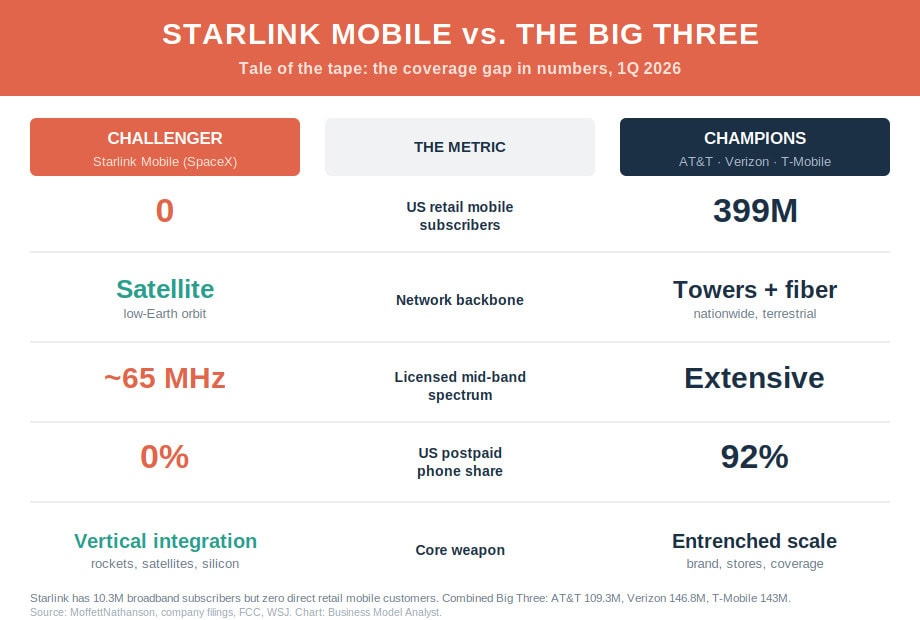
The tale of the tape makes the challenge obvious. On the metrics that decide a mobile market, subscribers, terrestrial reach, and licensed spectrum, Starlink starts at or near zero. What it brings instead is a different kind of weapon, and understanding that weapon is the whole story.
Why SpaceX Wants the Mobile Market
For SpaceX, mobile is not a side quest. Shotwell has said publicly that she expects Starlink mobile users to eventually outnumber Starlink broadband users, on the logic that far more people own a phone than a home internet subscription. The addressable market is the entire connected population, not just rural households underserved by fiber.
There is also a business model logic that founders will recognize. SpaceX has a habit of walking into industries it sees as static and refusing to buy from suppliers when it can build the input itself. As LightShed Partners telecom analyst Walt Piecyk put it, the company behaves like Tesla: if it cannot get the car seat it wants from a supplier, it makes its own car seat. Owning the retail relationship, rather than renting Starlink capacity to T-Mobile for a cut, captures the margin and the customer data that the carrier currently keeps.
This is vertical integration used as a competitive weapon. SpaceX already owns the rockets, the satellites, and increasingly the custom silicon inside them. Adding the retail layer would let it control the full stack from orbit to invoice. For more on how that model already works in orbit, see our breakdown of the Starlink business model.
The Spectrum and Hardware It Has Quietly Assembled
A retail carrier needs airwaves, and SpaceX has been buying. The EchoStar transactions gave it exclusive-use spectrum rather than the borrowed, carrier-provided frequencies its direct-to-cell service relied on before. That distinction matters: exclusive spectrum is the legal and technical foundation for running a network SpaceX actually controls. It also picked up two cellular licenses in a recent FCC auction for about $8.5 million, a rounding error next to the EchoStar spend but a signal of intent.
On the hardware side, SpaceX has been developing next-generation Starlink Mobile satellites, marketed as V2, which the company says will deliver roughly 20 times the throughput of the first generation using thousands of spatial beams and custom antennas. It has also shown a prototype handset to investors. The pieces of a consumer mobile business are being stacked in plain sight.
The Hard Part: Satellites Cannot Win Cities
Here is where the hype outruns the physics, and where a sharper reading pays off. Satellite connections are slower and weaker on phones than terrestrial links, and they struggle exactly where most revenue lives: dense urban areas, inside buildings, and in tunnels. Analysts are near unanimous that to serve those locations, SpaceX would have to build a ground network, which means becoming the capital-heavy terrestrial carrier it is supposedly disrupting.
Verizon Chief Executive Dan Schulman made the incumbent case bluntly at a March conference, arguing that terrestrial infrastructure remains the best option for connectivity and speed by a wide margin. He is talking his book, but he is not wrong on the engineering. Cell towers and fiber pipe large amounts of cheap bandwidth to always-on subscribers, and no constellation currently matches that in a crowded city. Starlink’s own direct-to-cell layer is designed to activate when a phone loses terrestrial coverage, not to replace it.
There is also a spectrum gap. Around 65 MHz of exclusive mid-band is a real asset, but it is a fraction of what AT&T and Verizon hold. Spectrum is the raw material of network capacity, and on that measure Starlink is bringing a knife to an artillery duel.
How the Incumbents Are Already Fighting Back
The carriers are not waiting to find out whether the threat is real. Reporting indicates the three declined MVNO deals with SpaceX ahead of the IPO, denying it an easy wholesale on-ramp into their networks. They then moved to form a joint venture focused on shared spectrum in underserved areas, the very rural gaps where satellite is strongest. Verizon and AT&T have also aligned with AST SpaceMobile, a rival satellite-to-phone player, hedging their own exposure to a Starlink-only future.
Verizon under Schulman has adopted openly aggressive language, positioning the company as the predator rather than the prey. The competitive reflex is telling: incumbents defending a market this large will spend heavily to keep a new entrant boxed into the low-value rural fringe.
Signal or Leverage? Read the Timing
Before treating this as a done deal, weigh the timing. Shotwell aired these plans at an IPO roadshow, roughly two weeks after SpaceX’s record public offering. A company selling shares has every incentive to describe the largest possible future market, and mobile is a far bigger story than rural broadband.
Several analysts read the disclosure as deliberate leverage. By signaling that it could compete directly, SpaceX makes itself more threatening to its own carrier partners and can extract better terms on future agreements, particularly from T-Mobile as exclusivity windows expire. In that reading, the terrestrial network is as much a negotiating chip as a committed build. It might get built. It might also be a very expensive way to say “give us a better deal.” Both can be true at once, and the smart money watches capital expenditure, not press quotes, to tell them apart.
What to Watch Next
- Capex commitments. A real terrestrial build shows up as spending on towers, backhaul, and RAN equipment. Until that appears, this is strategy, not construction.
- The T-Mobile relationship. Whether the partnership deepens, cools, or renegotiates will reveal if this is competition or leverage.
- Spectrum moves. Further mid-band acquisitions would signal seriousness about urban capacity.
- Pricing and timeline. SpaceX has confirmed no pricing or launch date for a retail product. Any concrete number changes the calculus fast.
The Business Model Analyst Take
The lazy headline is “satellites versus cell towers.” The real story is a vertically integrated platform company probing whether it can envelop an entire industry from a layer the incumbents cannot reach: orbit. Starlink will not replace your urban 5G connection any time soon, and it may never build a full terrestrial network. But it does not have to win the whole market to reshape it. If Starlink becomes the default coverage layer everywhere towers stop, it commoditizes the one thing carriers have historically charged a premium for, which is being reachable. That erodes the rural moat, resets the terms of every partner deal, and forces incumbents to spend defensively.
The lesson for operators is not about telecom. It is about where competitive advantage is migrating. When a company controls a scarce upstream asset, in this case cheap access to space, it can keep pushing downstream into adjacent markets on its own schedule. The question for AT&T, Verizon, and T-Mobile is not whether Starlink can beat them at their own game. It is whether Starlink can change the game before they finish defending the old one.
Frequently Asked Questions
Can Starlink replace my phone carrier today?
No. Starlink’s current mobile service is a supplemental layer that fills dead zones when you lose terrestrial coverage. It is not a full replacement for a traditional carrier, especially in cities.
Is SpaceX definitely building a mobile network?
Not confirmed. Shotwell described building a ground network as something the company is considering, disclosed at an investor roadshow. SpaceX has announced no pricing, timeline, or firm commitment.
How many subscribers does Starlink have?
About 10.3 million as of March 31, 2026, across more than 160 countries. Those are broadband subscribers, not retail mobile customers.
Why would a satellite company build cell towers?
Because satellites cannot deliver strong service inside buildings, in tunnels, or in dense cities. To compete for those high-value customers, SpaceX would need terrestrial infrastructure, which is why analysts see a ground network as a prerequisite for a full mobile business.