Stanley 1913 can change its steel, its factories, its freight lanes and its retailers. It cannot unweld a vacuum. That single irreversible step sets the warranty, kills the resale market, and turns the company’s recycling program into a melting program.
Stanley Value Chain Analysis at a Glance
What it is: A breakdown of the primary and support activities Stanley 1913 uses to turn stainless steel coil into a tumbler someone carries to a soccer game, and where the margin and the risk sit in each step.
Who runs it: PMI WW Brands, LLC, the Seattle operating company behind the Stanley 1913 brand, now a sibling company to logistics operator HAVI under Morgan Street Holdings.
The finding: Sort the chain by reversibility instead of by value added. Steel can be melted and remelted, so Stanley moved recycled content from 1% of stainless units in 2021 to 81% in 2025. The vacuum seal cannot be opened, so no repair node exists and no resale market forms. Freight cannot be undone either, and it is the node that got 5.5 times worse.
Why it matters: The 2026 growth plan adds coolers, totes and lunch bags. Those categories sit outside the recycling loop Stanley built, and they already pulled the recycled share of total materials down from 65% to 55% in a single year.
Every value chain analysis asks the same question in the same direction. Raw material comes in on the left, a customer pays on the right, and the analyst counts the margin added at each stop. Run that exercise on Stanley and you get a chain that looks like a hundred other consumer hardware chains: buy coil, form it, weld it, coat it, ship it, sell it, service it.
Read the chain in the other direction and it stops looking generic. Ask which steps can be walked backward. Steel comes apart and goes back into the furnace. Powder coat burns off. Boxes flatten. A supplier contract ends. But at one point on the line, two shells of stainless get joined and the air between them gets pulled out to roughly one ten-thousandth of a torr, a getter alloy gets sealed inside to hold that vacuum for decades, and the fill tube gets closed. After that moment the object is permanent. Nobody at Stanley, at a repair shop, or at a recycler can open the cavity, restore the vacuum, and put the product back into service.
That weld sits in the middle of the chain and it explains the rest of it. The lifetime warranty is a replacement promise rather than a repair promise because there is nothing to repair. The refurbished market that thrives around coolers and bags never formed around vacuum bottles. The Take Back program disassembles and melts instead of renewing. Read Stanley’s chain by what can be undone and the strategy stops looking like sustainability positioning and starts looking like physics with a marketing department attached.
The only public map of the chain is a carbon ledger
PMI WW Brands publishes no segment financials, so the usual value chain inputs are missing. No cost of goods split, no freight line, no plant list with capacity. What the company does publish, once a year, is a greenhouse gas inventory. That inventory is an accounting of activity by node, and it happens to be the most detailed public description of the Stanley value chain in existence.
The 2026 Impact Report, covering calendar 2025, splits the footprint four ways: materials at 54%, manufacturing at 18%, transportation at 17%, and operations and everything else at 11%.
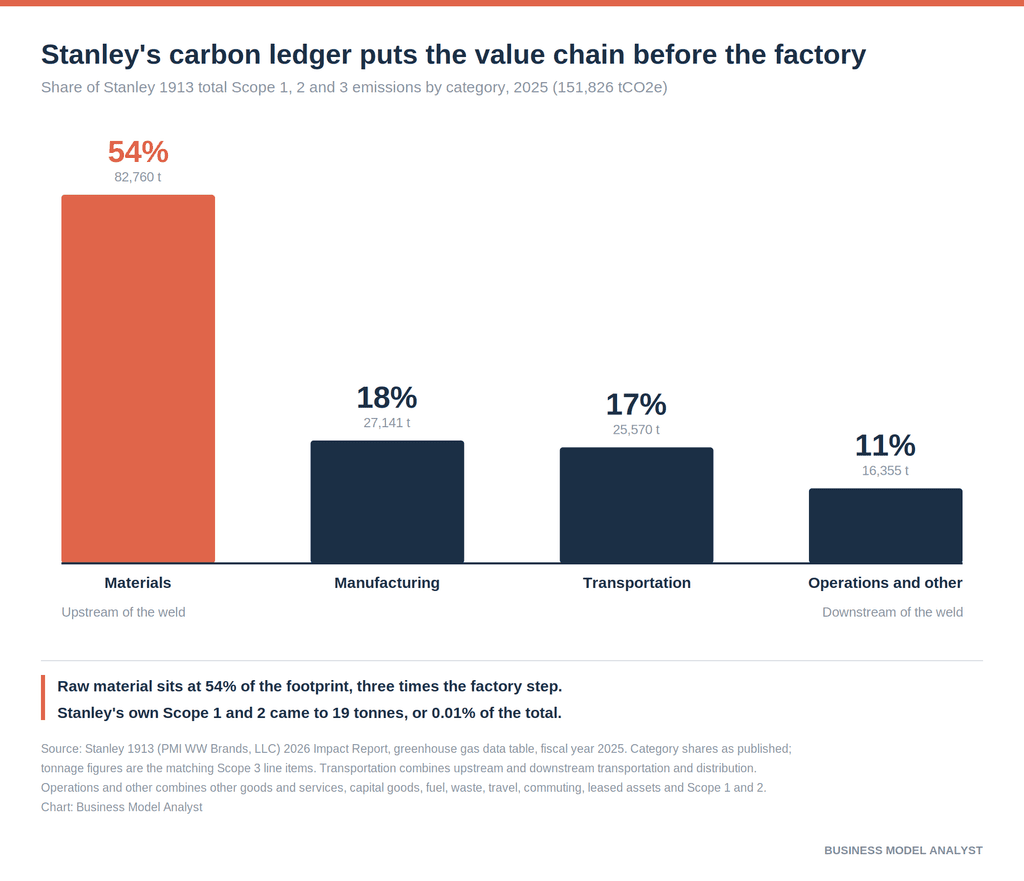
Two numbers in that report reframe the whole company. Total Scope 1 and Scope 2 emissions for 2025 came to 19 metric tons. Scope 3 came to 151,807. The entity that designs, brands and sells Stanley products accounts for roughly one hundredth of one percent of its own value chain footprint, and the report notes that all of its office locations are leased.
A business with 19 tons of direct emissions does not run factories. It buys from them. Trade coverage and older corporate profiles describe PMI as holding equity in three plants, one in China and two in Brazil, and that history is well documented. What the current reporting boundary shows is different: manufacturing energy and materials appear under purchased goods and services, supplied by what the report calls tier 1 manufacturing suppliers, audited by Stanley’s own compliance team. Whether the equity positions moved during the 2022 restructuring of Pacific Market International or whether they sit outside the reporting entity is not disclosed anywhere the research reached. Either way, on the only ledger the company publishes, Stanley owns none of the steps that make its product.
That matters for the reversibility question. A company that rents every node can change any of them, in principle. The constraint is not ownership. It is whether the step can be walked backward at all.
Inbound materials: the node Stanley fixed, because steel goes backward
Stainless steel is the most reversible input in consumer hardware. It melts, it separates by grade, and 18/8 coming out of a furnace performs the same whether the scrap arrived from a demolished building or a dead tumbler. No redesign required, no tooling change, no new supplier qualification beyond the mill.
Stanley moved fast on exactly that. Recycled stainless went from 1% of units produced in 2021 to 24% in 2022, 63% in 2023, 73% in 2024 and 81% in 2025, against a target of 50% by 2025 set at the start. The company estimates the switch avoided 64,000 metric tons of emissions in 2025, about 30% of what its total would otherwise have been, and it now holds Recycled Claim Standard certification on the Quencher Flowstate, the Quencher ProTour, IceFlow Flip Straw tumblers and the Classic Legendary bottles.
Speed like that is only available where the material cooperates. Compare the plastics. Lids, straws, stoppers and cooler bodies made up 23% of product weight in 2025, and 21 of those 23 points were conventional plastic. Recycled plastics reached 2%. The company relaunched hard coolers at roughly 50% recycled plastic and began using recycled Tritan in Quencher Luxe handles, but polymer degrades on each cycle and food contact rules narrow the eligible feedstock, so the reversal that took four years in steel has taken longer in resin.
The composition table tells the story on one line. Recycled stainless is 51% of product weight. Conventional stainless is another 22%. Everything else, all 27% of it, is the part of the product that resists going backward.
The weld: where the chain stops being a chain
Manufacturing accounts for 18% of the footprint and close to 100% of the strategic constraint.
The process is well documented in the patent literature and among contract manufacturers who build these vessels for the whole category. A flat stainless blank goes into a deep draw press, or a tube goes into a hydroforming die, and comes out as a seamless body. A second body gets formed to nest around the first. The two get joined at the neck and base. The cavity between them gets evacuated in a vacuum furnace, a non-evaporable getter alloy gets fixed inside to absorb outgassing over the product’s life, and the evacuation port gets sealed.
Nothing downstream of that seal is serviceable. A dented outer shell cannot be pushed back out, because pushing it out means gripping the inner wall that no tool can reach. A failed vacuum cannot be pulled again, because the port is gone. A scratched powder coat can be lived with or thrown away. The vessel is a single part that happens to look like an assembly.
Every service decision Stanley makes follows from that. The lifetime warranty covers the stainless body against defects and thermal performance loss, and excludes lids, seals and straws, a split this site examined at length in the Stanley SWOT analysis. The company’s own circularity diagram in the 2026 Impact Report lists five consumer steps, and the one labeled repair and spare parts points to a single destination: extra lids and straws sold on the website. The repair node in a 112-year-old durable goods company consists entirely of the components its warranty refuses to cover.
Outbound logistics: the node getting worse, at the company that sits next to a logistics operator
Upstream transportation and distribution emissions went from 3,200 tons in 2021 to 20,635 in 2025. Downstream went from 1,482 to 4,935. Combined, freight rose 5.5 times while the total footprint slightly less than doubled.
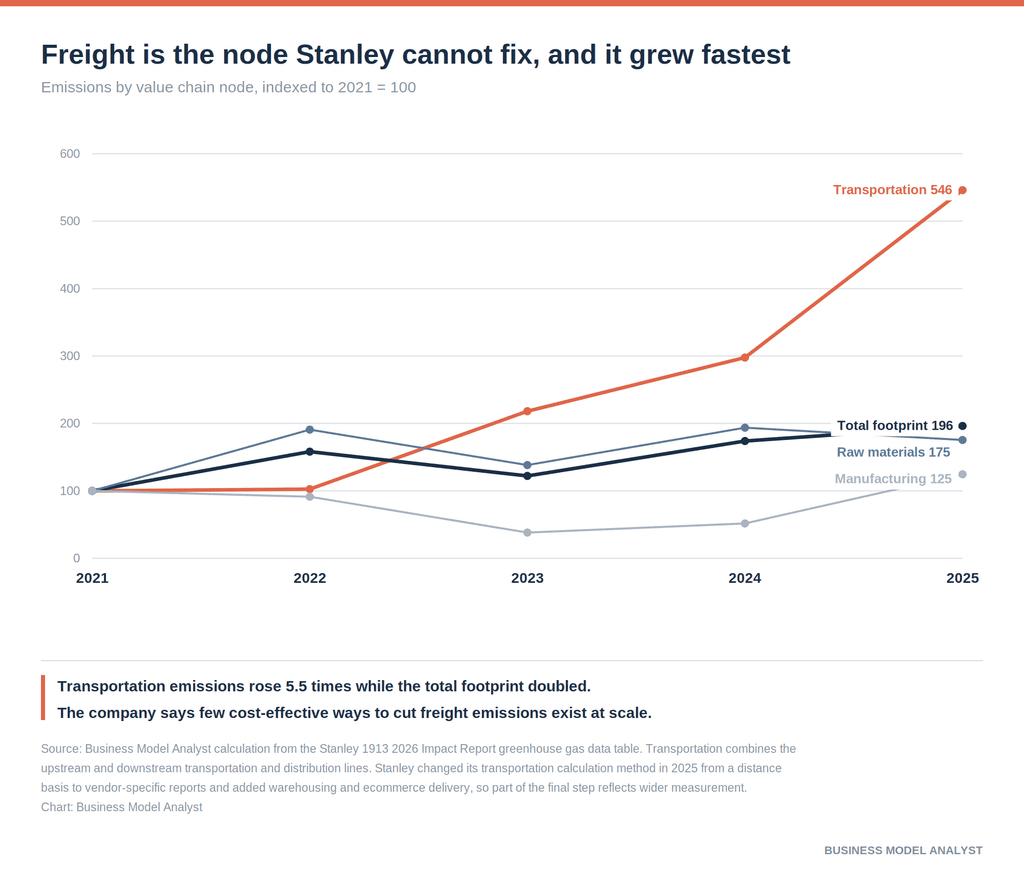
Part of that jump comes from better counting. Stanley switched from a distance-based method to vendor-specific reports in 2025 and folded in warehousing and ecommerce delivery for the first time. Strip the method change and the trend still points the same way, because the 2021 to 2024 period used one consistent method and freight tripled inside it.
The report’s own language on the node is blunter than anything else in the document. Cutting transportation emissions is described as the next frontier, with few cost-effective solutions available at scale. That is a company saying it has no lever.
The awkward part is who lives next door. Stanley 1913 sits under Morgan Street Holdings alongside HAVI, a supply chain operator running more than 75 distribution centers, around 1,000 trucks and over two million deliveries a year across 20-plus markets. Stanley does not appear on any of HAVI’s service pages. It appears only in the holding company’s portfolio list. The sibling network moves temperature-controlled food to restaurant chains on daily routes. Stanley ships bulky retail cases to distribution centers and single tumblers to doorsteps. Same family, incompatible physics, no transfer.
Freight punishes this product harder than most. A 40 ounce vacuum tumbler is mostly sealed void by volume, and ocean and parcel rates price cube rather than value. Every container Stanley moves is paying to ship the insulation gap that makes the product work.
Support activities: what the audits show
Procurement is where the 2026 expansion shows up first, and not flatteringly.
At the end of 2022, Stanley reported that 100% of its third-party manufacturers had achieved the top score on its ethical sourcing audit. In 2025, 37% of tier 1 manufacturing suppliers earned an A for social compliance. The company attributes the drop to two things it did on purpose: onboarding new suppliers across new categories and geographies, and raising the audit bar. Both explanations are credible and both point at the same cause. Adding occasions means adding factories that do not yet meet the standard the old factories met.
Supplier energy moved the other way. Tier 1 suppliers sourced 4% of their electricity from renewables in 2021 and 62% in 2025, with 13.6 million kilowatt hours of onsite solar generated in 2025. Stanley also pushed corporate social responsibility standards into tier 2 in 2025, with all participants trained and 77% providing audits aligned to its compliance standards.
Technology development stays close to the product. The company expanded prototyping and testing at its Seattle headquarters in 2025 and opened a dedicated color, material and finish studio, which is the physical embodiment of a business that ships variance rather than invention. Firm infrastructure is thin by design: leased offices in the United States, China, Brazil and the Netherlands, and a footprint that shows up as 19 tons of Scope 1 emissions.
| Node | Can it be undone | Evidence in Stanley’s own data | What the company did |
|---|---|---|---|
| Raw material | Yes, indefinitely | Recycled stainless 1% to 81% of units, 2021 to 2025 | Reversed it, fast, and certified the claim |
| Plastics and textiles | Partly, with degradation | Recycled plastics at 2% of product weight in 2025 | Relaunched coolers at about 50% recycled resin |
| Forming and coating | Yes, before the seal | Tooling and finish sit with suppliers | Runs color variance on amortized tooling |
| Vacuum seal | No | No repair channel exists for the vessel | Replaces under warranty, melts at end of life |
| Freight and warehousing | No, distance is fixed | Transportation emissions up 5.5 times since 2021 | States no cost-effective solution at scale |
| Retail and DTC | Yes | About 20 localized storefronts | Adds and drops channels at will |
The recycled content number that moved backward
Stanley’s headline sustainability metric counts stainless steel units. Its whole-portfolio metric counts everything by weight. The two moved in opposite directions in 2025.

Recycled stainless hit 81% of units. Recycled share of all materials by weight fell from 65% to 55%. The report names the cause: a more diverse product mix, including products made entirely from lighter-weight materials such as textiles, plus better supply chain visibility.
That is the tooling cost of the occasion strategy showing up in a second currency. This site’s Stanley target market analysis covered how the company shifted from segmenting people to segmenting moments, and the product answer to that shift was soft goods, coolers and lunch sets. Each new occasion adds a material Stanley has not solved yet. The steel program keeps improving while the portfolio it sits inside keeps diluting it.
End of life: the natural experiment Yeti already ran
Stanley launched Take Back in September 2025. Log the product online, print a prepaid label or show a QR code at a drop point, and the item goes to a US recycling partner where it is disassembled, sorted and recycled. Stanley says early tests recover about 96% of materials in a reusable state. Participants get a $5 credit, and Stanley donates $5 to Ocean Conservancy per item.
The terms are where the analysis lives. Four items per person per year. Contiguous 48 states only, and the FAQ gives the reason: shipping from Alaska and Hawaii would emit more than local disposal. That is a company publishing the finding that its own reverse logistics leg goes underwater past a certain distance, which is the freight problem from the previous section restated as a policy.
Eligibility excludes hard and soft coolers, accessories and partial items, and requires the product body. The categories driving 2026 growth cannot enter the loop.
Then there is the donation structure. Stanley guarantees a minimum of $50,000 a year and caps at $200,000. At $5 an item, the company has published a floor of 10,000 items and a ceiling of 40,000.
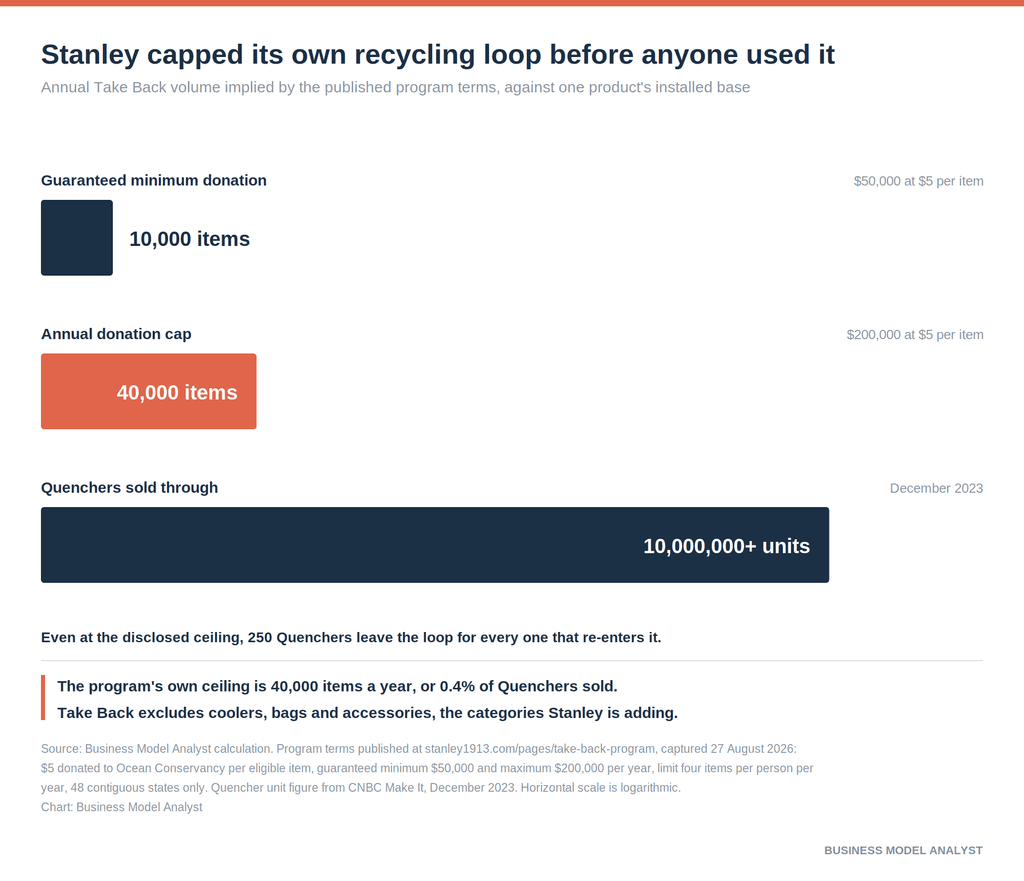
More than 10 million Quenchers had sold by December 2023, one product line, before two more years of volume. Against that base, the disclosed ceiling of the circular program is about 0.4% a year. The company’s letter reports $50,000 donated in the program’s first few months, which reads like a result until you notice it equals the guaranteed minimum, so it may be a floor payment rather than evidence of 10,000 returns. Stanley has disclosed a bound, not an outcome.
One more detail sits in the page source. As of August 27, 2026, the Take Back landing page carries a noindex, nofollow robots directive. The flagship circularity program is not competing for search traffic.
Yeti tested the same physics and split its answer in two, which is the cleanest available proof that the vacuum seal drives this rather than brand philosophy.
| Reversible products | Vacuum-sealed drinkware | |
|---|---|---|
| Yeti program | Yeti Rescues, launched 2023 | Rambler Buy Back |
| What happens | Coolers, bags and cargo are repaired or renewed and resold, graded by condition through a resale partner | Sorted, disposed and recycled |
| Customer gets | Nothing, they are the buyer | $5 per item in store credit, up to $50 |
| Revenue line | Yes | No |
| Stanley equivalent | None, coolers and bags are excluded from Take Back | Take Back, $5 credit, four items a year |
Same company, same customer, same year. The cooler comes back, gets fixed and sells again at a price. The tumbler comes back and gets melted for $5. Yeti and Stanley, working independently, arrived at the identical figure for a dead vacuum vessel: five dollars, paid in store credit, capped.
The difference between the two programs is the difference between a product held together by fasteners and a product held together by a weld.
Where the chain breaks
Three pressures point at the same seam.
Freight keeps growing as a share of the footprint while Stanley says it has no scaled solution, and the product’s cube-to-value ratio is set by the insulation gap it sells. International expansion across roughly 20 storefronts stretches those lanes further, and Stanley’s competitors face the same math with different exposure. Yeti moved its contracted network out of China and reported holding tariff-exposed Chinese goods below 5% of cost of goods sold, an option that reads differently for a company whose supplier base has produced in China since 2002. The comparison between the two supply bases is drawn out in more detail in our Yeti competitors breakdown.
Supplier quality is the second seam. Going from every third-party manufacturer scoring an A to 37% of tier 1 suppliers scoring an A is the audit trail of a company adding capacity faster than it can qualify it. Consumer hardware failures land hard on this chain, as the 2025 recall of 2.6 million Switchback and Trigger Action travel mugs over a burn hazard demonstrated. A product with no repair path converts a quality miss straight into replacement cost.
The third is the one the reversibility frame surfaces. Stanley’s improvement record is concentrated in the node where material physics did the work. Steel let itself be fixed. Freight will not, plastics are slow, and the vacuum seal was never negotiable. The 2026 plan adds textiles, resin and cube on the wrong side of the door while the steel program approaches its ceiling at 81%.
Frequently Asked Questions
What is a Stanley value chain analysis? It maps the primary activities that move stainless steel from a mill to a customer, covering inbound materials, forming and vacuum sealing, outbound freight, marketing and sales, and after-sale service, plus the support activities of procurement, technology, human resources and firm infrastructure. If you want the framework itself before applying it, our guide to value chain analysis examples walks through the structure.
Does Stanley manufacture its own products? On the only ledger the company publishes, no. The 2026 Impact Report puts total Scope 1 and 2 emissions at 19 metric tons for 2025 and describes all offices as leased, with manufacturing energy and materials recorded as purchased goods and services from tier 1 suppliers. Older profiles describe PMI holding equity in plants in China and Brazil. The company has not disclosed how those positions relate to the current reporting entity.
Why can’t a Stanley tumbler be repaired? The insulating cavity is sealed under vacuum during manufacturing and the evacuation port is closed permanently. Reopening it destroys the vacuum, and no tool reaches the inner wall. The stainless body is effectively one part, which is why Stanley replaces vessels under warranty and sells spare lids and straws rather than offering repair.
What does Stanley’s lifetime warranty actually cover? Stainless steel vacuum products are covered against defects and loss of thermal performance for the life of the product, with lids, seals and straws excluded. Soft goods carry a three-year limited warranty. The excluded parts are the plastic components, which are also the parts furthest behind on recycled content.
How much recycled material is in a Stanley product? Stanley sourced recycled stainless steel for 81% of stainless units produced in 2025, up from 1% in 2021, and units in that count contain at least 90% recycled content. Measured across all materials by weight, recycled content was 55% in 2025, down from 65% in 2024 as textiles and plastics entered the mix.
How does the Stanley Take Back program work? US customers in the 48 contiguous states register an eligible steel or stainless product online, ship it free with a prepaid label or drop it at a partner location, and receive a $5 store credit while Stanley donates $5 to Ocean Conservancy. The limit is four items per person per year. Coolers, accessories and partial items are not accepted, and returned products are disassembled and recycled rather than refurbished.
How does Stanley’s supply chain compare with Yeti’s? Yeti contracts its manufacturing across Vietnam, the Philippines, Thailand, Mexico, Cambodia, Indonesia, Malaysia and the United States, and cut tariff-exposed Chinese goods below 5% of cost of goods sold. Stanley’s supplier base has produced in China since 2002 and is expanding into new geographies for soft goods. Yeti also monetizes end of life through resale on non-sealed products, a channel that does not exist for either company’s drinkware.
Where does Stanley make money in the chain? Value capture concentrates in brand and channel rather than in any manufacturing step. The company runs color and collaboration variance on tooling that suppliers have already amortized, then sells across direct, wholesale and about 20 international storefronts. The mechanics of that demand engine are covered in our Stanley marketing strategy breakdown.
The Business Model Analyst Take
Stanley’s chain rewards the analysis that runs it backward. Sorted by reversibility, the company’s whole record makes sense: it moved 80 points of recycled steel in four years because steel let it, it built a recycling program instead of a refurbishment business because the weld gave it no choice, and it has no answer on freight because distance does not negotiate.
The strategic risk is that the 2026 plan spends on the wrong side of the seal. Coolers, totes and lunch sets add resin and textile weight that dilutes the material metric, add suppliers that fail the audit standard the old ones passed, add cube per dollar to the node already growing three times faster than the business, and sit outside the only take-back loop the company operates. Each of those is a small cost. Together they describe a chain getting less reversible while the strategy calls for more flexibility.
The fix is not another material target. Stanley’s steel program is close to its practical ceiling. The next real gain sits at the seal: designing a vessel that can be opened, serviced and put back into use would create the resale line Yeti already earns on its coolers and would give the installed base a reason to transact with the company more than once. Every competitor faces the same weld. Whoever gets past it first stops selling replacements and starts selling a second life.