
Stanley 1913 spent eight months and more than 5,000 interviews across six countries trying to find its next customer. What it came back with was not a person. It was a distinction between a routine and a ritual.
That is a stranger outcome than it sounds, and it is the single most useful fact for anyone trying to understand who Stanley sells to in 2026. Every competing analysis of this company answers the target market question with a portrait: millennial and Gen Z women, roughly 25 to 44, wellness-adjacent, TikTok-fluent, suburban. That portrait was accurate for about four years. It is now a description of the installed base, not of the buyer Stanley is chasing.
What is Stanley’s target market? Stanley 1913 targets an interest-based segment it calls the stylish achiever, defined by health, sport and music affinities rather than by age or gender, with roughly 60 to 65 percent of that base having children at home. In practice the company now segments by occasion rather than by person: hydration, coffee and cafe, sport and gameday, lunch and back-to-school, and travel and commute, sold across twenty localized international storefronts. The old Quencher Woman cohort remains the revenue base. The growth thesis is selling that same household a second, third and fourth vessel for occasions it has not yet assigned one to.
That shift is worth taking seriously, because it changes what growth even means for this company.
What a target market is, and what it is not
A target market is the specific group a company designs, prices and distributes for. It is not the same as the customer base, which is whoever actually bought. The gap between the two is where strategy lives.
Companies describe target markets three ways. Demographic segmentation sorts by age, gender, income and geography. Psychographic segmentation sorts by values, interests and self-image. Occasion or behavioral segmentation sorts by the situation in which the product gets used.
The choice is not cosmetic. A demographic segment has a hard ceiling equal to the number of people in it. An occasion segment does not, because one person carries several occasions. Which framework a company picks tells you whether it expects to grow by finding new buyers or by getting more out of the ones it has.
The portrait everybody else is still selling
The received version of Stanley’s target market comes from a real moment. Three women running an Instagram shopping account with an audience skewed heavily toward women aged roughly 35 to 44 found the Quencher, championed it, and set off the most documented consumer product renaissance of the decade. We covered the mechanics of how that turned into a repeatable demand engine in our Stanley marketing strategy breakdown, and there is no need to relitigate it here.
Graham Nearn, chief product and sustainability officer at PMI WW Brands, splits the company’s history into three eras. From roughly 1913 to 2020, Stanley made work and outdoor gear for a primarily male audience. From 2020 to 2024, the Quencher brought in a primarily female one. Since 2024, the company has been building the third era.
Here is the problem with the era-two portrait as a forward-looking target market. Piper Sandler’s spring 2025 Taking Stock With Teens survey, covering 6,455 US teens with an average age of 16.2, asked female teens to name top fashion trends. Stanley cups landed in the top five. In the same survey, the same teens also put Stanley cups in the top five trends on their way out.
A brand can survive being unfashionable. What it cannot survive is being the load-bearing symbol of a cohort that has decided to move on, which is exactly what identity-based positioning risks. Piper Sandler has since moved the survey from semi-annual to annual, with the 2026 edition due in the fall, so that spring 2025 reading is still the most recent structured teen data available on the brand.
Meanwhile the category itself cooled. Circana’s point-of-sale tracking showed water bottle and insulated container sales at US sporting goods retailers declining year over year every month from September 2024 through February 2025, and category growth at those retailers falling from 38 percent in 2023 to 14 percent in 2024. Matt Navarro, PMI WW Brands’ global president, described it plainly at a March 2025 event as a settling of the hydration category in the US.
So the demographic that made Stanley famous is aging out of the trend, and the category it dominates has stopped compounding. That is the setup for everything that follows.
What Stanley actually segments by now
Kate Ridley, the chief brand officer who arrived from Allbirds and Adidas, refers to the loyalists as the Quencher Woman, and she is explicit that the company intends to keep nurturing them. But the segment Stanley now designs for has a different name and a different logic. Ridley calls it the stylish achiever, and describes it as a group united not by demographics but by shared interests: health and wellbeing, sport, music.
Two attributes of that segment matter more than the label.
The first is that it has children. Ridley put the share of the target base with kids at home at over 65 percent in January 2026 and at 60 percent in July 2026. That is not a large gap, and different interviews round differently, but it is worth logging that the household figure moved down five points over six months as the definition of the segment widened. Either way, the majority of Stanley’s intended buyer base is a household, not an individual.
The second is the research finding underneath it. The eight-month, 5,000-consumer, six-country study Ridley commissioned did not produce a persona. It produced a distinction. A routine is something you repeat. A ritual is something you do with intention and attach meaning to. Ridley’s examples are how someone makes their matcha, how obsessive they are about brewing coffee, how they meal prep for the week.
That is an occasion framework wearing a psychographic coat. And the company’s product cadence follows it exactly. Between mid-February and mid-April 2026, Stanley shipped the Vitalize collection of backpacks, totes and shaker bottles, the Clutch Bottle, and the Flowstate Spring Bottle. It has since added cafe products including the Transit Flip Top Mug and the Cafe-To-Go Travel Mug. Ridley counts five new product lines in ten weeks, coordinated by roughly fifty global leaders across design, product, marketing and supply chain working from the same consumer insight set.
None of those launches is aimed at a new demographic. Every one of them is aimed at a moment the existing buyer already has and has not yet bought a Stanley for.
The evidence sitting in the navigation bar
Company strategy documents are aspirational. Navigation menus are operational, because they are built by people whose job is conversion. Stanley’s US storefront in August 2026 carries both segmentation schemes side by side, and it is a useful measure of how far the transition has actually traveled.
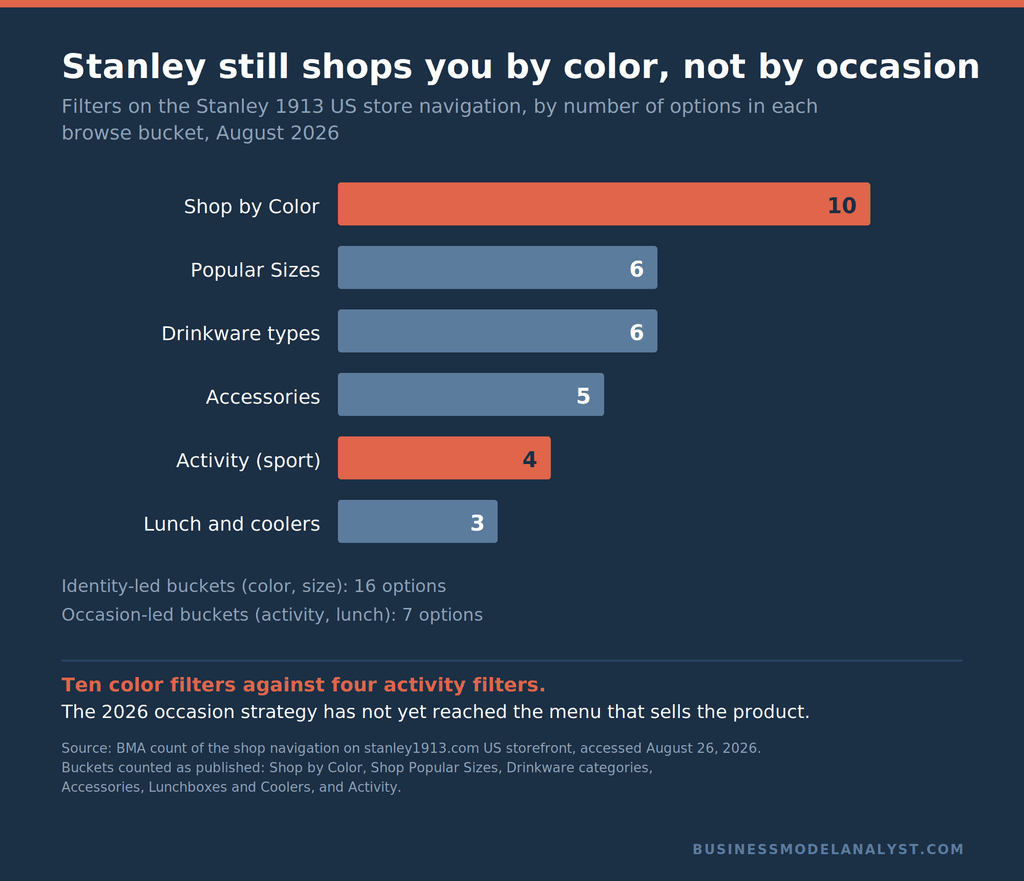
There is a Shop by Color menu with ten entries, which is the era-two identity model in its purest form: the product is the same, the color is the choice, and the choice says something about you. There is a Shop Popular Sizes menu with six entries. And there is an Activity menu with exactly four: soccer, golf, basketball, camping and hiking.
Sixteen identity-led options against seven occasion-led ones. The strategy has been announced, staffed and funded. It has not yet reached the menu.
Where it has reached is the merchandising layer above the menu. The trending tiles in that same navigation in August 2026 were tailgating, back-to-school hydration, and a lunch set. Not colors. Not collabs. Three occasions, each with a date attached.
The four buyer groups Stanley is actually working
Pulling the company’s own statements, product cadence and storefront structure together, Stanley’s 2026 target market resolves into four groups. They overlap, which is the point.
| Group | Who they are | What Stanley sells them | Evidence |
|---|---|---|---|
| The hydration base | The Quencher Woman cohort, skewing 25 to 54, the installed base of 10 million-plus Quencher owners | Replacement colorways, ProTour leakproof upgrades, accessories and charms | Consumer Edge puts Stanley at roughly 30% of US direct-to-consumer bottle spend, with most traction among 25 to 54 |
| The ritual owner | The same person at a different hour: coffee, matcha, mate, meal prep | Cafe-To-Go, Transit Flip Top Mug, camp cookware, food containers | The routine-versus-ritual finding from the six-country study; the cafe line launched off it |
| The gameday fan | Sports followers of both genders, reached through clubs and athletes rather than through media buys | Club and athlete collections, soccer and golf and basketball collections, tailgating | Messi, Arsenal, PSG, Juventus, Caitlin Clark, Nelly Korda, Collin Morikawa; Stanley Sessions football activations |
| The household buyer | The 60 to 65% of the target base with kids at home, buying for people who are not themselves | Back-to-school bottles, lunch gear, Vitalize bags with an insulated bottom compartment | Ridley names back-to-school lunch gear as an open category; the Vitalize tote sold out in DTC within a week of its February 17 launch |
The fourth group is the one most analyses miss entirely, and it is the one that changes the arithmetic.
Why occasions beat audiences: the arithmetic
Here is the mechanism, and it is not a marketing conceit.
Americans do not own a reusable water bottle. They own several. A survey of more than 3,000 US adults aged 21 to 60, fielded by EverVessel with Statista between August 28 and September 5, 2024, found that 85 percent own and use a reusable water bottle, and that they own an average of four each.
Four. That is the base case, not an aspiration.
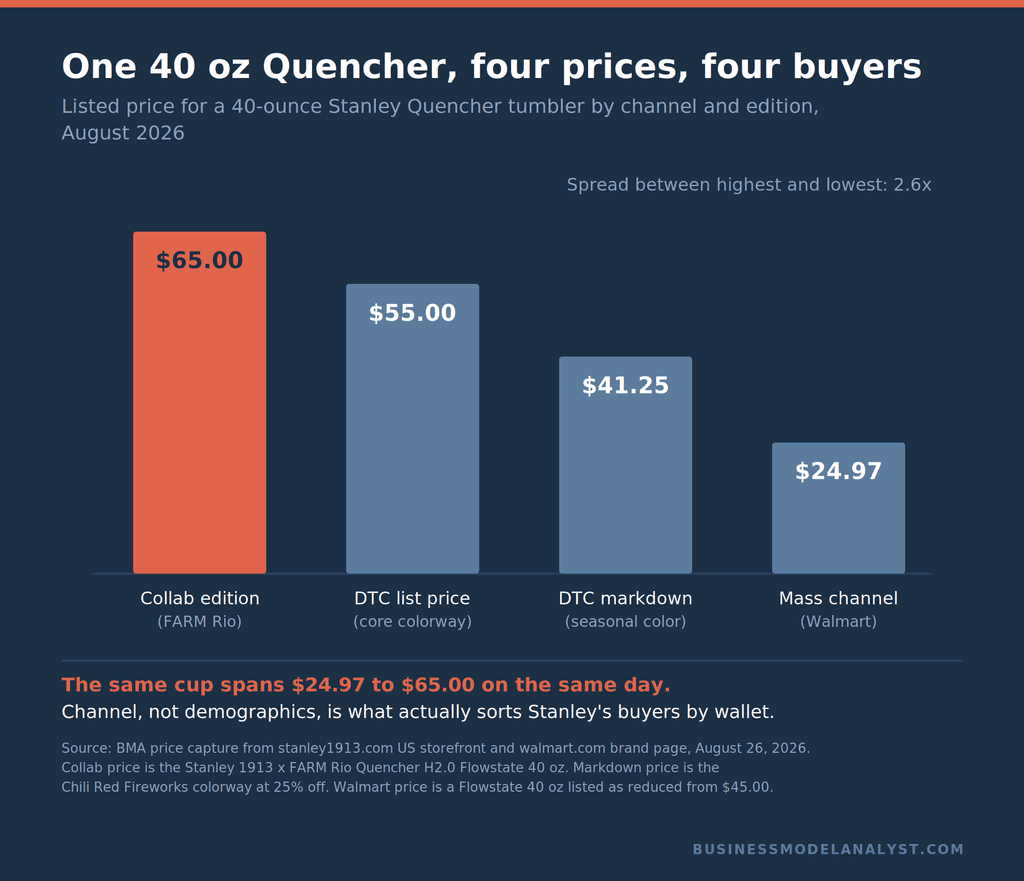
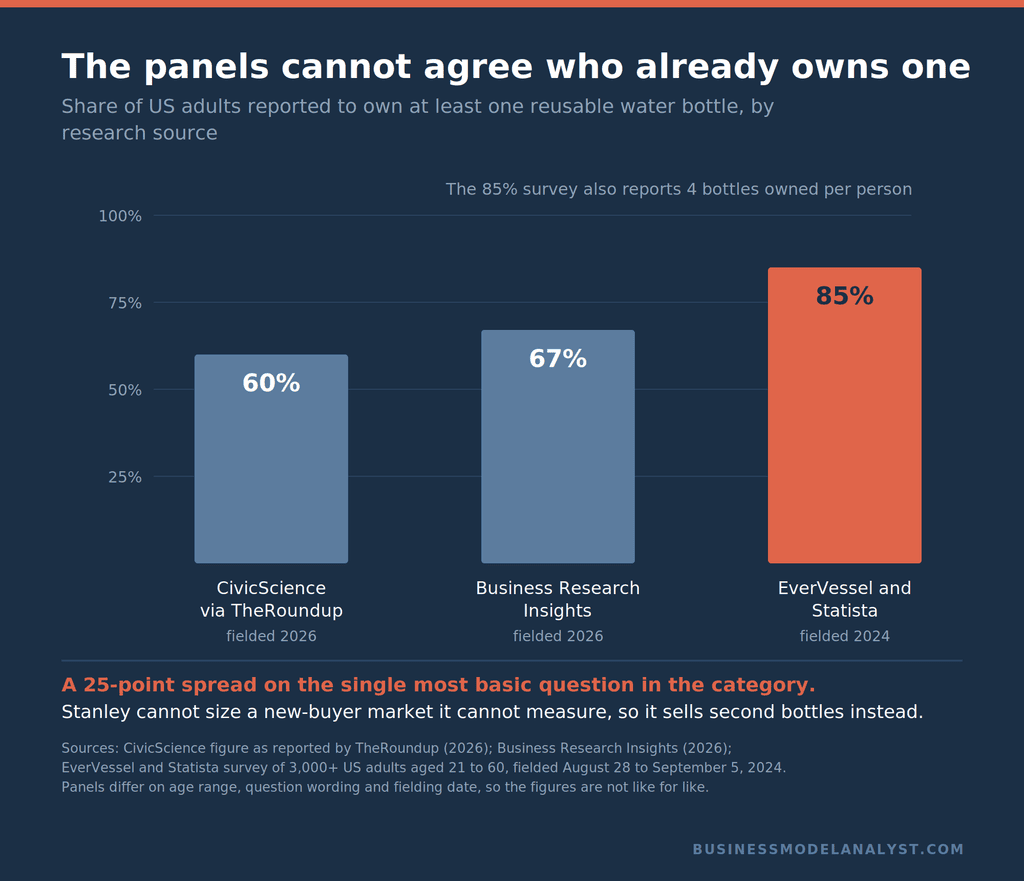
The panels disagree wildly on the headline penetration number. CivicScience data reported by TheRoundup puts 2026 ownership at 60 percent of US adults, roughly 155 million people. Business Research Insights puts it near 67 percent owning at least one, with 44 percent owning two or more. EverVessel and Statista put it at 85 percent among 21 to 60 year olds. Different age frames, different question wording, different fielding dates, and a 25-point spread on the most basic question in the category.
That spread matters strategically. A company cannot size a new-buyer opportunity it cannot measure. It can, however, count the vessels already in the cupboards of people it has already sold to.
And the same survey explains why the number is four rather than one. Fifty-one percent of respondents replace a bottle within the first year and 32 percent within six months, with 40 percent citing odor or hygiene as the reason and 56 percent saying the bottles are difficult and time-consuming to clean.
Read that as a segmentation input rather than a product complaint. A vessel that carried coffee does not go back to water. A vessel that carried a protein shake does not go back to matcha. Flavor and odor transfer make each vessel functionally single-purpose, which means the multi-bottle household is not a fashion outcome. It is a physics outcome. Stanley’s occasion strategy is not inventing a behavior. It is finally selling into one that already exists and that the brand has been leaving on the table for four years.
Stanley’s own fan research points the same direction from a different angle. In a global survey the brand commissioned with sports fandom researcher Daniel Wann, 48 percent of fans said gameday food and drink is non-negotiable, 44 percent insisted on the same snack or beverage every match, and 39 percent reported relying on what the brand calls emotional support drinkware, a specific lucky cup used to feel calm during tense moments.
That last figure is the most commercially interesting statistic Stanley has published. It describes a buyer who owns a cup that is deliberately not substitutable, cannot be used for anything else, and therefore requires a second cup for everything else. It is the first published evidence the company has offered that anyone needs more than one.
The gift buyer nobody has been writing copy for
The household group carries a structural feature the other three do not: the buyer and the user are different people.
Back-to-school gear, teacher and nurse appreciation gifts, kids’ bottles, and club merchandise for a fan in the family are all purchases made by one person on behalf of another. That decouples purchase frequency from personal replacement cycles entirely. A household of four with a lifetime-warranted steel body in every hand still buys, because the occasions keep arriving on a calendar.
It also happens to be the part of the market Stanley has served worst. Ridley acknowledged to Digiday in August 2026 that the brand’s occasion marketing had been heavy on imagery and light on copy explaining use and occasion. Imagery works for a buyer who already knows what they want. It fails for a buyer searching for something to give to a person whose preferences they are guessing at, and it fails harder in a search environment where the answer is being assembled from text.
The company’s loyalty program, the Stanley 1913 Club, is where this gets operationalized. Enrollment collects a birthday in exchange for a promised gift, and requires the member to be 18 or older. That birthday field is the only first-party occasion signal Stanley captures at sign-up. For a brand pivoting to occasion segmentation, it is a thin instrument, and an obvious place to expand.
The international buyer, market by market
The other route to more purchases without more Americans is more countries.
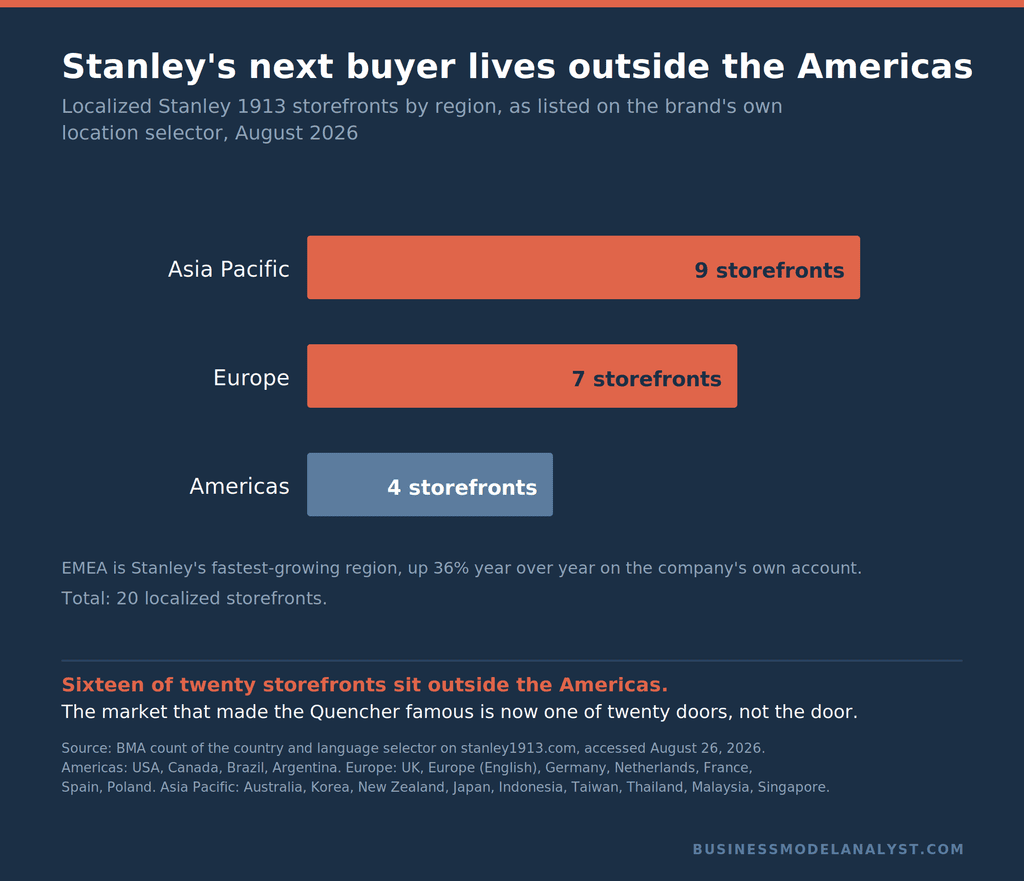
Stanley’s own location selector in August 2026 lists twenty localized storefronts. Four sit in the Americas: the United States, Canada, Brazil and Argentina. Seven cover Europe: the United Kingdom, a pan-European English store, Germany, the Netherlands, France, Spain and Poland. Nine cover Asia Pacific: Australia, Korea, New Zealand, Japan, Indonesia, Taiwan, Thailand, Malaysia and Singapore.
Sixteen of twenty doors sit outside the Americas, and Ridley says EMEA is the fastest-growing region at 36 percent year over year, driven specifically by European coffee and commuter culture. Navarro has separately named the UK, Germany, Spain, France, Japan, China, Korea, Australia and New Zealand as focus markets, plus the Middle East.
Note what EMEA growth is attributed to. Not a demographic. An occasion, and specifically the one that Stanley’s original 1913 product was built for. The European commuter buying a Transit mug is not the Quencher Woman in translation. It is a different ritual with a different vessel, sold to a market where the 2020 to 2024 identity wave never fully landed and therefore never has to be unwound.
The price ladder is an occasion ladder
Stanley does not publish revenue by brand or by segment, because PMI WW Brands is private and reports nothing. But the price architecture is public every day, and it sorts buyers more honestly than any persona does.
On a single day in August 2026, the same 40-ounce Quencher format carried four different prices. The Stanley 1913 x FARM Rio collaboration listed at $65.00. The core colorway listed at $55.00. A seasonal colorway sat at $41.25 after a 25 percent markdown. And Walmart listed a 40-ounce Flowstate at $24.97, reduced from $45.00.
A 2.6x spread on functionally the same object. Owala, the brand that took the US stainless steel bottle lead in 2023, sits at roughly $20 to $35, which places the marked-down Stanley squarely inside Owala’s range and the Walmart Stanley below it.
That is the real segmentation. The collab buyer is buying a drop. The full-price DTC buyer is buying a specific colorway for a specific reason. The markdown buyer is buying a cup. The Walmart buyer is buying a cup that happens to say Stanley. Four wallets, one SKU family, and no demographic variable required to tell them apart.
How Stanley’s target market compares to the category
| Stanley 1913 | Yeti | Owala | |
|---|---|---|---|
| Stated segmentation basis | Interest-based (“stylish achiever”), moving toward occasion | Activity and quality-driven premium buyer, split across outdoor core and drinkware mainstream | Everyday hydration, value-forward |
| Core historical buyer | Tradespeople and outdoors, then women 25 to 44, now households | Hunters and fishing guides, then a mainstream drinkware buyer | Mainstream US bottle buyer |
| Typical 40 oz price | $45 to $65 at list, less on markdown and in mass channels | Premium, supported by a 57% gross margin | Roughly $20 to $35 |
| Financial visibility | None. PMI is private and publishes no brand-level figures | Public and audited, the only clean proxy for the category | None. Private |
| Growth vector | More occasions per household, plus twenty international storefronts | International mix and category expansion into fitness and cookware | US share gains on lid design |
Yeti is the only auditable read on this category, which is why our Yeti target market analysis is a useful cross-check on anything Stanley says about demand. The two companies are converging from opposite directions: Yeti moving from an activity identity toward the mainstream cup, Stanley moving from the mainstream cup back toward activity. Our Yeti competitors breakdown covers where the two collide, and the Yeti SWOT analysis covers what the collision costs.
What would break this thesis
Occasion segmentation sounds clean on a slide. Four things could stop it working.
Every occasion needs its own SKU. Colors are cheap to add because the tool is the same. Occasions are not. A cafe mug, a shaker, a lunch box and a tote are four tooling programs, four inventory lines and four sets of retail shelf negotiations. Stanley’s own product team says the normal cycle from brainstorm to prototype runs about three years, which sits awkwardly against a cadence of five lines in ten weeks. Something is being compressed, and compression in hard goods usually shows up later as a quality or recall event. The company already recalled 2.6 million Switchback and Trigger Action travel mugs in 2025 over a burn hazard, and travel mugs are precisely the cafe-occasion product the new strategy leans on.
The occasion buyer still gets a lifetime warranty on the part that never breaks. Our Stanley SWOT analysis works through how the coverage terms shape replacement behavior, so we will not repeat the argument here. The short version is that adding occasions increases units per household without shortening the life of any of them.
The household number is a company estimate with no audit trail. Sixty to sixty-five percent of the target base having kids at home is a figure from brand interviews, not a disclosure. PMI publishes no financials, no cohort data and no segment splits. Every quantitative claim in this analysis about Stanley’s own buyer comes either from a third-party panel or from an executive in a trade interview, and the panels themselves disagree by 25 points on the simplest question in the category.
The men may not come. Reconquering a male buyer via soccer, golf and basketball is the least proven leg of the plan. Ridley’s evidence for it is largely anecdotal and largely delightful: Arsenal players holding up Stanley pints unprompted at a parade that drew 1.3 million people against an expected 300,000, and Messi drinking mate from a Stanley since childhood. Those are good signals about brand permission. They are not yet evidence of purchase behavior, and Stanley publishes nothing that would let anyone check.
Frequently asked questions
Who is Stanley’s target market in 2026? Households in the 25 to 54 range organized around interests rather than demographics, which Stanley internally calls the stylish achiever. Roughly 60 to 65 percent of that base has children at home. The company designs for occasions inside that household rather than for a single user profile.
Is Stanley still targeting women? Yes, as the retained base. Ridley describes the Quencher Woman cohort as fans the company will keep nurturing. But the incremental spend is aimed at men, parents buying for children, and international commuters. The brand describes it as an opportunity to develop deeper relationships with more men, not as a replacement of the existing audience.
What age group buys Stanley cups? Consumer Edge purchase data shows the strongest traction among 25 to 54 year olds. Younger buyers remain reachable but volatile: in Piper Sandler’s spring 2025 teen survey, female teens ranked Stanley cups both a top-five fashion trend and a top-five trend on the way out.
Is Stanley a luxury brand? No. It is premium mass. A 40-ounce Quencher listed at $55.00 direct in August 2026, with collaborations reaching $65.00 and mass-channel listings as low as $24.97 for the same format. That price band sits above Owala and below any accepted definition of luxury.
Who owns Stanley? The Stanley 1913 brand is operated by PMI WW Brands, LLC of Seattle, which acquired the rights to Stanley and Aladdin in 2002. PMI has been a business unit of The HAVI Group, LP since September 1, 2021. PMI publishes no brand-level financials.
How many countries does Stanley sell in directly? The brand’s location selector listed twenty localized storefronts in August 2026: four in the Americas, seven in Europe and nine in Asia Pacific. Ridley identifies EMEA as the fastest-growing region at 36 percent year over year.
Who are Stanley’s main competitors? Owala, which took the US stainless steel bottle lead in 2023 on lid design, Yeti, Hydro Flask, Simple Modern, BruMate, HydroJug and Corkcicle. Yeti is the only publicly reporting comparison in the set.
Why is Stanley moving into bags and lunch gear? Because those are occasions its existing buyers already have. The Vitalize line launched February 17, 2026, sold out its tote in direct-to-consumer channels within a week and became Amazon’s top new release in gym totes and backpacks, which suggests the demand was waiting rather than created.
The Business Model Analyst Take
The interesting thing about Stanley’s target market is not who is in it. It is that the company has quietly stopped answering the question in the form it was asked.
Ask most consumer brands who they sell to and you get a person with an age, an income and a set of aspirations. Ask Stanley and you get a study about the difference between a routine and a ritual, a store menu organized by sport, a trending shelf full of tailgates and lunch boxes, and a product calendar that ships five lines in ten weeks aimed at five different hours of the same person’s day.
That is a rational response to the position the company is actually in. Stanley cannot grow the way it grew from 2019 to 2023, because that growth came from converting a demographic that has now converted, in a category where the panels cannot even agree whether penetration is 60 percent or 85 percent. It cannot grow much on replacement, because a steel body outlives its owner’s interest in it. What is left is the arithmetic of the cupboard: Americans already keep four of these things, they keep them because coffee and water and protein powder cannot share a vessel, and until 2026 Stanley was only ever selling into one of those four slots.
The risk is that occasion strategies are expensive in a way identity strategies are not. A new color is a purchase order. A new occasion is a tooling program, an inventory line, a retail negotiation and a warranty exposure. Stanley is running that expansion with a compressed development cycle, inside a private company that discloses nothing, in a category that just spent two years decelerating. That is a lot of operational risk to carry on the strength of an insight, however good the insight is.
But the insight is good. The most telling number Stanley has put into public view this year is not a revenue figure or a market share. It is that 39 percent of sports fans keep a lucky cup they will not use for anything else. A company that understands why that is a business model and not a curiosity has found something more durable than a color of the month.